


Nebius Group has given shareholders a sharp ride, with the price now well off recent highs after a strong multi‑year climb. That puts fresh focus on whether the current valuation is still supported by its sales. After that kind of swing, the key issue is how much ongoing revenue the market is effectively paying for at today’s level.
- Over the past 5 years the stock has gained 64.8%, which puts a lot of weight on the question of how much sales power is now embedded in the share price.
- Recent headlines around project delays, tighter financing conditions and a major customer reassessing neocloud spending can affect expectations for Nebius Group’s future revenue growth, margin profile and the timing of cash coming back into the business.
- There is a second opinion on Nebius Group worth weighing. See what analysts think Nebius Group's shares could be worth.
The stock’s next move may depend on whether Nebius Group’s current market value is well grounded in the sales it is generating today and what investors expect that top line to look like over time.
If you want a second reference point while you assess Nebius Group’s recent swings and sales multiple, run the same lens across a focused list of 53 AI infrastructure stocks.
Is Nebius Group a Bargain on Sales?
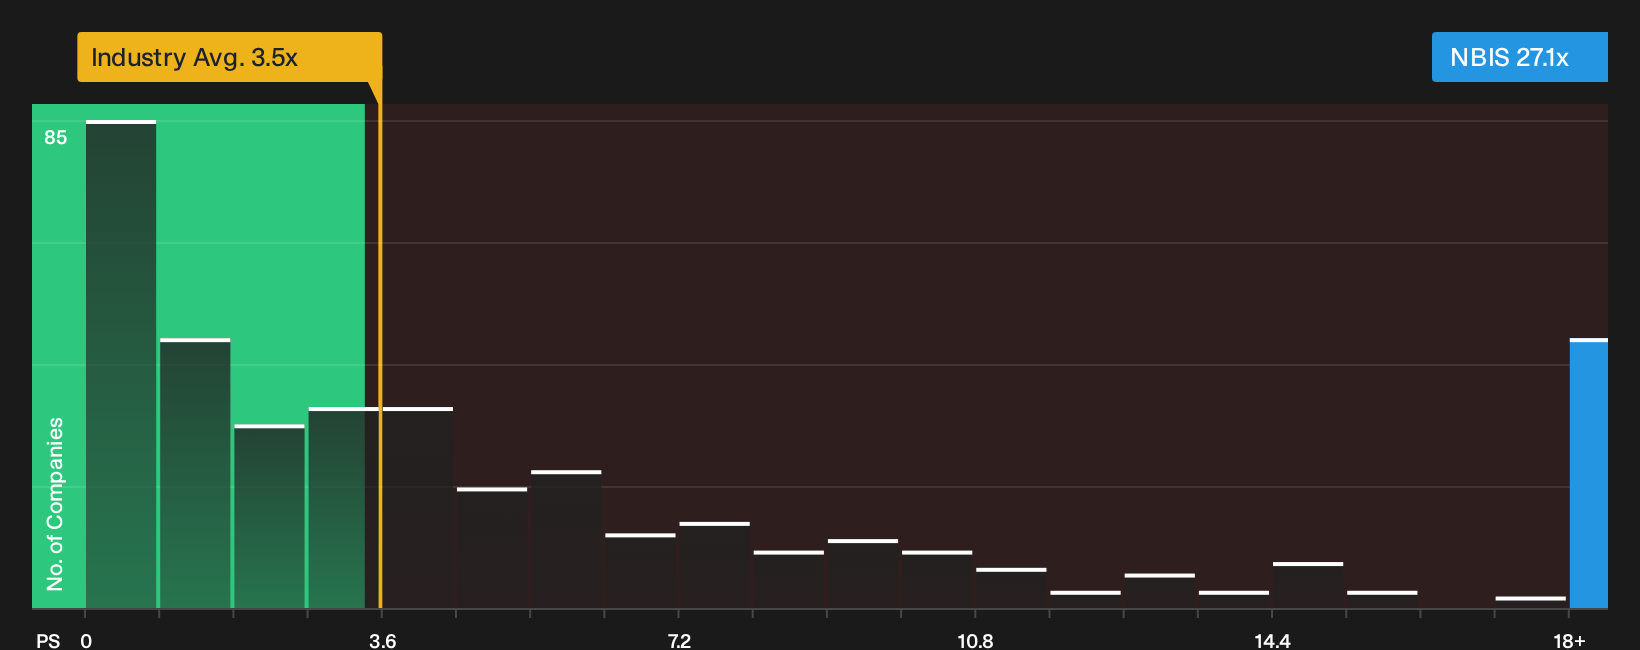
P/S is the cleanest way to frame Nebius Group right now because investors are focused on how much current revenue is being capitalised into the share price. The stock trades on a P/S ratio of 27.1x. That sits well above the wider Software industry average of 3.5x and also above a more focused peer group around 5.9x, so every dollar of Nebius Group’s sales is being valued at a much richer level than many sector peers.
Given that backdrop, the tailored fair multiple implied by the valuation model points to the shares trading below what that framework would expect for Nebius Group’s mix of growth potential, profitability profile, scale and risk. Because Microsoft has recently tightened neocloud spending and pruned partnerships, the fact that the stock still screens as undervalued on this sales yardstick suggests the market may be pricing those contract and financing concerns quite heavily already. Explore the numbers behind Nebius Group's P/S valuation.
The Nebius Group Narrative: What Would Justify Today's Price?
Nebius Group’s Simply Wall St Narratives pick up where the P/S puzzle leaves off by spelling out what kind of future for growth, margins and earnings would need to hold for the stock to be worth significantly more or less than today. Each narrative ties a fair value anchor to a particular storyline about Nebius Group's possible catalysts and pressure points, which lets you see over time which version of events is actually unfolding on the Community page.
The two Nebius Group Narratives line up on strong AI demand but disagree on whether the current price reflects funding risk or underpriced earnings power.
Bull case: 52% undervalued
The analyst consensus Narrative on Simply Wall St frames the upside if execution and profitability trends hold together.
"Nebius leverages rapid AI demand, global expansion, strategic partnerships, advanced technology, and strong funding to drive recurring revenue, margin growth, and long-term profitability…"
Discover why this Narrative puts Nebius Group at 52% undervalued.
Bear case: 23% overvalued
The bearish analyst Narrative on Simply Wall St focuses on what happens if funding strains and consolidation worries dominate.
"Bearish analysts expect Nebius Group to remain a high risk story where extreme capital needs, tighter credit and the possibility that many neocloud peers may not stay independent leave the business exposed if funding conditions worsen…"
Explore why this Narrative puts Nebius Group at 23% overvalued.
One more check on Nebius Group before you move on
Price ratios tell you what the market is paying today. The next layer is how professional forecasters currently see Nebius Group a few years down the road. Explore where analysts expect Nebius Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com