


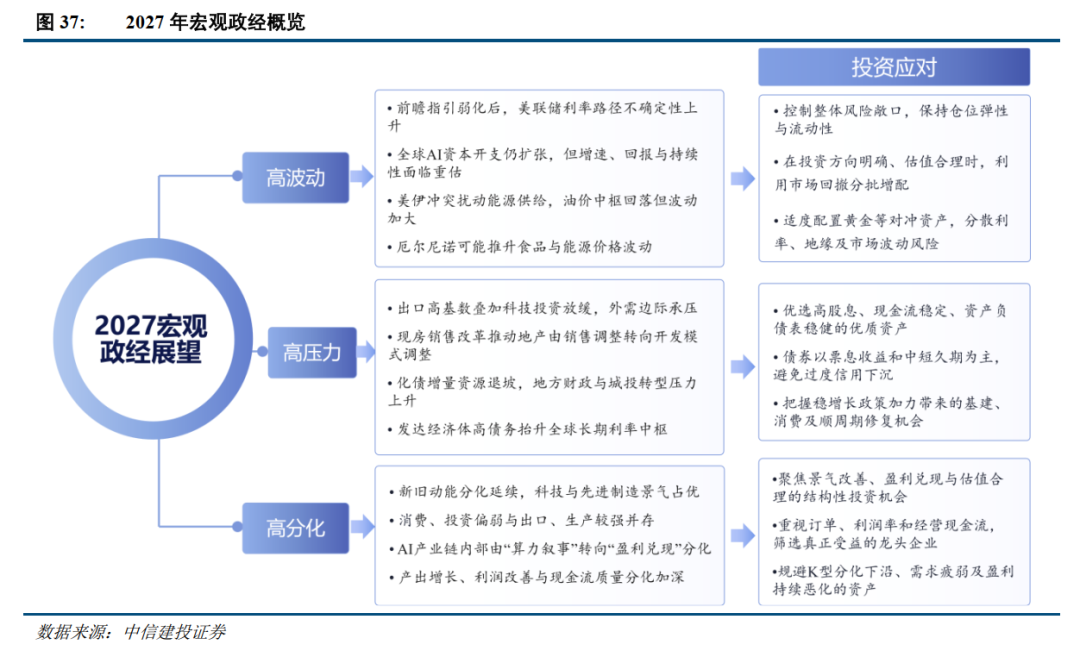
The Zhitong Finance App learned that CITIC Construction Investment Securities released a research report saying that the 2027 global macroeconomy is expected to show the characteristics of “high volatility, high pressure, and high differentiation.” High volatility comes from external disturbances such as the Federal Reserve's policy path, global AI investment returns, Middle East energy supply, and El Niño; high pressure is mainly reflected in a high export base, transformation of real estate development models, the link between local debt resources and developed economies' sovereign debt constraints; high differentiation is reflected in differences between supply and demand, new and old industries, and AI investment and profit delivery. It is expected that macroeconomic policies will continue to be active, strengthening central financial coordination, domestic demand recovery, mitigation of key risks, and industrial system reform. Asset allocation should focus on the risk hedging value of gold, A-share structural opportunities, and bond dividend income, focusing on technological innovation, major projects, service consumption, and advantageous manufacturing industries going overseas.
China's economy as a whole will remain resilient in 2026, but the structural characteristics of strong supply and weak demand are still prominent. GDP grew 4.6% year on year in the first three quarters, industrial production and exports grew rapidly, and consumption and investment recovery lagged behind; industrial product prices rebounded but downstream transmission was limited, central finance and government bonds played a steady growth role, and local financial resources and physical credit demand were still weak.
In 2026, macroeconomic policy accelerated from the “15th Five-Year Plan” strategic deployment to project implementation, and 109 major projects and the construction of the “Six Networks” became important grippers for expanding effective investment. Consumer promotion policies have been extended from short-term subsidies to increase residents' income, service supply, and fiscal and financial coordination. The “Artificial Intelligence +” campaign focuses more on industrial applications, the construction of a unified national market and anti-internal control continues to be deepened, and the reform of real estate sales and financing systems is progressing simultaneously.
Looking ahead to 2027, the global macroeconomy is likely to show the characteristics of a “new three highs”. Federal Reserve policies, global AI capital expenditure, Middle East geopolitical conflicts, and extreme climate increase interest rates and commodity price fluctuations; high export base, adjustment of real estate development models, localization debt policies, and pressure on overseas sovereign debt constrain growth; new and old industries, domestic and foreign demand, and internal profitability within the AI industry chain are further divided. Whether the economy can achieve higher quality recovery is whether domestic demand can handle the growth momentum of external demand, and whether technology investment can be converted into actual productivity and sustainable profits.
The 2027 policy is expected to remain positive and promising, with fiscal and monetary coordination, expansion of domestic demand, risk mitigation, and structural reforms to drive the transformation of growth momentum. In terms of asset allocation, gold still has strategic allocation value. A-shares focus on structural opportunities driven by profit cashout. Domestic bonds focus on coupon interest and long-term management. US stocks and US bonds need to balance technology investment returns, interest rates, and financial supply. The RMB may continue to fluctuate in both directions and is moderately strong. The main investment line focuses on scientific and technological innovation, improving the infrastructure cycle, improving consumption quality and capacity, and going overseas with advantageous manufacturing industries, focusing on examining enterprise orders, profit margins, and operating cash flow.
Looking ahead to 2027 global macroeconomic characteristics: the “new three highs” economy
The outstanding characteristics of the global macroeconomy are evolving from “high inflation, high interest rates, and high debt” to “high volatility, high pressure, and high differentiation.” After the 2008 international financial crisis, the global economy showed a “three low and one high” pattern of low growth, low inflation, low interest rates, and high debt for a long time. Since 2022, post-pandemic imbalances between supply and demand, geopolitical conflicts, and rising energy prices have driven up global inflation. Central banks in major developed economies raised interest rates rapidly, and the “three highs and one low” characteristic of high inflation, high interest rates, high debt, and low growth coexisted from 2022 to 2024. Looking ahead to 2027, global inflation may have declined somewhat from the previous peak, but debt constraints still exist, and the risks facing the macroeconomy will further shift from total quantitative restrictions on inflation and interest rates to a combination of multiple shocks and structural adjustments. On the one hand, monetary policy expectations, geographical conflicts, and changes in technology investment cycles may exacerbate global economic and financial fluctuations; on the other hand, adjustments in global demand momentum and debt constraints are intertwined with China's stock risk mitigation and industrial transformation pressure, and the profit performance of different industries and enterprises may further diverge. Therefore, this paper summarizes the outstanding characteristics of the global macroeconomic environment in 2027 as the “new three highs” of “high volatility, high pressure, and high differentiation”, and focuses on analyzing their impact on China's economic operation and asset allocation.
(1) High fluctuation
Looking ahead to 2027, the global economy is expected to maintain some growth resilience, but uncertainty about macroeconomic performance is likely to rise further. Changes in the Federal Reserve's policy communication methods, changes in the AI capital expenditure cycle, the Middle East geopolitical conflict, and extreme climate events will all affect global interest rates, asset valuations, and commodity prices. Unlike simultaneous fluctuations driven by traditional demand cycles, this round of uncertainty is more reflected in the intertwining of policy expectations, technology investment, and supply shocks. The transmission of external risks to China's financial market, export demand, and price levels is worth paying attention to.
1. After the forward-looking guidance weakened, the uncertainty of the Federal Reserve's monetary policy increased
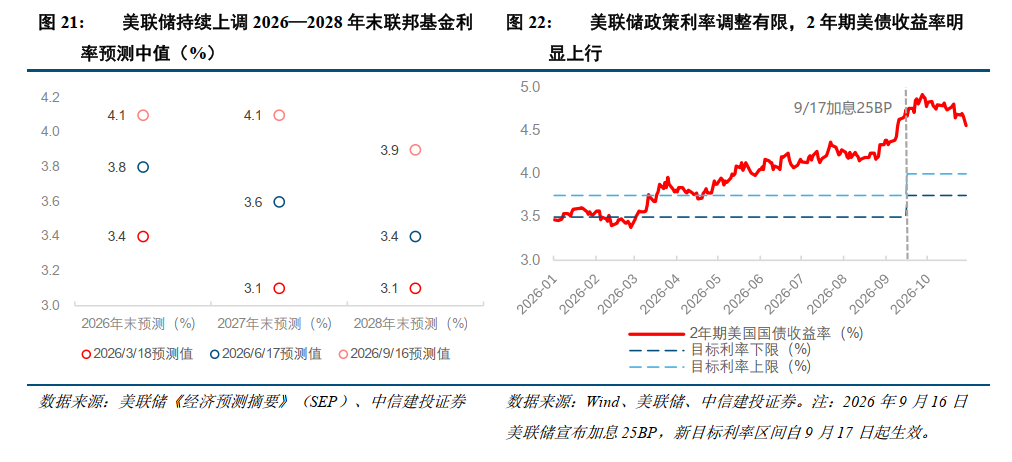
In 2026, the Federal Reserve gradually weakened its prior commitment to future interest rate paths, compounded economic growth resilience and inflationary pressure, and the 2027 monetary policy faced a greater risk of adjustment of expectations. In August, Federal Reserve Chairman Walsh proposed forward-looking guidelines to limit normalization, emphasizing avoiding excessive commitment to future policy paths and retaining the flexibility to adjust policies according to the economic situation. The main purpose of this change is to reduce the market's reliance on pre-set interest rate paths. At the same time, the US economy is showing strong performance, rising energy prices are increasing inflationary pressure, and the Federal Reserve's policy stance is once again becoming more cautious. The Federal Reserve raised interest rates by 25 basis points in September, raising the federal funds rate target range to 3.75% — 4.00%; the economic forecast for the same period will further raise the median policy interest rate to 4.1% at the end of 2027 from 3.1% in March and 3.6% in June. Interest rates remained unchanged at the October meeting, but the two members preferred to continue to raise interest rates, reflecting that there are still some differences in policy orientation.
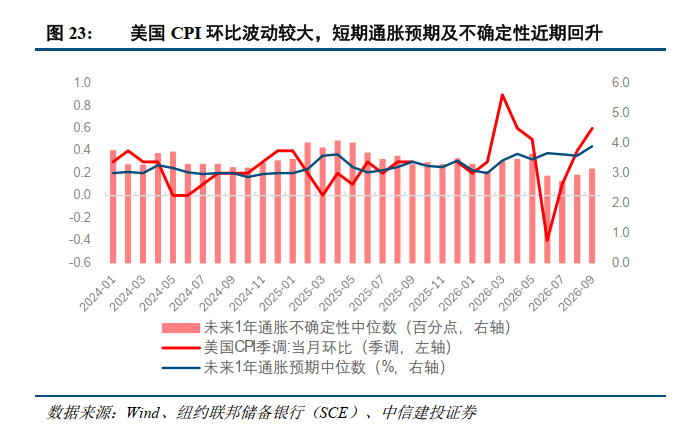
The uncertainty about the 2027 interest rate path is mainly due to dynamic changes between growth resilience and falling inflation, rather than weakening forward guidance itself. The US CPI fluctuated greatly from month to month in 2026. The New York Federal Reserve's September survey showed that one-year inflation expectations rose to 3.9%, and inflation uncertainty has recently picked up. Furthermore, the Federal Reserve's September forecast shows that in 2027, the real GDP growth rate of the US will be 2.4%, the unemployment rate will be 4.1%, and the core PCE inflation rate will still reach 2.5%, indicating that economic growth and employment resilience may keep monetary policy strong when inflation has not fully declined. Looking ahead to 2027, the restoration of energy supply is expected to drive continued improvement in inflation, but repeated geopolitical conflicts and core inflation stickiness may increase phased fluctuations, making monetary policy adjustments face greater uncertainty. Under the benchmark scenario, the Federal Reserve is expected to raise interest rates by 25 basis points to 4.00% — 4.25% in December 2026, leaving interest rates unchanged throughout 2027. Under the hawkish scenario, if inflation falls short of expectations, interest rates may be raised by another 25 basis points in the first half of 2027, and the target interest rate range for the end of the year will rise to 4.25% to 4.50%.
Weakening forward-looking guidance may amplify the market's sensitivity to economic data and policy signals, causing interest rate expectations to be adjusted before actual policy changes. In the absence of promises of a stable path, the market needs to judge policy orientation more based on employment, inflation, and economic activity data. Expected changes may be transmitted to other assets through short-term US bond yields, US dollar exchange rates, and global risk appetite. Even if the Federal Reserve keeps the policy interest rate unchanged at some meetings, the financial market may still fluctuate greatly due to future adjustments in interest rate expectations. For China, the relevant changes will further affect the RMB exchange rate, cross-border capital flows, and risk asset valuation.
2. Fluctuations in AI expectations of repricing
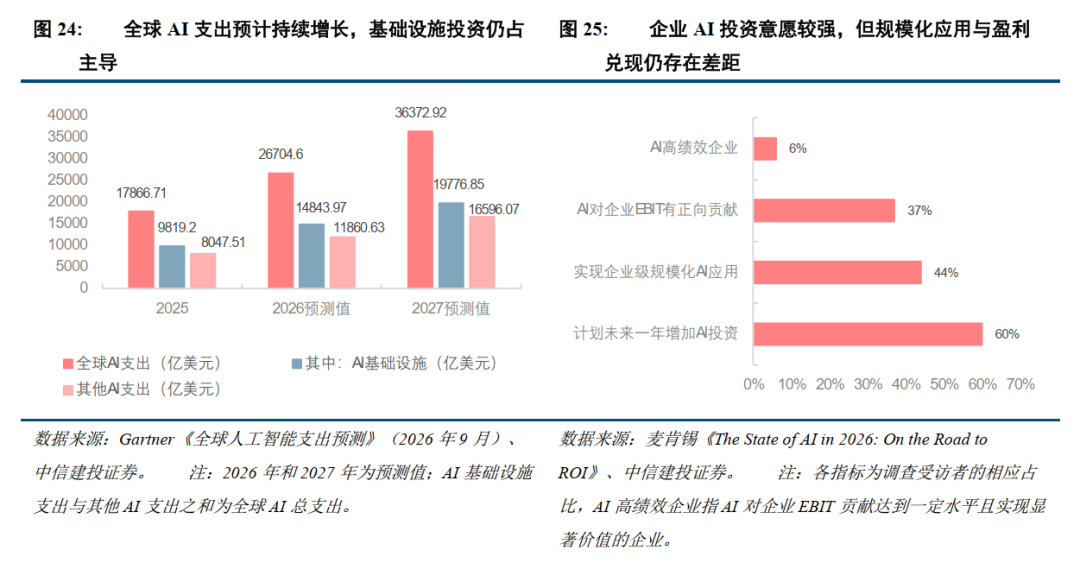
Global AI investment is still in an expansion cycle, but as the scale of capital expenditure grows rapidly, the market focus in 2027 will shift further from the scale of investment to commercial income and return on capital. Since 2026, global technology companies have continued to increase investment in computing power infrastructure, driving rapid growth in demand for semiconductors, servers, data centers and supporting power equipment. According to WTO data, in terms of trade volume, AI-related products will contribute 47% of the increase in global goods trade in the first half of 2026. Gartner predicts that in 2027, global AI-related spending will reach $3.64 trillion, an increase of 36.2% over the previous year, of which AI infrastructure spending is close to $2 trillion. As artificial intelligence expands into fields such as enterprise software, smart devices, and industrial applications, the expansion of application scenarios and improvements in technological efficiency are expected to continue to release demand. AI is still an important driving force for investment and economic growth in the global technology industry.
The differentiation between AI's long-term growth potential and short-term commercial returns may become an important source of repricing expectations for the global technology industry and capital market in 2027. On the one hand, the scope of AI applications continues to expand, and some fields have shown great potential for commercialization; on the other hand, the revenue growth rate of some AI companies has slowed down, and there is still a time gap between investing in high computing power and realizing commercial benefits. According to the McKinsey 2026 survey, 44% of respondents said that their companies have implemented large-scale enterprise-level AI applications, but only 37% reported that AI has made a positive contribution to corporate operating profits, and AI high-performing companies account for only 6%, reflecting that application expansion has not generally been transformed into significant financial benefits. As upfront investment gradually forms operating costs and depreciation burdens, the market's judgment on AI demand growth, profit fulfillment, and reasonable valuation may be further divided. If commercial returns fall short of expectations, capital expenditure adjustments may be transmitted along the semiconductor, server, and data center industry chains, causing related asset valuations to fluctuate. For China, AI is not only an important growth engine for technology manufacturing exports and industrial upgrading, but also a source of anticipated fluctuations in external demand and capital markets.
3. The US-Iran conflict and oil prices: focus on the supply recovery path rather than simply judging that oil prices continue to rise
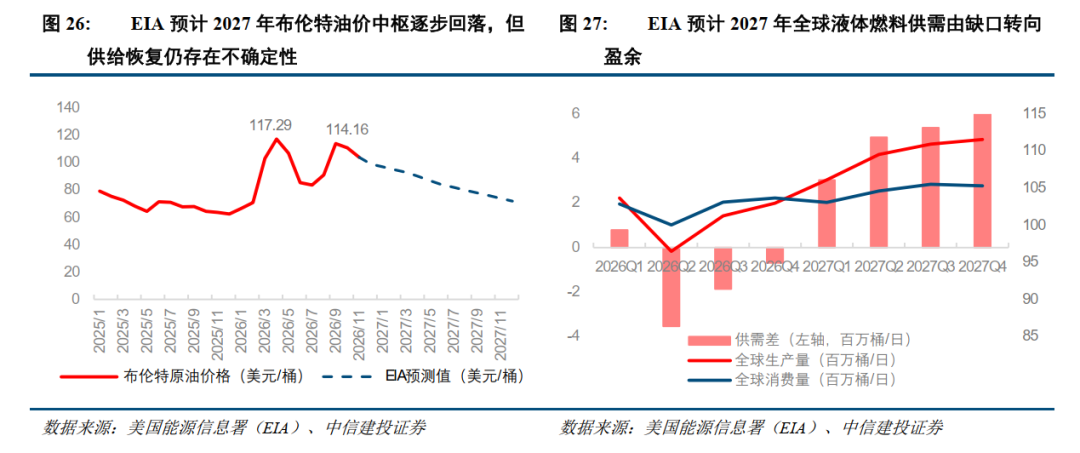
The geographical conflict in the Middle East continues to disrupt global energy supply, and international oil prices in 2027 may be characterized by a decline in the price center coexisting with high phased fluctuations. Since 2026, the US-Iran conflict and disruptions in regional energy facilities and shipping lanes have driven up international oil prices significantly. According to EIA data, the average spot price of Brent crude oil rose to 114 US dollars/barrel in September, and once reached 131 US dollars/barrel on September 15. With the gradual resumption of oil production and transportation in the Middle East, the EIA predicts that the average price of Brent crude oil will fall back from 96 US dollars/barrel in 2026 to 84 US dollars/barrel in 2027, but the forecast for 2027 is 10 US dollars/barrel higher than in September, reflecting continued supply constraints and transportation risks that still support oil price expectations.
The shift in the supply and demand pattern from a gap to a surplus is the main basis for the central decline in oil prices in 2027, but this judgment is highly dependent on the recovery progress of production and transportation in the Middle East. The EIA benchmark scenario predicts that most of the affected production in the Middle East is expected to return to pre-conflict levels at the end of the second quarter of 2027. Global liquid fuel supply and demand will shift from a continuous gap in the second half of 2026 to a supply surplus in 2027. The expected surplus will expand from about 3 million b/d in the first quarter to about 6.2 million b/d in the fourth quarter. As supply recovers faster than demand, global oil inventories are expected to gradually recover, ease tight spot supply and push oil prices back down. This means that the main driving force behind the decline in oil prices in 2027 is a recovery in supply rather than an overall weakening of global energy demand.
The main uncertainty about oil prices is that supply recovery and transportation safety may be repeated, and price fluctuations may not necessarily fall smoothly along the benchmark forecast path. If production recovery in major oil-producing countries and construction of alternative transportation routes meet expectations, the oil price center is expected to gradually decline; if the conflict escalates or key channels such as the Strait of Hormuz are blocked again, the supply gap and transportation risk premiums may widen again, causing phased price jumps. As far as China is concerned, falling oil prices are conducive to reducing energy imports and downstream production costs, while repeated prices may affect PPI and industrial chain profit distribution through raw materials and transportation costs. The transmission to terminal consumer prices still depends on domestic demand and price mechanisms. Overall, the risk of energy prices in 2027 is more reflected in repeated price and cost shocks under uncertainty about supply recovery, rather than continued unilateral increases.
4. The impact of the El Niño phenomenon on the price level
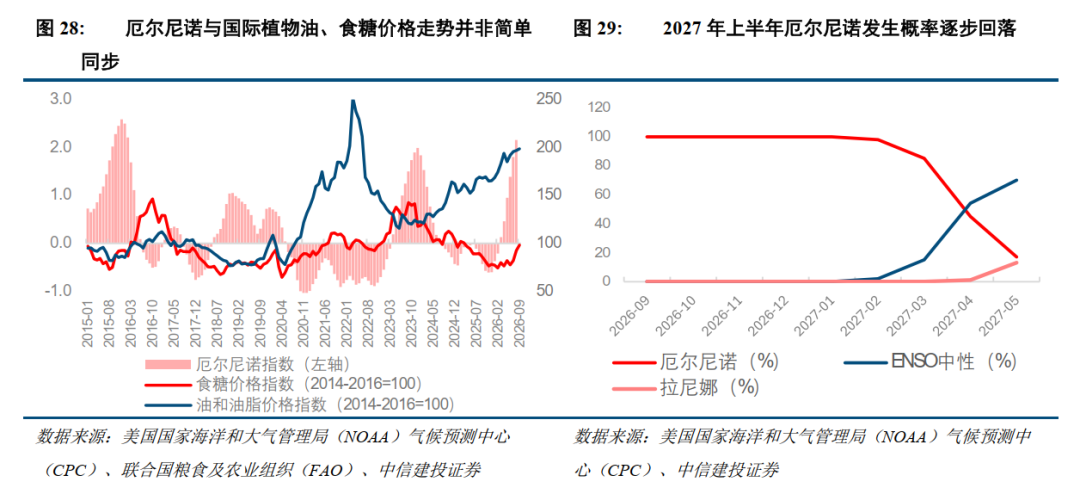
The strong El Niño event formed in 2026 may have a delayed impact on global agricultural supply in 2027, and some food prices face the risk of structural increases and fluctuations. Monitoring by the National Climate Center shows that a super El Niño event officially formed in September 2026, and the three-month average value of the sea temperature index in the Niño 3.4 zone from July to September reached 2.54 degrees Celsius. In October, NOAA predicted that the probability that the strong to extremely strong El Niño state will continue to exceed 83% from January to March 2027. Since then, the probability of an ENSO neutral state will increase in spring as the sea temperature gradually weakens. However, the weakening of climate conditions does not mean an immediate recovery in agricultural supply. Abnormal weather such as droughts and floods in the early stages may still affect the supply of agricultural products in 2027 through crop growth cycle and yield adjustments.
The impact of El Niño on international agricultural product prices has obvious regional differences and time lags, and climate-sensitive commodities such as vegetable oil and sugar are worth focusing on. El Niño may reduce precipitation in parts of Southeast Asia, affect palm oil production in Indonesia and Malaysia, and oil palm has a long growth cycle, and the impact on production may gradually become apparent a few months after the climate event; major sugar producing countries such as India and Thailand may be affected by abnormal monsoon precipitation, thereby changing the pattern of sugar supply and demand. Historical data shows that the El Niño index is not always in sync with international vegetable oil and sugar prices, and price changes are also affected by factors such as energy costs, biofuel demand, stocks, and trade policies. The World Bank predicted in October that global food commodity prices will rise further by about 7% in 2027. The relevant forecast takes into account multiple factors such as abnormal climate, disturbances in food transportation, and energy and fertilizer costs. As a result, climate shocks are more likely to cause some commodity price fluctuations through supply contraction in specific production areas, rather than driving the prices of all agricultural products to rise simultaneously.
As far as our country is concerned, the price impact of El Niño is expected to be reflected more in structural fluctuations in food prices rather than overall inflationary pressure. Changes in international commodity prices such as vegetable oil and sugar may be transmitted domestically through import costs, food processing and related consumer goods channels. Extreme weather may also affect the production, transportation, and water and electricity supply of some domestic agricultural products. However, the transmission of international prices to domestic terminal prices is still affected by factors such as exchange rates, inventory reserves, import regulation capacity, and market competition, and China's major food varieties have a certain domestic supply guarantee basis. Looking ahead to 2027, even if El Niño gradually weakens, the supply of some agricultural products may still be affected by delays in earlier climatic anomalies. It is expected that overall prices in China are still expected to remain relatively moderate. We need to focus on being wary of repeated food and other bureau prices and their impact on residents' living costs and the profits of related enterprises.
(2) High pressure
In 2027, China's economic growth will still face the double pressure of adjustment of external demand momentum and internal structural transformation. On the one hand, rapid export growth in 2026 forms a high base, and changes in global technology investment and international trade policies may affect external demand's support for domestic production; on the other hand, the transformation of the real estate development model, local financial constraints, and stock debt adjustments will still take time. At the same time, pressure on developed economies' sovereign debt may affect the domestic financial environment through global interest rates and capital flows. Under the combination of multiple factors, the pressure on economic growth may be reflected more in changes in demand momentum and balance sheet adjustments rather than a single external shock.
1. The impact of the decline in China's export growth rate
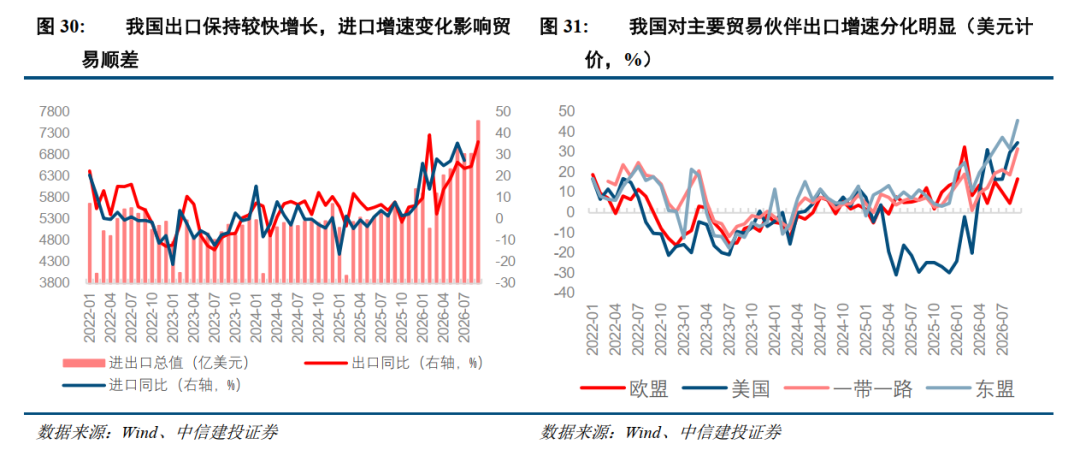
In 2027, China's export growth rate may gradually return to normal from rapid growth in 2026. The main pressure comes from a high base and adjustments in demand growth in some booming industries, rather than an overall weakening in global external demand. In the first three quarters of 2026, in US dollars, China's exports of goods increased by 21.3% year on year. Among them, exports of mechanical and electrical products increased by 29.0%, accounting for 64.4% of total exports, driving the overall export growth of 17.5 percentage points. The expansion of global investment in technology and the competitive advantage of China's manufacturing industry have jointly supported export growth, but it has also concentrated more export growth in some advantageous industries. Looking ahead to 2027, as the concentrated release of early orders forms a high base, the pace of investment expansion in fields such as artificial intelligence infrastructure may gradually slow down. Combined with international trade policy adjustments and increased competition in overseas markets, the export growth rate of some technology manufacturing industries may decline somewhat. However, the supporting capacity of China's manufacturing industry chain and diversified market layout will still provide support, and export growth is more likely to show structural differentiation among industries rather than general contraction.
The slowdown in export growth has not necessarily led to a simultaneous decline in the contribution of net exports to economic growth, but the negative effects transmitted through the industrial chain are still worth paying attention to. Exports and imports together determine how net exports drive economic growth. Even if export growth declines, if import growth slows down further, net exports may maintain a positive contribution. However, if the slowdown in imports is mainly due to insufficient domestic consumption and investment, a widening trade surplus does not mean an increase in economic growth momentum. At the same time, the slowdown in export order growth will directly affect enterprise production arrangements, procurement of raw materials and components, and affect corporate revenue and profits through the upstream and downstream industrial chains. If the growth of export orders slows down, the related impact may be transmitted along the industrial chain, weakening the production expansion, revenue growth, and investment needs of upstream and downstream enterprises. Therefore, even if the contribution of net exports to economic growth remains stable, some export manufacturing industries and their upstream and downstream enterprises may still face pressure from weakening demand growth, and changes in trade surpluses alone cannot judge the actual support of external demand for the domestic economy.
The key impact of the adjustment in external demand in 2027 is whether domestic consumption and investment can effectively handle the momentum of export growth. If the growth rate of export orders declines and domestic demand does not improve at the same time, some manufacturing industries may face pressure from declining capacity utilization, intensifying price competition, and narrowing profit margins; if consumer consumption and private investment gradually resume, it is expected that the impact of the deceleration in external demand on production and business operations will be mitigated. At the same time, enterprises with technological advantages, diversified overseas market layouts, and strong industrial chain competitiveness are expected to still have some growth resilience. Overall, the change in export growth in 2027 itself is not the only risk that needs to be paid attention to. More importantly, whether external demand can continue to provide marginal support for domestic production and corporate profits, and whether domestic demand can form an effective continuation.
2. Under the existing housing sales system, real estate is being dragged down to deep adjustment
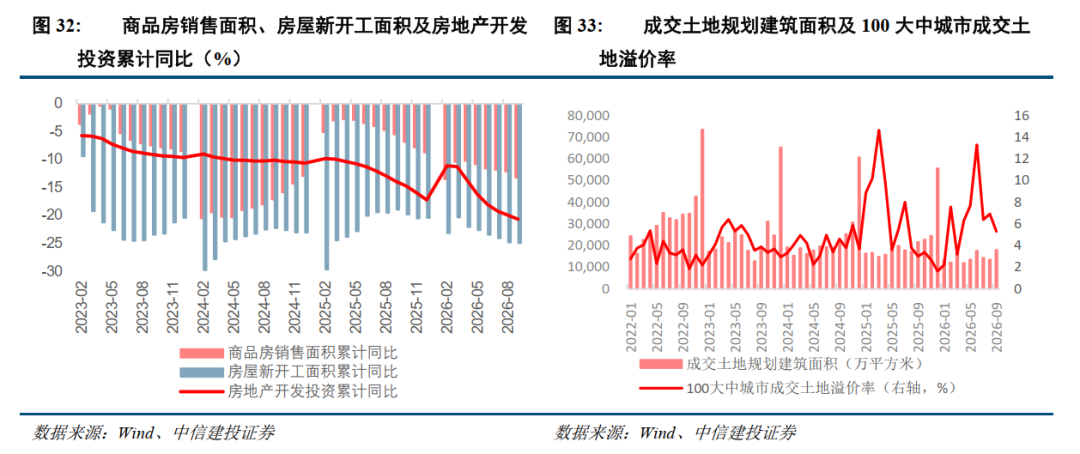
In 2027, the real estate market may face the double constraints of weak sales demand and a shift in development models. Existing housing sales reforms will further change the capital turnover and new investment decisions of housing enterprises. Compared with the traditional pre-sale model, existing housing sales require development companies to bear construction costs for a longer period of time before obtaining the main sales payment, increasing the use of project capital, and placing higher demands on own capital and development financing. At the same time, the land market continued to adjust, and the country's state-owned land use rights concession revenue fell from a peak of 8.71 trillion yuan in 2021 to 4.15 trillion yuan in 2025, a cumulative decrease of 52.3%; a further year-on-year decline of 27.9% in the first three quarters of 2026. As new projects gradually apply the existing housing sales system, housing enterprises may pay more attention to financial security and sales elimination expectations, reduce business methods that rely on rapid turnover to expand the scale of development, and land market restoration will also face certain restrictions.
Whether financing such as development loans can effectively link sales repayments is an important variable affecting real estate investment in 2027. In the first three quarters of 2026, deposits and advance payments and personal mortgage loans together accounted for 45.2% of the funds available to housing enterprises. Domestic loans accounted for only 13.4%, and a year-on-year decrease of 33.1%, indicating that real estate development still relies heavily on sales-related funds, and bank financing has yet to form clear alternative support. As sales repayments for some new projects move backwards, if funding sources such as development loans and equity financing cannot be replenished in a timely manner, housing enterprises may give priority to guaranteeing the delivery of projects under construction and inventory removal, further slowing down land acquisition and the commencement of new construction. The project sponsor banking system and development loan arrangements that match the construction cycle can help relieve financial pressure, but the actual results still depend on the bank's risk appetite, project sales prospects, and the enterprise's own credit status.
Real estate investment is likely to continue to be weaker than sales-side recovery in 2027, and the slowdown in land acquisition by housing enterprises will further limit local revenue and investment capacity. Currently, the decline in new construction area has clearly exceeded the sales area of newly built commercial housing, reflecting that development companies are still cautious about new investment. Even if subsequent housing transactions improve, enterprises may prioritize absorption of existing projects, repair cash flow, and then gradually resume new investment. The recovery in sales will spread to land purchases and new construction starts, and there is a time lag. Under the existing housing sales model, the extension of the capital turnover cycle of housing enterprises may further curb demand for land acquisition, influence local government fund budgets through the scale of land transactions and sales revenue, and restrict land preparation, infrastructure, and related public investment expenses. Looking ahead to 2027, revenue from land concessions is expected to remain under pressure, and regions that are partly dependent on land finance face greater balance constraints. Overall, the key to whether real estate's drag on economic growth can be reduced in 2027 is not only stabilizing housing sales, but also whether improvements in housing companies' capital cycle can drive the restoration of new construction, the land market, and local financial investment capacity.
3. Local government debt amounts have declined, and urban investment platforms are under pressure to withdraw
In 2027, local government debt settlement has entered the policy interface stage. The decline in established large-scale replacement quotas and local revenue restrictions may jointly affect local investment capacity. According to the 2024 debt package, an additional 2 trillion yuan of local government debt limits will be added every year from 2024 to 2026 to replace hidden stock debt, and an additional 800 billion yuan of special bonds will be added every year from 2024 to 2028 to be used for debt conversion. As of September 2026, the cumulative issuance progress of the 6 trillion yuan replacement limit has reached 98.3%. With the end of the centralized replacement arrangement, the established debt support for 2027 will continue, but without additional policies, replacement resources will be significantly reduced compared to the previous period. At the same time, land concession revenue continues to shrink, and local governments are still facing greater financial coordination pressure between repayment of existing debt, livelihood security, and new investment.
Early debt swaps have effectively relieved debt repayment pressure, but the market-based transformation of urban investment platforms and the restoration of local investment capacity still face constraints. Debt swaps improve debt repayment cash flow by reducing financing costs and extending debt periods, but they have not directly increased local revenue or project operating income. As the government financing function of financing platforms is gradually divested, urban investment enterprises will rely more on operating income and their own cash flow to repay debts. The differentiation in regional financial strength, platform asset quality, and refinancing capacity may become further evident. At the same time, funds freed up by local finance may be prioritized for debt repayment and rigid expenditure, and may not directly result in new investment. Overall, there is still a basis for policy mitigation of local debt risk in 2027, but it will still take time for debt pressure to be reduced and transmitted to the restoration of investment capacity. Central financial support, improvement of local financial resources, and progress in the transformation of urban investment platforms will be important influencing factors.
4. Pressure on developed economies' sovereign debt
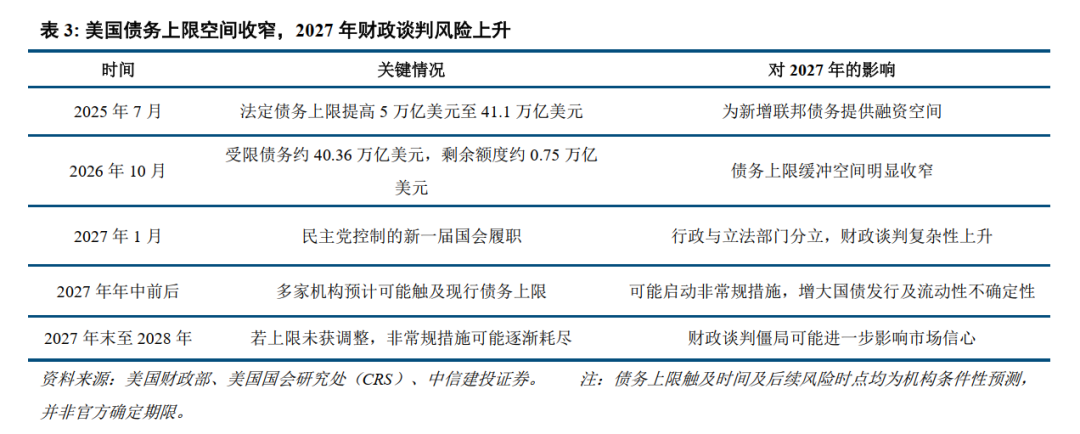
High debt and high interest rates in advanced economies reinforce each other, and fiscal financing pressure in 2027 may further transform into long-term interest rates and asset pricing constraints. The US federal budget deficit in fiscal year 2026 was about 1.99 trillion US dollars, and net interest expenses reached 1.05 trillion US dollars, accounting for 19.5% of fiscal revenue. The debt interest burden continued to increase. Continued fiscal deficits mean that the government still needs to expand debt financing, and after early low-interest debt matures one after another, higher refinancing costs may also drive up interest expenses and further reduce fiscal policy space. At the same time, US debt ceiling restrictions have reappeared. In July 2025, the US raised the debt ceiling to 41.1 trillion US dollars. By the end of October 2026, the remaining amount was less than 800 billion US dollars. Institutions expect to hit the upper limit again in 2027. Compared with the risk of short-term sovereign default, what is more noteworthy is the combination of high debt size, continuous debt issuance requirements, and fiscal policy uncertainty, which may increase long-term financing costs.
Changes in the US political landscape after the midterm elections may further increase uncertainty about 2027 debt ceiling negotiations and long-term interest rate trends. After the 2026 midterm elections, the Democratic Party gains control of both houses of Congress, and the fiscal policy differences between the Trump administration and Congress are likely to grow. If the debt ceiling is hit again in 2027, the game between the two parties over debt amounts, fiscal expenditure, and budget arrangements may cause the upper limit adjustment to face a longer negotiation process, increasing the risk of fluctuations in the US bond market. Even if the Federal Reserve gradually lowers policy interest rates in the future, the continued supply of treasury bonds, high interest burdens, and investors' concerns about fiscal sustainability may limit the downward space for long-term yields. As far as China is concerned, related changes may affect the domestic financial market through US bond yields, US dollar exchange rates, and cross-border capital flows. Overall, the sovereign debt risk of developed economies in 2027 is not only reflected in long-term fiscal financing constraints, but may also become an important source of fluctuations in global financial markets due to political games.
(3) High differentiation
The structural differentiation of China's economy in 2027 may further extend from differences in output growth rates to corporate profits, operating cash flow, and return on investment. At the industrial level, technology demand, price changes, and market competition will continue to divide the profit performance of old and new industries and within the same industry; at the macro level, production and exports will maintain some resilience, but domestic demand recovery and investment restructuring may still limit the transformation of growth momentum; and the artificial intelligence industry is facing problems where the acceleration of technology application and the delivery of commercial benefits are not synchronized. Compared to the growth rate itself, whether demand can generate continuous revenue and whether enterprises can retain profits will be an important basis for judging the quality of economic growth in 2027.
1. Differentiation of old and new kinetic energy between different industries
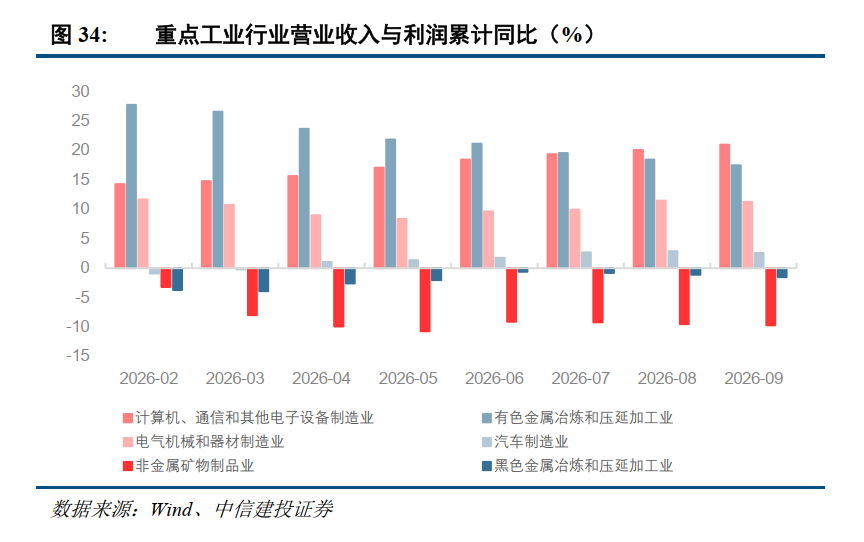
Industrial growth in 2027 may continue the pattern where the expansion of emerging industries coexists with adjustments in some traditional industries, but the differentiation of industry profits is not simply a “new strength, old weakness,” but will depend more on market demand, product pricing, and competitive patterns. In the first three quarters of 2026, the revenue of the computer, communications and other electronic equipment manufacturing industry increased by 21.0%, profit increased by 103.8%, revenue from the non-ferrous metal smelting and rolling processing industry increased by 17.5%, and profit increased by 79.7%. In contrast, the revenue of the electrical machinery and equipment manufacturing industry increased by 11.3%, but profit decreased by 5.9%, and the automobile manufacturing industry's revenue increased by 2.6% and profit decreased by 22.8%. Revenue and profit changes in different industries are clearly differentiated, reflecting technological demand, product prices, and industry competition all influence corporate profits. Looking ahead to 2027, emerging fields such as artificial intelligence and high-end equipment are still expected to benefit from technological upgrades and application expansion, but the release of new production capacity in some areas may increase price competition; in traditional industries, enterprises with cost advantages, improved supply and demand, or strong pricing capabilities may still recover profits, while real estate chain-related industries face continuous adjustment pressure.
Industrial differentiation will further extend from differences in growth rate to differences in profit quality and operating cash flow, and whether companies can turn revenue growth into sustainable income will be even more important. At the end of September 2026, accounts receivable and finished product inventories of large-scale industrial enterprises increased by 10.0% and 11.6%, respectively, higher than the 6.6% growth rate of operating income during the same period. The payback period and inventory turnover days were also extended, reflecting that some enterprises are still facing pressure on capital turnover and inventory digestion. In 2027, as early industrial investment gradually forms new supply, even if some industries maintain rapid output and revenue growth, they may be constrained by price competition, rising costs, and extended repayment cycles. Compared to simple production and revenue expansion, order continuity, profit margin, asset turnover efficiency, and operating cash flow will more directly affect the company's ability to add new investment and profit resilience. Overall, the core of industry differentiation in 2027 may not only be rapid or slow growth, but also whether enterprises can maintain stable profits and cash flow amid changes in demand and competitive adjustments.
2. The differentiation between weak consumption and investment and strong exports and production
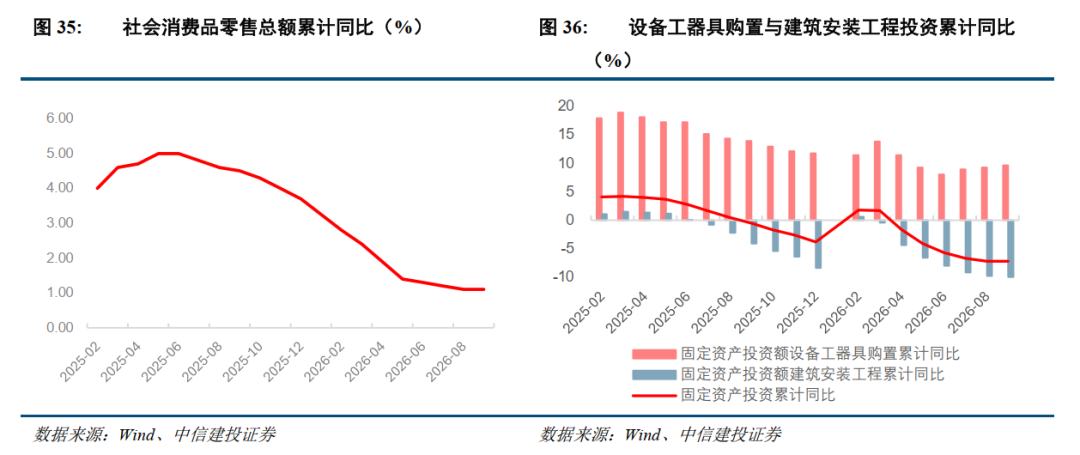
In 2027, China's economy is likely to continue the characteristics of strong production-side resilience and a relatively slow recovery in domestic demand, but not all industries are experiencing simultaneous differentiation, and structural differences within investment are also worth paying attention to. Industrial production and exports maintained rapid growth in 2026, while the recovery of consumption and fixed asset investment was relatively insufficient. In the investment structure, investment in the purchase of equipment and tools increased by 9.7% in the first three quarters, and investment in construction and installation projects fell by 10.0%, reflecting that investment needs such as technological transformation and equipment renewal are still supported, but traditional construction investment continues to be under pressure. This means that production expansion and capital expenditure in some emerging sectors have not been simultaneously transformed into broader consumer consumption, private investment, and terminal demand improvements, and economic growth is still constrained by demand restructuring.
The key to whether the differentiation between supply and demand can be improved in 2027 is not only whether the gap between production and demand growth narrows, but also whether the economy converges through a recovery in domestic demand or a slowdown in production. If employment income, consumer consumption, and private investment gradually improve, domestic demand is expected to take on part of the growth momentum of exports and production, drive enterprise inventory digestion, profit recovery, and investment intentions to recover, forming a virtuous cycle of demand-driven production. If external demand growth slows down and domestic terminal demand does not continue effectively, some industries may achieve passive adjustments through price reduction competition, reduced production and reduced investment, further affecting corporate profits and residents' income. Overall, the key to improving the economic structure in 2027 is whether domestic demand can form a driving force for continuous growth, rather than simply relying on production-side adjustments to narrow the gap between supply and demand.
3. The differentiation of the AI industry's internal narrative and implementation
In 2027, the artificial intelligence industry chain may further show the characteristics of revenue differentiation in hardware orders, model services, and terminal applications. Accelerated application of technology does not mean that profits in all links will improve at the same time. Looking at the industrial chain, infrastructure links such as chips, servers, optical communication, and data center supporting equipment mainly benefit from the capital expenses of technology companies, and order performance is closely related to the new investment cycle; model and computing power service companies need to continue to bear computing power, R&D, and operating costs, and their profitability depends on customer needs, service pricing, and cost changes brought about by technology iteration; although the capital investment of downstream application companies is relatively light, the business model has yet to be verified. As artificial intelligence moves from technology promotion to actual business scenarios, the pace of revenue growth and profit redemption in different sectors may further diverge.
The industrial value creation of artificial intelligence is not necessarily synchronized with the acquisition of commercial value by enterprises; the ability to implement applications will become an important factor in determining industrial differentiation. Looking at the industrial chain, infrastructure links such as chips, servers, liquid cooling, and power supply and distribution mainly benefit from capital expenditure expansion, and order growth has strong investment cycle characteristics; models and computing power services face constraints such as technology iteration, computing power prices, equipment depreciation, and changes in customer demand; whether downstream application companies can achieve continuous profits depends on product payment, scenario adaptation, and customer retention. For terminal industries such as manufacturing, the economic value of AI applications is more reflected in improved production efficiency and reduced operating costs, but related benefits may not be fully converted into commercial profits for AI service providers. As the “artificial intelligence+manufacturing” campaign continues to advance in 2027, industrial intelligence, industry models, and enterprise application scenarios are expected to be implemented at an accelerated pace. The pricing logic of the AI industry may further shift from technical narratives and capital expenditure expectations to order fulfillment, profitability and actual productivity improvements, and the market performance of different links in the industrial chain is expected to become more fragmented.
(4) Policy expectations
The 2027 macroeconomic policy is expected to continue its positive overall approach. While stabilizing the intensity of fiscal expenditure, more emphasis will be placed on the coordinated application of policy financial instruments, fiscal interest rates, and structural support policies. Facing the slowdown in external demand growth, real estate adjustments, and local financial constraints, the policy focus is expected to shift from simply expanding capital investment to improving the efficiency of leveraging financial resources, forming a steady growth synergy through central financial strengthening, policy financial support, and demand-side subsidies, and moderately strengthening countercyclical adjustment of risks in the capital market and key areas.
The fiscal policy is expected to maintain an official deficit rate of around 4%, the scale of broad fiscal financing will expand marginally, and the application of new policy financial instruments is expected to be normalized. Under the benchmark scenario, it is estimated that in 2027 the official fiscal deficit will be about 6.1 trillion yuan to 6.3 trillion yuan, with additional local special debt of about 4.6 trillion to 4.8 trillion yuan, ultra-long-term special treasury bonds of about 1.2 trillion to 1.5 trillion yuan, and a total of about 12.1 trillion yuan to 12.6 trillion yuan in additional government debt financing in a broad sense, an increase from the original schedule for 2026. The launch of 800 billion yuan of new policy financial instruments has been completed in 2026. It is expected that 800 billion to 1 trillion yuan will continue to be allocated in 2027, focusing on supplementing capital for the “Six Networks”, urban renewal, consumer infrastructure, and scientific and technological innovation projects to leverage bank supporting financing. Financial support methods will give more prominence to the central government's coordination and efficiency in the use of funds, and the link between policy financial instruments and reserves for major projects is expected to be further institutionalized.
Monetary policy is expected to remain moderately loose, with lower and policy interest rate adjustments paying more attention to operational flexibility and internal and external balance. Since November 2026, overnight reverse repurchase rates have become an important anchor for short-term policy interest rates, helping to enhance the accuracy of short-term market interest rate regulation. Looking ahead to 2027, considering government bond issuance, credit investment, and bank debt cost constraints, it is expected that there will be room for a 25-50 basis point downgrade to provide medium- to long-term liquidity support. If domestic demand and price recovery fall short of expectations, policy interest rates are still likely to be lowered moderately, but it is necessary to balance bank net interest spreads and exchange rate stability. When the RMB is under pressure to appreciate rapidly, it is expected that the central bank will strengthen the management of exchange rate expectations, use foreign exchange macroprudential tools in due course to prevent unilateral expectations from strengthening themselves, and maintain the basic stability of the RMB exchange rate at a reasonable equilibrium level.
The real estate policy is expected to be further skewed towards the demand side, and the impact of existing housing sales reforms on the capital turnover of housing enterprises and local finance will be mitigated through fiscal and financial coordination. The first housing loan financial interest rate policy introduced in 2026 imposes restrictions on total housing prices, area, and loan types. If real estate sales continue to be weak, it is expected that the policy period will be extended in 2027, and the total price, area, or scope of applicable housing will be moderately relaxed to increase the degree of coverage of the policy's demand for improved housing purchases. The supply side is expected to continue improving the project sponsor banking system and development loan arrangements to ease the pressure on the advance construction capital under the existing housing sales model. In terms of local finance, the continued contraction of land concession revenue may prompt the central government to further increase transfer support, moderately revitalize local government debt balance limits, and support land reserves, stock commercial housing acquisitions, and urban renewal through special bonds to ease the restrictions on local investment capacity due to declining land finance.
The consumer promotion policy is expected to extend from product renewal subsidies to increasing residents' consumption capacity, expanding service consumption, and building consumption infrastructure. Based on the consumer goods trade-in policy, it is expected that financial support in 2027 will be more skewed towards fields such as old-age care, cultural tourism, sports and entertainment, and digital consumption, to improve consumer financing conditions and effective supply by continuing interest rates on personal consumer loans, expanding loan support for service industry operators, and optimizing consumer infrastructure investment. For regions where demand is clearly insufficient, local governments may issue targeted vouchers based on financial resources and consumption scenarios, and explore methods such as digital write-off and collaborative financial and platform subsidies to improve the efficiency of actual consumption transformation of policy funds. In the medium to long term, it is necessary to improve residents' consumption expectations through increased employment income and social security, and reduce the limitations of simply relying on short-term subsidies to drive consumption.
Industrial policies are expected to shift further from investment expansion to technology application and profit fulfillment, while capital market policies focus more on stabilizing expectations and improving the quality of listed companies. Focusing on artificial intelligence, advanced manufacturing, and modern infrastructure, it is expected that the policy will strengthen the opening of application scenarios, supply of industry data, technology finance, and initial application support, and promote the transformation of technological innovation into actual productivity and commercial benefits. It is expected that the construction of a unified national market and “anti-internal circulation” management will continue to improve the industrial profit environment by regulating local investment promotion, improving fair competition rules, and promoting the orderly adjustment of inefficient production capacity. On the capital market side, stock repurchases and refinancing have moved to long-term institutional arrangements. It is expected that 2027 will further optimize the exchange facilitation mechanism for securities, funds, and insurance companies and the use of repurchase support tools, and enhance capital market stability through medium- to long-term capital entry, improving the quality of dividend repurchases, and improving the governance of listed companies. Overall, the key effect of the 2027 policy will be a further shift from the scale of incremental capital to capital transmission efficiency, restoration of endogenous demand, and improvement of corporate profits.
Major asset allocation recommendations
(1) Gold and commodities: Gold fluctuates at a high level, and oil prices are affected by a combination of supply and demand and geographical risks
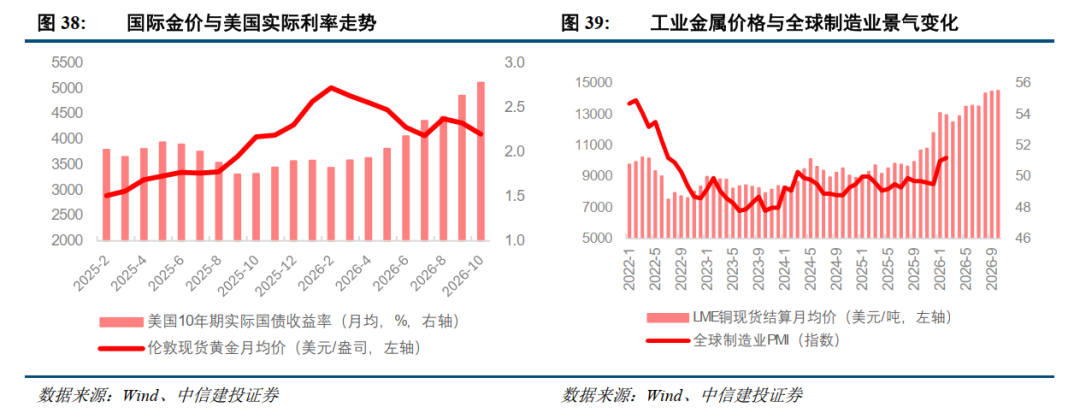
Gold still has strategic allocation value in 2027, but its main role is to diversify portfolio risk rather than provide deterministic unilateral upward returns. The diversification of global central bank reserves, sovereign credit risk, and geopolitical uncertainty still provide medium- to long-term support for gold, but the price of gold is also affected by the real interest rate of the US dollar and global liquidity. In 2026, the average monthly price of London spot gold fell from about 5020 US dollars/ounce in February to about 4106 US dollars/ounce in October, a drop of about 18%, indicating that the safe-haven attribute does not mean that the price fluctuation is low. The price of gold is affected by a combination of factors such as the actual interest rate of the US dollar, liquidity, and safe-haven demand. The 2027 allocation should focus on medium- to long-term risk hedging values, and also be wary of the risk of valuation adjustments after a large increase in the previous period. If the real interest rate of the US dollar falls in 2027, compounded by rising global fiscal and geographical risks, the value of gold allocation is expected to increase further; if US interest rates remain high and the liquidity of the US dollar tightens, the price of gold may still be under pressure in stages. In terms of allocation, it is recommended to maintain moderate strategic positions and lay out in batches during the price adjustment process to avoid chasing rapid increases driven by short-term events.
Crude oil allocation should be prudent; it is more suitable for seizing phased opportunities brought about by changes in supply and demand, rather than continuing one-sided upward expectations in 2026. In September 2026, the average spot price of Brent crude oil was about 114 US dollars/barrel. The EIA expects the average price to fall back to 84 US dollars/barrel in 2027, reflecting that the restoration of energy supply may depress the oil price center, but geographical conflicts and transportation risks may still cause phased price recurrence. Under the benchmark scenario of gradual recovery of oil production and transportation in the Middle East, improved supply and inventory recovery may drive the central decline in oil prices, but geographical conflicts and uncertainty about key shipping routes may still cause phased price jumps. As a result, investment opportunities in crude oil are more likely to be reflected in a volatile market due to supply disturbances rather than a continuous upward trend. The configuration should focus on tracking actual production recovery, commercial inventory and shipping conditions to avoid excessive increase after the geographical risk premium rises rapidly.
There are structural allocation opportunities for industrial metals, but the supply and demand conditions and price elasticity of different types may be clearly differentiated. In 2025, the global manufacturing PMI was near or below the boom and bust line for most months, but copper prices are still on the rise. In October 2026, the average monthly LME copper spot price further reached about 14,500 US dollars/ton. In addition to being affected by the traditional manufacturing cycle, industrial metal prices may also be affected by structural demand and supply constraints such as power grids and computing power investments. Power infrastructure upgrades, energy transformation, and digital investment are expected to support medium- to long-term demand for some metals, but weak demand in traditional industries, supply expansion, and upfront price increases may also limit further upward space. Compared with an overall increase in industrial metals, more attention should be paid to varieties where physical demand continues to grow, supply expansion is limited, and inventory levels are low, distinguishing between improvements in fundamentals and price increases driven by short-term capital transactions.
(2) Domestic risk assets: A-shares focus on structural opportunities, and the bond market may remain volatile
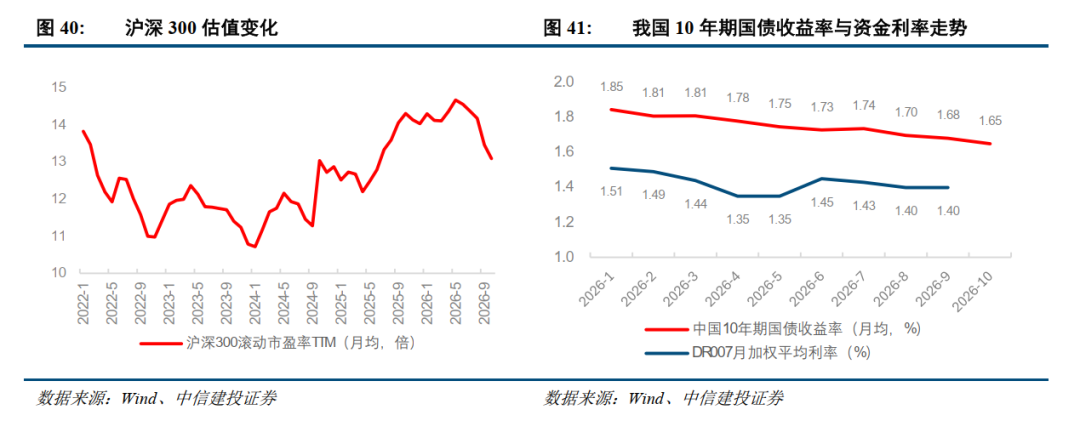
The 2027 A-share allocation proposal remains neutral and positive. Market opportunities may come more from improvements in corporate profits than from a general rise in valuation centers. After market adjustments in 2026, valuation pressure on some assets has been released, but whether the recovery in valuation can continue depends on improvements in profit expectations and investor confidence. It is expected that active macroeconomic policies will help stabilize market expectations, but when domestic demand has not fully recovered, there may still be large differences in the profit performance of different industries. If subsequent corporate profit improvements spread from a few booming sectors to more industries, the overall allocation appeal of A-shares is expected to increase; if profit recovery is still concentrated, the market may continue to be dominated by structural opportunities, and the basis for overall growth is relatively limited.
Equity portfolios should balance growth elasticity with return stability, and focus on matching valuation, profit growth, and cash flow. Growth assets still have long-term allocation value, but priority should be given to companies that have clear competitive advantages, can fulfill profit expectations, and whose valuation matches the medium term growth space, and avoid simply relying on industrial concepts or policy expectations for pricing. At the same time, high-dividend assets with steady management and strong dividend capacity can still help reduce portfolio fluctuations, but attention should also be paid to the sustainability of dividends and long-term corporate profitability to avoid judging investment value only by higher dividend rates. Overall, the 2027 equity allocation is more suitable for seeking a balance between profit certainty and room for growth, rather than focusing on a single market style.
Domestic bonds are expected to maintain a volatile pattern in a low interest rate environment. The allocation should be based on coupon income and short term periods to carefully grasp long-term interest rate trading opportunities. From January to October 2026, the average monthly yield on China's 10-year treasury bonds fell from 1.85% to 1.65%. The overall capital interest rate remained low during the same period, reflecting the loose monetary and financial environment supporting the bond market. However, as yields fall further, bond prices are more sensitive to interest rate rebounds, and in 2027, we still need to pay attention to the risk of adjustments brought about by changes in government bond supply, economic recovery, and inflation expectations. The slow recovery in domestic demand and a supportive monetary environment still support the bond market, but with the current yield being relatively low, there may be limited room to further rely on a sharp decline in interest rates to obtain capital gains. If economic recovery falls short of expectations, there is still a chance for long-term interest rates to decline; if fiscal spending accelerates, the supply of government bonds increases, or inflation expectations pick up, it may trigger phased adjustments. It is recommended to use short- and medium-term interest rate bonds and high-grade credit bonds as the basic allocation, and take the opportunity to increase the term after the yield is adjusted. In terms of credit bonds, more attention should be paid to the issuer's real solvency and liquidity to avoid excessive decline in qualifications when credit spreads are low.
(3) US stocks and US bonds: US stocks are concerned about the fulfillment of profits, and US bonds are constrained by interest rates and financial supply
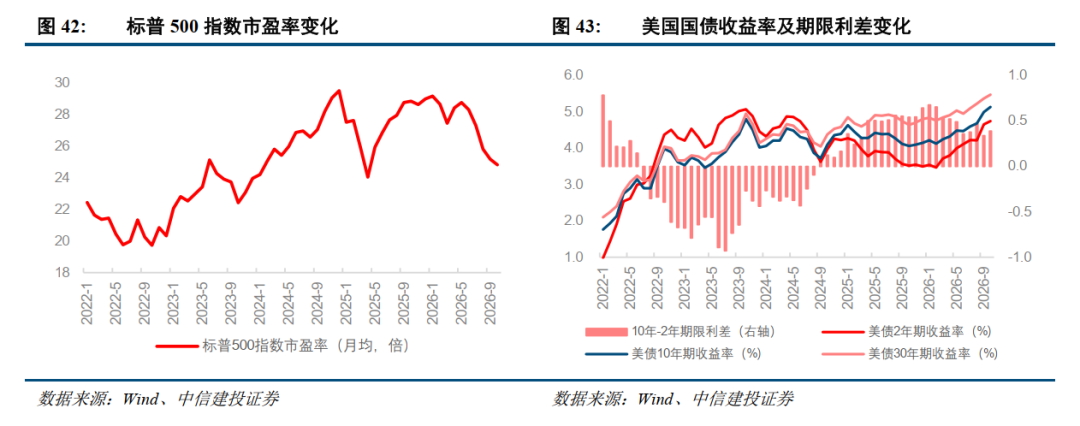
The 2027 US stock allocation proposal remains neutral and cautious, and the performance of overvalued assets will depend more on whether profit growth can continue to be realized. The price-earnings ratio of the S&P 500 index fell from an average monthly average of 29.20 times in January to 24.85 times in October. Although the valuation has been adjusted to a certain extent, it is still higher than the level of about 20 times for part of 2022. With valuations still relatively high, whether US stocks can receive further upward support in 2027 will depend more on corporate profit growth and actual implementation of capital returns. The US technology industry still has strong innovation capabilities and global competitive advantages, but some corporate valuations already include high future growth expectations. Profits or capital returns fall slightly short of expectations, which may trigger larger price adjustments. At the same time, higher long-term interest rates will continue to affect corporate financing costs and equity asset valuations, and place more obvious restrictions on growth assets whose profits are mainly concentrated in the long term. Therefore, investment in US stocks needs to pay more attention to matching profit growth with valuation levels, so as not to simply infer that related stocks have room to continue to rise based on the expansion of the scale of technology investment.
Internal US stock proposals give priority to companies with abundant free cash flow, high capital efficiency, and stable competitive advantage, and moderately reduce concentrated exposure to high-valuation and high-capital expenditure sectors. For technology companies, the key is not only revenue and order growth, but also whether new investments can generate corresponding profits and cash flow; for companies with relatively stable profits, they need to pay attention to their pricing capacity, debt structure, and continuous dividend ability. In an environment where the return on technology investment has yet to be verified, defensive assets with stable cash flow and less pressure on capital expenditure can be moderately allocated to improve the risk-return characteristics of the portfolio. It is expected that the return on investment in US stocks in 2027 may be more dependent on the company's own operating performance, and earnings differentiation within the market will continue.
US bonds have relatively high coupon appeal, but long-term yields are still constrained by financial financing pressure and term premiums, so it is not appropriate to simply bet on a continuous bond bull market. From January to October 2026, the average monthly yield on US 10-year and 30-year Treasury bonds rose from 4.21% and 4.84% to 5.13% and 5.47%, respectively, and long-term financing costs rose markedly. The long-term yield on US bonds not only depends on monetary policy, but is also affected by factors such as inflation expectations, continued demand for debt issuance, and term premiums. Even if policy interest rates stabilize or are lowered in the future, long-term yields will not necessarily decline at the same time. The short-term yield on US bonds in 2027 will reflect more changes in the Fed's policy, while the long-term will also be affected by inflation expectations, treasury bond supply, and market risk premiums. The two trends may not be completely consistent. Even if policy interest rates fall, long-term treasury bond yields may remain high due to high demand for fiscal financing. In terms of allocation, it is recommended that priority be given to short- and medium-term US bonds, using coupon income as the main source, and controlling the risk of capital loss due to interest rate fluctuations; long-term bonds are more suitable for allocating opportunities after a marked economic slowdown, continued improvement in inflation, or long-term yield adjustments. For domestic investors, it is also necessary to include changes in the US dollar exchange rate in the actual investment return assessment to avoid judging the allocation value based only on the US dollar return.
(4) Exchange rate: RMB may continue the two-way fluctuation pattern to mitigate appreciation
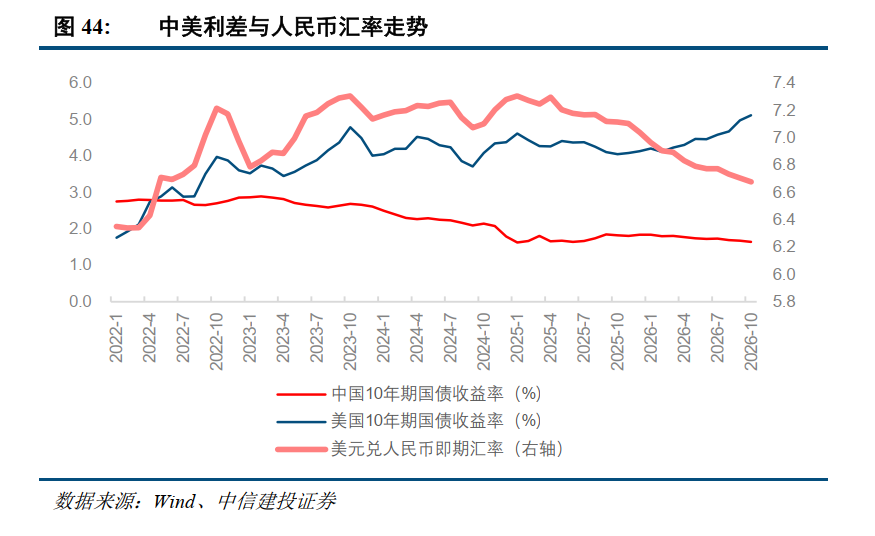
The RMB exchange rate is expected to maintain a two-way fluctuating, moderate and strong basic pattern in 2027, but the conditions for continued rapid appreciation are insufficient. China's balance of payments and manufacturing competitiveness will still help stabilize RMB exchange rate expectations, and improvements in domestic economic fundamentals may further enhance the attractiveness of RMB assets. However, the trend of RMB depends not only on domestic economic performance, but is also affected by a combination of US dollar interest rates, global risk appetite, and cross-border capital flows. From January to October 2026, the spread on 10-year treasury bonds between China and the US widened further from about -2.37 percentage points to -3.48 percentage points, but the spot exchange rate of the US dollar against the RMB fell from about 6.97 to 6.68 during the same period, and the RMB is still appreciating. Looking ahead to 2027, even if the gap between China and the US remains highly inverted, the RMB is likely to remain resilient, supported by improved foreign trade surpluses and exchange rate expectations. If US inflationary pressure eases, US dollar interest rates fall, and domestic demand continues to recover, the RMB is expected to appreciate further moderately; if US interest rates remain high, global financial market fluctuations increase, or international trade frictions escalate, the RMB may still face phased adjustments. It is expected that the exchange rate operation will be more flexible in both directions, and expectations of unilateral appreciation should not be excessively strengthened.
In asset allocation, more attention should be paid to the impact of exchange rate changes on the actual return on cross-border investment to avoid directly treating the nominal return on foreign currency assets as the final return on investment. For domestic investors holding US dollar assets, even if the yield on US bonds or US stocks is good, the appreciation of the RMB may still erode the actual return after conversion; conversely, the phased strengthening of the US dollar may also amplify returns on foreign currency assets, but at the same time increase the risk of exchange rate fluctuations. Therefore, in 2027, cross-border asset allocation should consider the return prospects, exchange rate risks and hedging costs of the assets themselves in an integrated manner, and manage exchange rate exposure according to the investment period and actual foreign currency demand. Overall, compared to betting on the unilateral trend of RMB or the US dollar, it is more important to maintain a moderate diversification of currency allocations and the ability to hedge risks.
Main investment recommendations
Looking ahead to 2027, uncertainty in the global macro environment coexists with the upgrading of the domestic industrial structure, and investment opportunities are expected to be further concentrated in fields with continuous demand, competitive technological advantages, and the ability to deliver profits. Combining the implementation of major “15th Five-Year Plan” projects, the acceleration of the application of artificial intelligence, the restructuring of consumption, and the development trend of manufacturing globalization, it is recommended to focus on the four main investment lines of scientific and technological innovation, smooth infrastructure cycle, consumption improvement and expansion, and advantageous manufacturing industries going overseas. Compared to the investment logic that relied on policy expectations and capital expenditure expansion in the early stages, in 2027, more attention should be paid to the actual transmission of industrial sentiment to corporate orders, profit margins, and operating cash flow.
(1) Science and technology innovation sector
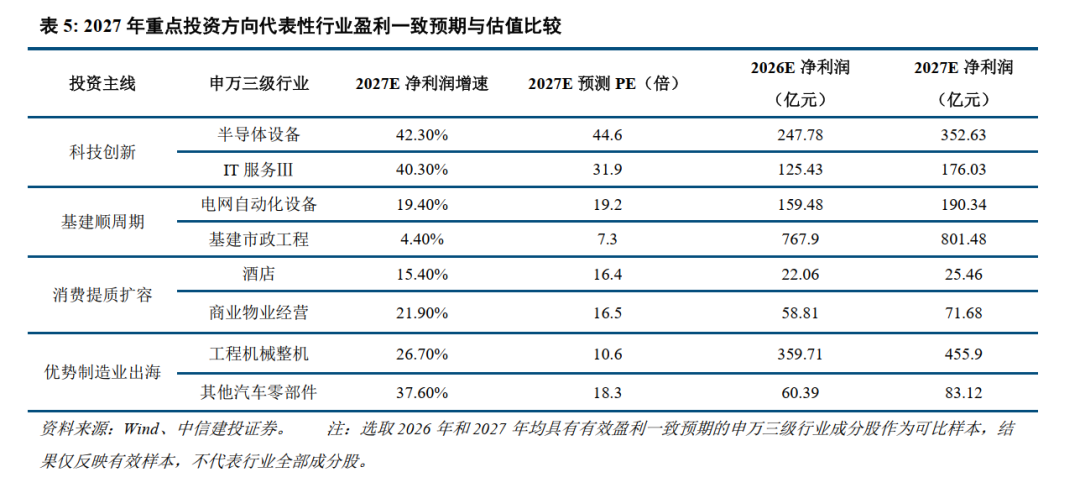
In the field of scientific and technological innovation, priority is given to key links where technical barriers are high, products have entered the industrialization stage, and can continue to expand market share. As the domestic industrial chain accelerates technological upgrading, fields such as semiconductor equipment and materials, advanced packaging, industrial mother machines, precision sensors, and industrial control still have a lot of room for development. In 2027, semiconductor equipment and IT service-related samples all agree that the profit growth rate is around 40%, but the price-earnings ratio is predicted to be about 45 times and 32 times, respectively. Higher growth expectations place higher demands on performance delivery. Investment should focus on enterprises that have completed customer certification, entered the batch supply stage, and have the ability to continuously iterate. If key technological breakthroughs, domestic substitution progress, and downstream order release exceed expectations, related links are expected to gain room for further profit growth.
The AI industry chain can focus on grasping the three types of opportunities: infrastructure technology upgrading, commercialization of industry applications, and AI governance, but the growth drivers of different links should be distinguished. In the hardware sector, advanced storage, optical communication, liquid cooling and high-performance computing supporting equipment are still expected to benefit from computing power system upgrades, and enterprises with technical advantages, customer base, and the ability to increase product value are relatively more competitive. The application area should focus on products that can be embedded in the core business processes of the enterprise and have quantifiable cost reduction and efficiency effects, such as industrial quality inspection, predictive equipment maintenance, intelligent production scheduling, and enterprise-level software services. Compared to the number of applications deployed, customer willingness to continue to pay, implementation costs, and ability to replicate across customers can better reflect the quality of commercialization. In terms of AI governance, demand for model security evaluation, data compliance, intelligent risk protection, and continuous secure operation is expected to grow as large models and agents penetrate the financial, government, and manufacturing sectors. In terms of investment, priority should be given to enterprises with mature products, industry customer base and continuous service capabilities, focusing on actual orders, customer payments, and profit contributions from related businesses.
Frontier fields such as commercial aerospace and physical intelligence are expected to form new industrial growth space, but the investment value still needs to be verified by product maturity and large-scale demand. Related industries are rapidly iterating on technology, investing heavily in early R&D and equipment, and some enterprises have yet to form a stable source of revenue. It is recommended to pay more attention to substantial developments such as breakthroughs in core technology, product finalization, customer introduction and batch delivery, and give priority to companies that have formed competitive advantages in key components, control systems, or industrial support links to avoid directly equating long-term market space with short-term profit growth.
(ii) Implement the national strategy in the infrastructure development cycle
Infrastructure investment opportunities in 2027 will be more dependent on the implementation of capital for key projects and the progress of equipment procurement, and the degree of benefit from the industrial chain may be clearly divided. As major “15th Five-Year Plan” projects enter the continuous implementation stage, infrastructure investment is expected to provide order support for related industries, but the planned scale of the project does not directly correspond to the revenue and profits of listed companies. According to consistent profit estimates from a sample of representative companies, the net profit of power grid automation equipment is expected to increase by 19.4% in 2027, corresponding to the predicted PE by 19.2 times; the net profit of infrastructure and municipal engineering is expected to increase by 4.4%, corresponding to the predicted PE by about 7.3 times, reflecting differences in profit growth expectations between the equipment side and traditional engineering construction processes. Compared to simply expanding the scale of project construction, this round of infrastructure upgrades places more emphasis on equipment updates, operation efficiency, and network collaboration. Investments should focus on industrial chain links with adequate financial security, clear tendering and procurement schedules, and high technical standards, and distinguish differences in profit models and capital recovery cycles between equipment manufacturing, engineering construction, and subsequent operations.
The construction of new power grids and telecommunication collaboration is a key direction that combines continuous demand and space for technological upgrading. The increase in the proportion of new energy access, the development of distributed energy, and the increase in electricity demand in data centers place higher demands on power grid regulation capacity, power supply reliability, and operation efficiency. Relevant investment opportunities exist not only in new transmission and transformation equipment, but also in intelligent distribution, power grid automation, energy storage control, power quality management, and energy management systems. Computing collaboration is expected to further drive the demand for highly reliable power supply and distribution, energy scheduling, and electricity efficiency optimization. Compared with traditional engineering construction, the market space in these areas is more dependent on equipment technology upgrades and stock system transformation, and enterprises with technical standards, customer certification and product support advantages are expected to continue to benefit.
The renewal of water networks, urban underground pipelines, and logistics facilities should pay more attention to the equipment and operation service requirements brought about by stock renovation. The renewal of water networks and underground pipelines is expected to drive demand in industrial chains such as pipe equipment, pumps and valves, intelligent metering, pipeline network inspection, and smart water services, while upgrading logistics facilities may promote automated warehousing, intelligent sorting, and logistics informatization transformation. Unlike new construction projects, which mainly rely on one-time construction investments, the renewal of existing facilities may also require continuous inspection and maintenance, equipment replacement, and operation management. However, traditional construction businesses usually face high capital usage and long repayment cycles, and some projects are still constrained by local financial capacity. In terms of investment, relatively priority can be given to enterprises with a high degree of product standardization, outstanding equipment technical advantages, and good project repayment guarantees, and carefully evaluate the impact of low price competition and the accumulation of accounts receivable on operating profits.
(3) Improving the quality and expansion of consumption
Structural opportunities in the consumer sector in 2027 come more from high-quality supply and improved business models rather than the simultaneous expansion of total consumption. In a context where it still takes time for consumer consumption to recover, different consumer sectors may show clear growth differentiation. In October 2026, relevant state departments introduced policies to strengthen consumer infrastructure construction to support the upgrading of commercial facilities, cultural tourism and sports, pension and childcare, and the construction of digital consumer facilities, which is expected to promote the improvement of consumer supply and the upgrading of stock assets. According to the consistent profit estimates of representative companies, the net profit of the hotel and commercial property business sample in 2027 is expected to increase by 15.4% and 21.9%, respectively, corresponding to the predicted PE by about 16.4 times and 16.5 times. There is still some room for profit growth in related fields. Investments can focus on tourism operators, hotel accommodations, and commercial facility operators with stable customer sources, high-quality content resources, and mature operating systems, especially those that can achieve profitable growth through increased passenger flow, improved occupancy rates, and cost control.
The long-term growth opportunities for service consumption are worth watching, but there is still a big difference between expanding demand and corporate profits. Demographic changes are expected to continue to drive demand in fields such as old-age care, health care services, health management, and high-quality housekeeping. Experiential consumption such as cultural tourism, sporting events, and entertainment also has plenty of room for development. The continuous improvement of consumer infrastructure is expected to further improve the supply of related services, but the service industry usually has characteristics such as high labor costs and strong operation and management requirements, and the increase in market demand will not necessarily lead to a simultaneous increase in profitability. Among them, enterprises with standardized service systems, stable customer sources, and large-scale operation capabilities are more likely to form competitive advantages through improved service quality and operational efficiency. In terms of investment, more attention should be paid to matching service capabilities with pricing levels to avoid judging the growth space of relevant enterprises based only on demographic trends or potential market size.
The commodity consumption sector should focus on the incremental demand brought about by technological innovation, product iteration, and brand competitiveness. Smart terminals, wearable devices, and new consumer electronics products incorporating artificial intelligence functions are expected to drive demand for some product updates through functional upgrades and improved user experience. Compared to sales growth that relies on policy subsidies or price promotions, companies with differentiated products, strong R&D capabilities, and mature sales channels have a better chance of forming continuous brand premiums and user stickiness. However, consumer electronics products still face constraints such as rapid technological iteration, fierce competition, and inventory management. Investments need to pay attention to new product sales performance, product gross margin, and channel efficiency to avoid directly treating the popularity of new products in the short term as the ability to continue to grow.
(4) Competitive manufacturing companies going overseas and improving global competitiveness
Investment opportunities for dominant manufacturing industries to go overseas in 2027 will focus more on increasing overseas market share and increasing operating profits, rather than simply expanding the scale of exports. Fields such as power equipment, construction machinery, high-end equipment, industrial automation, and some auto parts are still expected to benefit from overseas infrastructure construction, industrial upgrading, and equipment renewal needs. According to sample estimates from representative companies, the net profit of complete construction machinery and other auto parts is expected to increase by 26.7% and 37.6% respectively in 2027, corresponding to the predicted PE is about 10.6 times and 18.3 times, indicating that related fields have certain profit growth expectations and valuation appeal. Among them, power equipment companies can pay attention to equipment and system integration requirements brought about by overseas power grid transformation and energy infrastructure projects; construction machinery and industrial equipment companies may enhance global competitiveness through product upgrades, channel expansion, and after-sales service. Compared with the increase in export volume, enterprises with technical standard advantages, overseas customer certification, and complete product service capabilities have a better chance of obtaining stable orders and reasonable profits.
Overseas localization will become an important way for the manufacturing industry to improve market competitiveness, but its costs and benefits require a comprehensive assessment. Facing international trade barriers and regionalized supply chain adjustments, some enterprises may further approach the terminal market through overseas assembly, local production, warehousing and distribution, and after-sales network construction to improve delivery efficiency and customer service capabilities. However, localized investment also means an increase in upfront capital investment, operation management, and compliance costs, and there is still uncertainty about whether overseas production capacity can form stable orders. Therefore, the internationalization path of different enterprises should match their product characteristics, customer distribution, and market size. It cannot simply be assumed that the more overseas factories are built, the stronger the international competitiveness.
The profit quality and return on capital from an enterprise's overseas business will be an important screening criterion for overseas investment in the manufacturing industry in 2027. It is recommended that priority be given to advantageous enterprises that have established a global customer base, international channels and localized service systems, and focus on examining the gross profit margin of overseas business, order delivery, accounts receivable collection, and return on overseas capital expenses. For enterprises with continuous after-sales service, parts supply and technology upgrading capabilities, overseas revenue sources are expected to gradually expand from disposable product sales to equipment maintenance, parts updates and integrated solutions, enhancing customer stickiness and profit stability. At the same time, attention still needs to be paid to the impact of tariffs and trade remedy measures, overseas operating costs, exchange rate changes, and geopolitical risks on profits. Overall, the investment value of the manufacturing industry going overseas in 2027 is more likely to come from the improvement of companies' global management capabilities and the actual contribution of overseas business to profit growth.