


Just because a business does not make any money, does not mean that the stock will go down. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
Given this risk, we thought we'd take a look at whether Suven Life Sciences (NSE:SUVEN) shareholders should be worried about its cash burn. For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. Let's start with an examination of the business' cash, relative to its cash burn.
How Long Is Suven Life Sciences' Cash Runway?
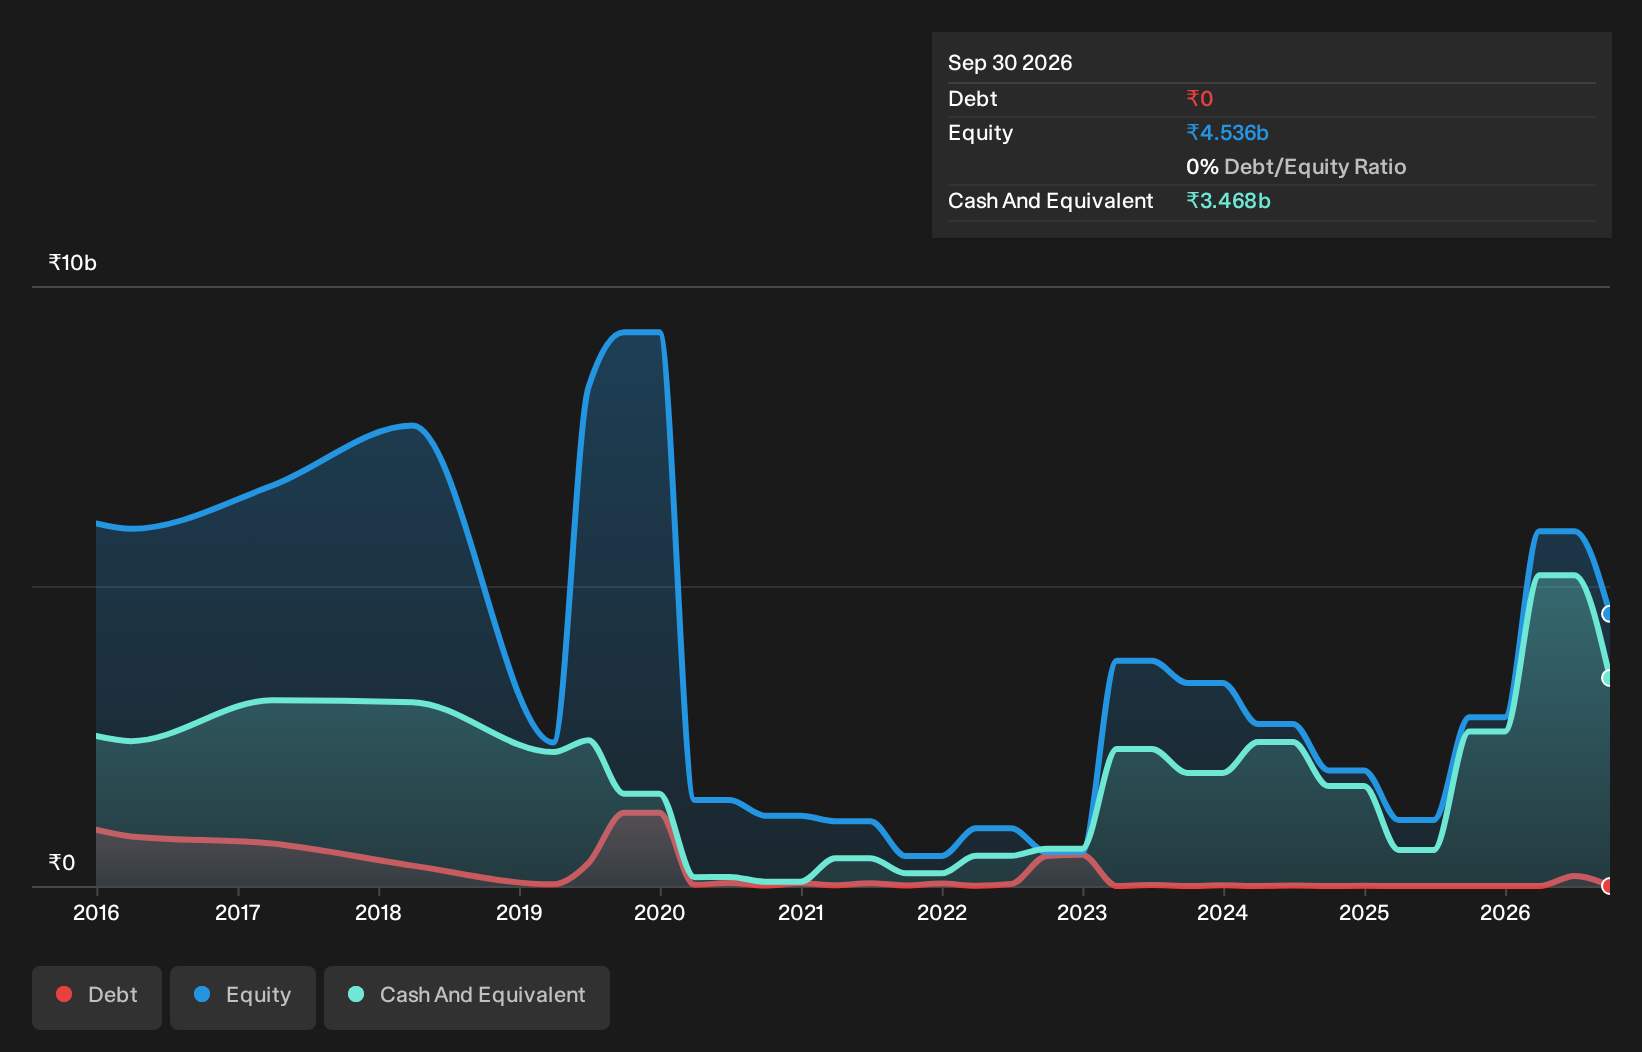
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. When Suven Life Sciences last reported its September 2026 balance sheet in November 2026, it had zero debt and cash worth ₹3.5b. In the last year, its cash burn was ₹4.7b. Therefore, from September 2026 it had roughly 9 months of cash runway. To be frank, this kind of short runway puts us on edge, as it indicates the company must reduce its cash burn significantly, or else raise cash imminently. The image below shows how its cash balance has been changing over the last few years.
See our latest analysis for Suven Life Sciences
How Is Suven Life Sciences' Cash Burn Changing Over Time?
In our view, Suven Life Sciences doesn't yet produce significant amounts of operating revenue, since it reported just ₹91m in the last twelve months. Therefore, for the purposes of this analysis we'll focus on how the cash burn is tracking. In fact, it ramped its spending strongly over the last year, increasing cash burn by 116%. It's fair to say that sort of rate of increase cannot be maintained for very long, without putting pressure on the balance sheet. Suven Life Sciences makes us a little nervous due to its lack of substantial operating revenue. We prefer most of the stocks on this list of stocks that analysts expect to grow.
How Hard Would It Be For Suven Life Sciences To Raise More Cash For Growth?
Given its cash burn trajectory, Suven Life Sciences shareholders should already be thinking about how easy it might be for it to raise further cash in the future. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Commonly, a business will sell new shares in itself to raise cash and drive growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
Suven Life Sciences has a market capitalisation of ₹79b and burnt through ₹4.7b last year, which is 5.9% of the company's market value. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
Is Suven Life Sciences' Cash Burn A Worry?
On this analysis of Suven Life Sciences' cash burn, we think its cash burn relative to its market cap was reassuring, while its increasing cash burn has us a bit worried. Looking at the factors mentioned in this short report, we do think that its cash burn is a bit risky, and it does make us slightly nervous about the stock. On another note, Suven Life Sciences has 4 warning signs (and 2 which can't be ignored) we think you should know about.
Of course Suven Life Sciences may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.