


- Kratos Defense & Security Solutions recently reported third quarter 2026 revenue of US$471.8 million with a small net loss of US$0.2 million, maintained year to date net income of US$16.1 million, and secured contracts for NASA’s Space Reactor 1 power system and THAICOM 10 satellite gateway infrastructure.
- The combination of Q/V/Ka band ground systems for THAICOM 10 and a US$33.6 million power conversion award for NASA’s SR 1 Freedom highlights how Kratos Defense & Security Solutions is integrating space, propulsion, and software defined infrastructure into longer duration programs and a record multi billion dollar backlog.
- This article examines how Kratos Defense & Security Solutions’ raised guidance and record backlog relate to the investment narrative that investors are tracking.
Scan beyond Kratos Defense & Security Solutions and compare it with other contractors riding similar defense and space demand through our hand picked 30 resilient stocks with low risk scores.
Kratos Defense & Security Solutions Investment Narrative Recap
To own Kratos Defense & Security Solutions, you need to believe that today’s record US$2.6b backlog and hypersonics, propulsion, and space contracts turn into durable production work with better profitability. In the short term, the swing factor is execution on this heavier workload, especially in unmanned systems where fixed price contracts have already pressured margins and kept net income modest.
On the risk side, the analyst consensus Narrative on Simply Wall St points to foreign exchange headwinds, cash tied up in working capital, and elevated capex. The recent THAICOM 10 and NASA SR 1 awards are helpful for visibility, but they do not yet change those near term constraints in a material way.
The THAICOM 10 gateway contract looks most relevant to the current news, because it sits exactly at the intersection of Kratos Defense & Security Solutions' space ground systems and software defined infrastructure story. Q/V/Ka band gateways, integrated monitoring and control, and diversity sites all feed into the space segment backlog that analysts already flag as a key earnings driver.
Operationally, this project ties directly into the space and satellite catalyst set in the analyst consensus Narrative on Simply Wall St. OpenSpace software and prior missile warning awards support a US$600m backlog. Execution quality on THAICOM 10, schedule discipline, and cost control will be important markers for whether those space contracts can offset FX, working capital, and unmanned margin pressure.
Kratos Defense & Security Solutions' current analyst narrative ties to revenue projections of US$2.9b and earnings of US$180.7m by 2029, built on an assumed 24.6% yearly top line expansion and an earnings move of about US$149.8m from US$30.9m today to that 2029 consensus level.
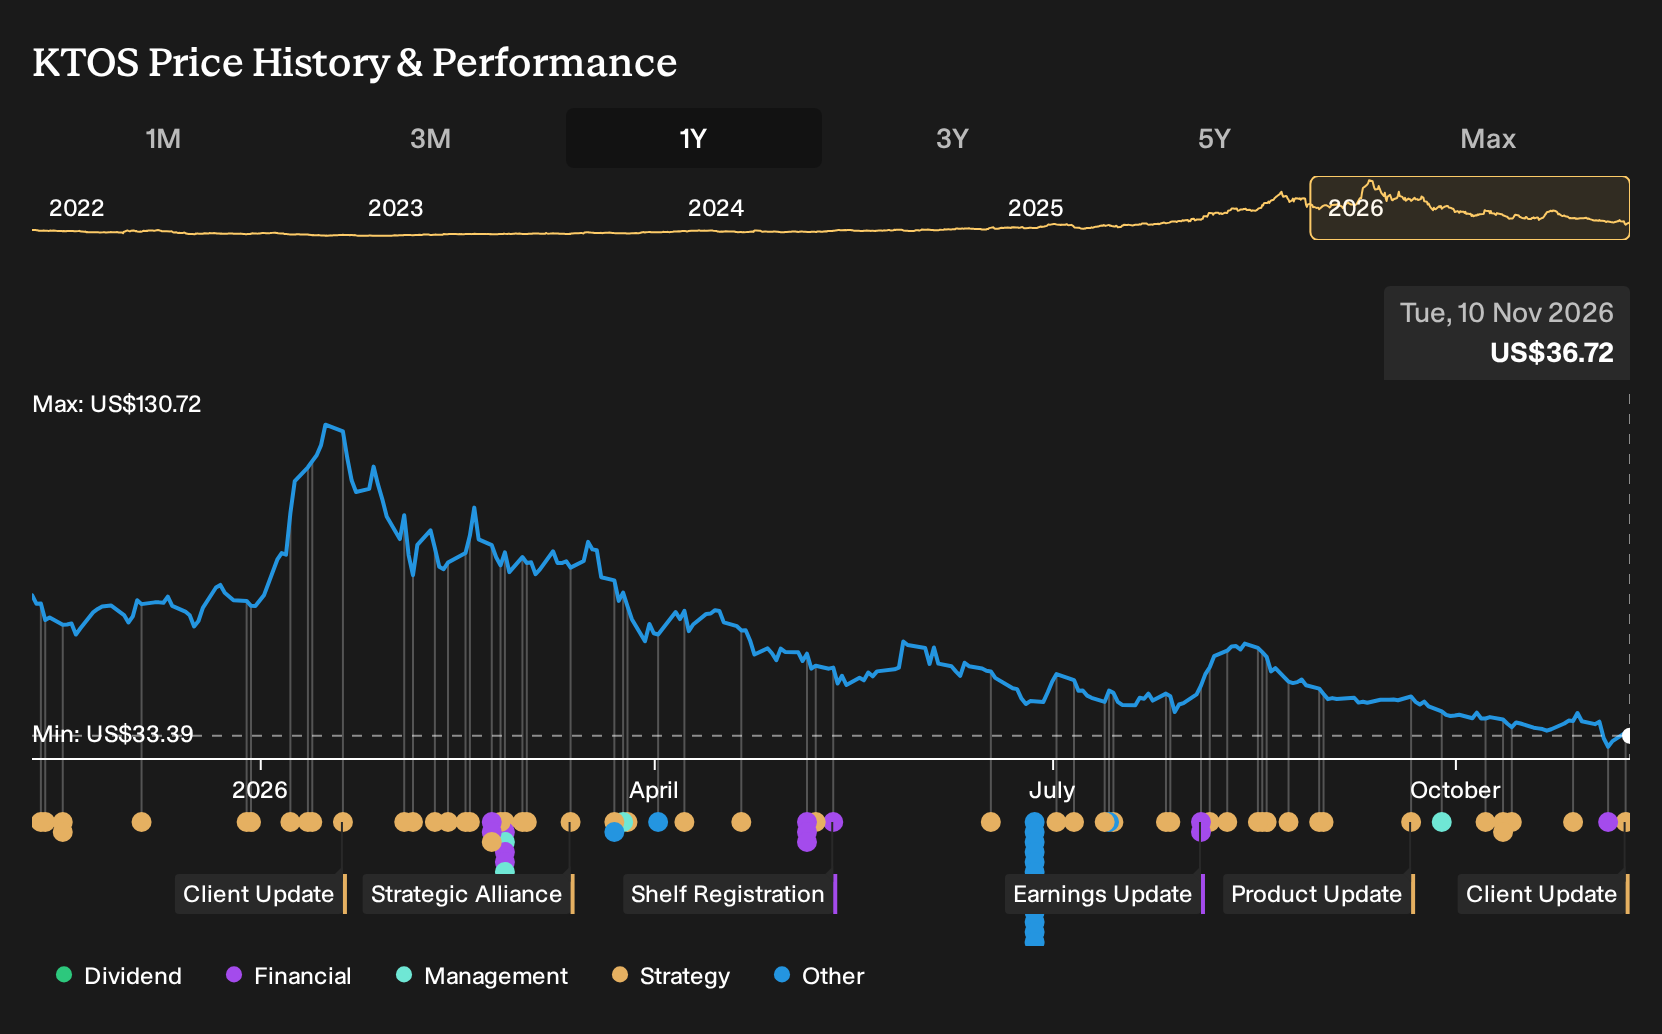
Uncover how Kratos Defense & Security Solutions' fair value indicates a 157% potential upside to its current price before the discount gap closes.
Exploring Other Perspectives
One alternate view focuses on revenue quality rather than contract wins like THAICOM 10. The most bearish analysts were penciling in revenue of about US$2.9b and earnings of US$105.9m by 2029 before this news, which is far below the consensus earnings of US$180.7m. That gap shows how widely opinions can differ, so it pays to compare several narratives before deciding what this gateway award might mean to you.
Explore 5 other Kratos Defense & Security Solutions fair value estimates, including one that suggests as much as 100% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kratos Defense & Security Solutions research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kratos Defense & Security Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kratos Defense & Security Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kratos Defense & Security Solutions?
Once you have a view on Kratos Defense & Security Solutions, it can help to cross check that thesis against other stocks that share similar qualities or offer very different risk and reward profiles. The Simply Wall St Screener gives you a way to move from a single ticker to a watchlist that fits your own style.
- For investors focused on income resilience, consider companies that combine robust balance sheets with meaningful payouts through our 5 dividend fortresses.
- If capital preservation and a smoother ride are higher on your list than rapid gains, scan for businesses with steadier risk characteristics using the 30 resilient stocks with low risk scores.
- When you want to widen the opportunity set beyond widely followed tickers, filter for under the radar quality through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com