


- Atmos Energy announced in November 2026 that Chairman Kim R. Cocklin will retire at the 2027 annual meeting, outlined a fiscal 2027 earnings per diluted share range of US$9.05 to US$9.25, and set a quarterly dividend of US$1.09, indicating an annual payout of US$4.36.
- The 172nd consecutive quarterly dividend and updated earnings guidance give investors fresh data points on how Atmos Energy is balancing heavy infrastructure spending, regulatory frameworks and shareholder cash returns.
- The next focus will be on how Atmos Energy's updated earnings guidance shapes the existing investment narrative around capital intensity and dividends.
Scan beyond Atmos Energy and compare this earnings and dividend story with a curated 5 dividend fortresses that are also committing meaningful cash to investors.
Atmos Energy Investment Narrative Recap
To own Atmos Energy, you need to be comfortable with a regulated utility that leans heavily on multi year capital projects and ongoing rate proceedings, as described in the analyst consensus Narrative on Simply Wall St. The short term swing factor is still how effectively that US$4.2b fiscal 2026 spending and higher operating and maintenance budget translate into allowed returns under existing regulation.
The biggest operational risk remains that costs, including safety, legal and compliance expenses, move faster than what regulators are willing to include in customer bills. The latest earnings guidance and dividend move do not fundamentally change that picture. They mostly refresh expectations rather than reset the core thesis or risk profile.
The dividend increase to an indicated US$4.36 per share for fiscal 2027 is the clearest data point to focus on. It extends Atmos Energy's long dividend record while capital needs and debt coverage concerns remain in the background. For an income focused holder, that mix of cash returns and spending plans is where attention naturally goes next.
With a dividend yield flagged as not well covered by free cash flow and debt described as not well covered by operating cash flow, the higher payout sharpens the question around funding. It sits right alongside catalysts like customer growth, supportive Texas legislation and recent rate outcomes, and it keeps execution on financing and regulatory decisions firmly in the spotlight.
Atmos Energy's analyst narrative points to revenue of US$6.7b and earnings of US$1.9b by 2029, based on 10.6% yearly revenue growth and an earnings increase of about US$500m from current earnings of US$1.4b.
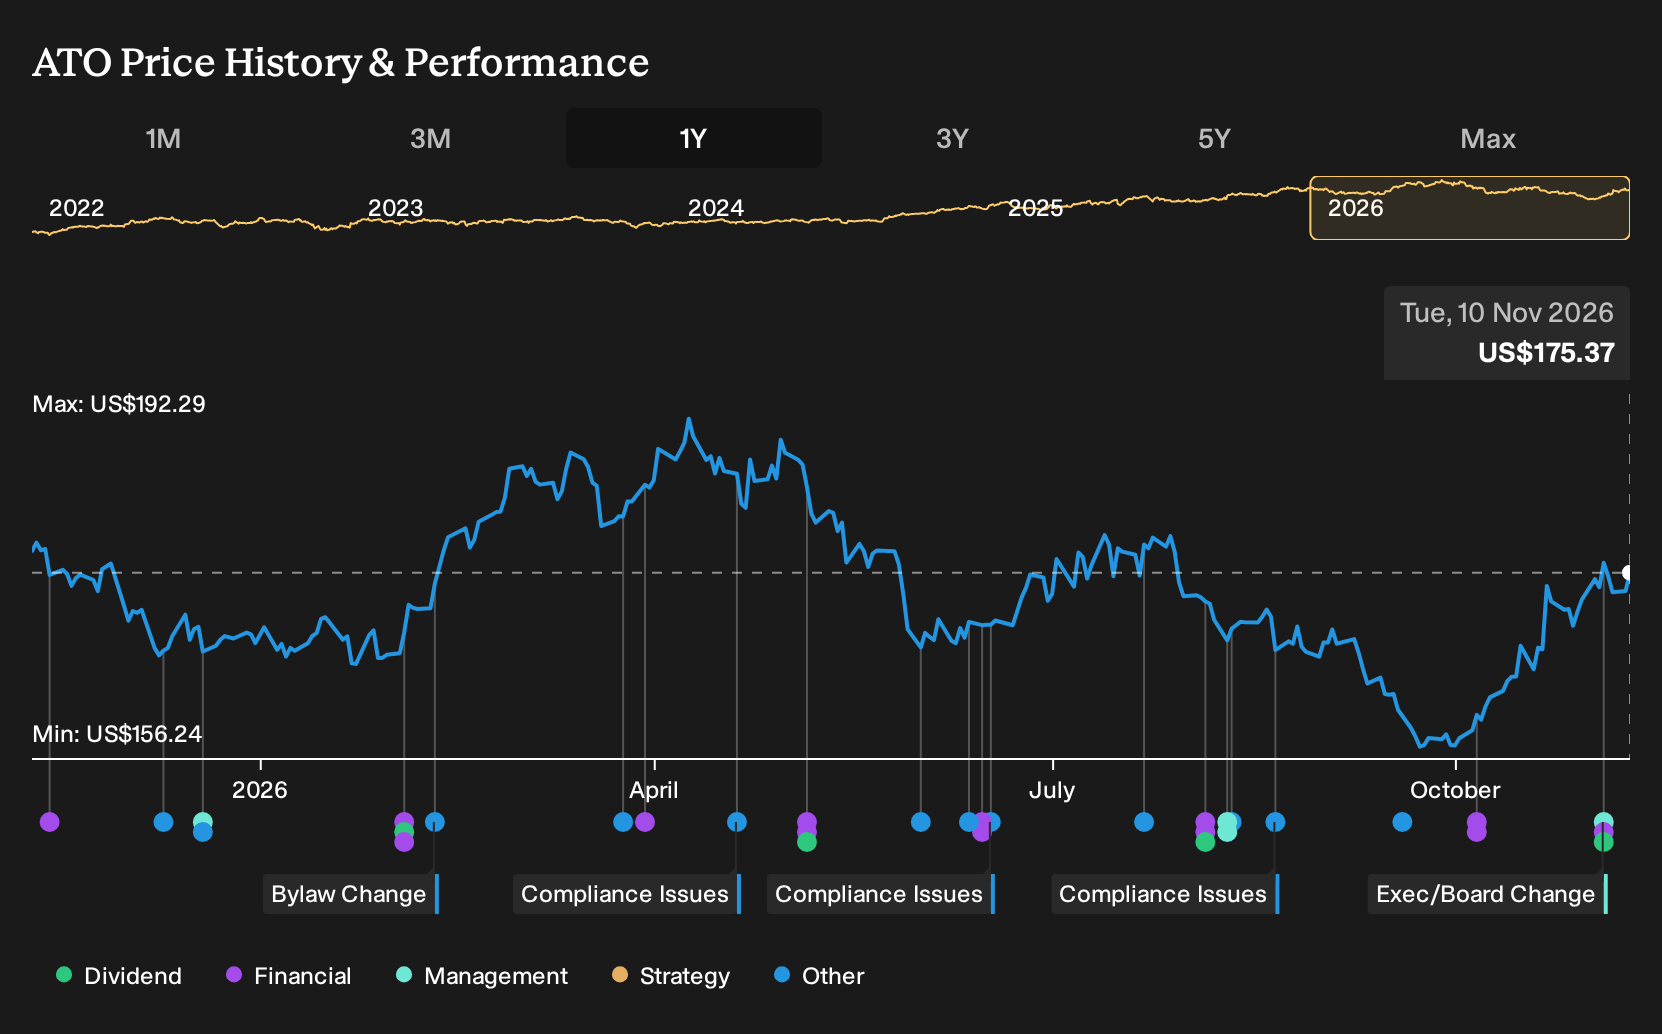
Uncover why Atmos Energy's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Atmos Energy from two Simply Wall St Community contributors span roughly US$135.64 to US$185.55 per share, leaving a wide gap between the lowest and highest views. Those pre news opinions sit alongside fresh catalysts, such as the CEO and Chair roles being combined, which could influence how you weigh governance, earnings guidance and dividend commitments. Investor opinions can vary sharply, so consider several of these alternative viewpoints before deciding how Atmos Energy might fit into your portfolio.
Explore another Atmos Energy fair value estimate, including one that suggests as much as 6% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Atmos Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Atmos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atmos Energy's overall financial health at a glance.
Looking for more investment ideas beyond Atmos Energy?
Once you have formed a view on Atmos Energy, it can help to widen the lens and compare it with other companies that share similar income, value or balance sheet traits. The Simply Wall St Screener lets you do that quickly by narrowing the universe down to businesses that already fit the kind of profile you are interested in.
- If you want potential income plus financial resilience, start with a focus list of companies that combine higher yields with balance sheet strength through the 5 dividend fortresses.
- For investors who care most about paying a fair price for quality, filter for businesses where fundamentals and valuation both look tight by using the 36 high quality undervalued stocks.
- If your priority is capital preservation and smoother returns, narrow your watchlist to companies with lower risk scores and steadier profiles using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com