


When the 10 year Treasury yield hits 5% after a hot inflation print, income investors feel it straight away. Cash suddenly looks tempting. Yet bond payouts reset, while some established businesses keep sending shareholders regular, growing cash every year. That gap creates an opening. This article looks at three high yielding dividend payers from our screen of companies with 3%+ yields that appear well covered and consistent.
The three stocks highlighted here offer a compelling starting point if you want exposure to well covered, stable dividend payers with 3%+ yields. However, if you want the standouts, these 5 dividend aristocrats stocks are the most outstanding.
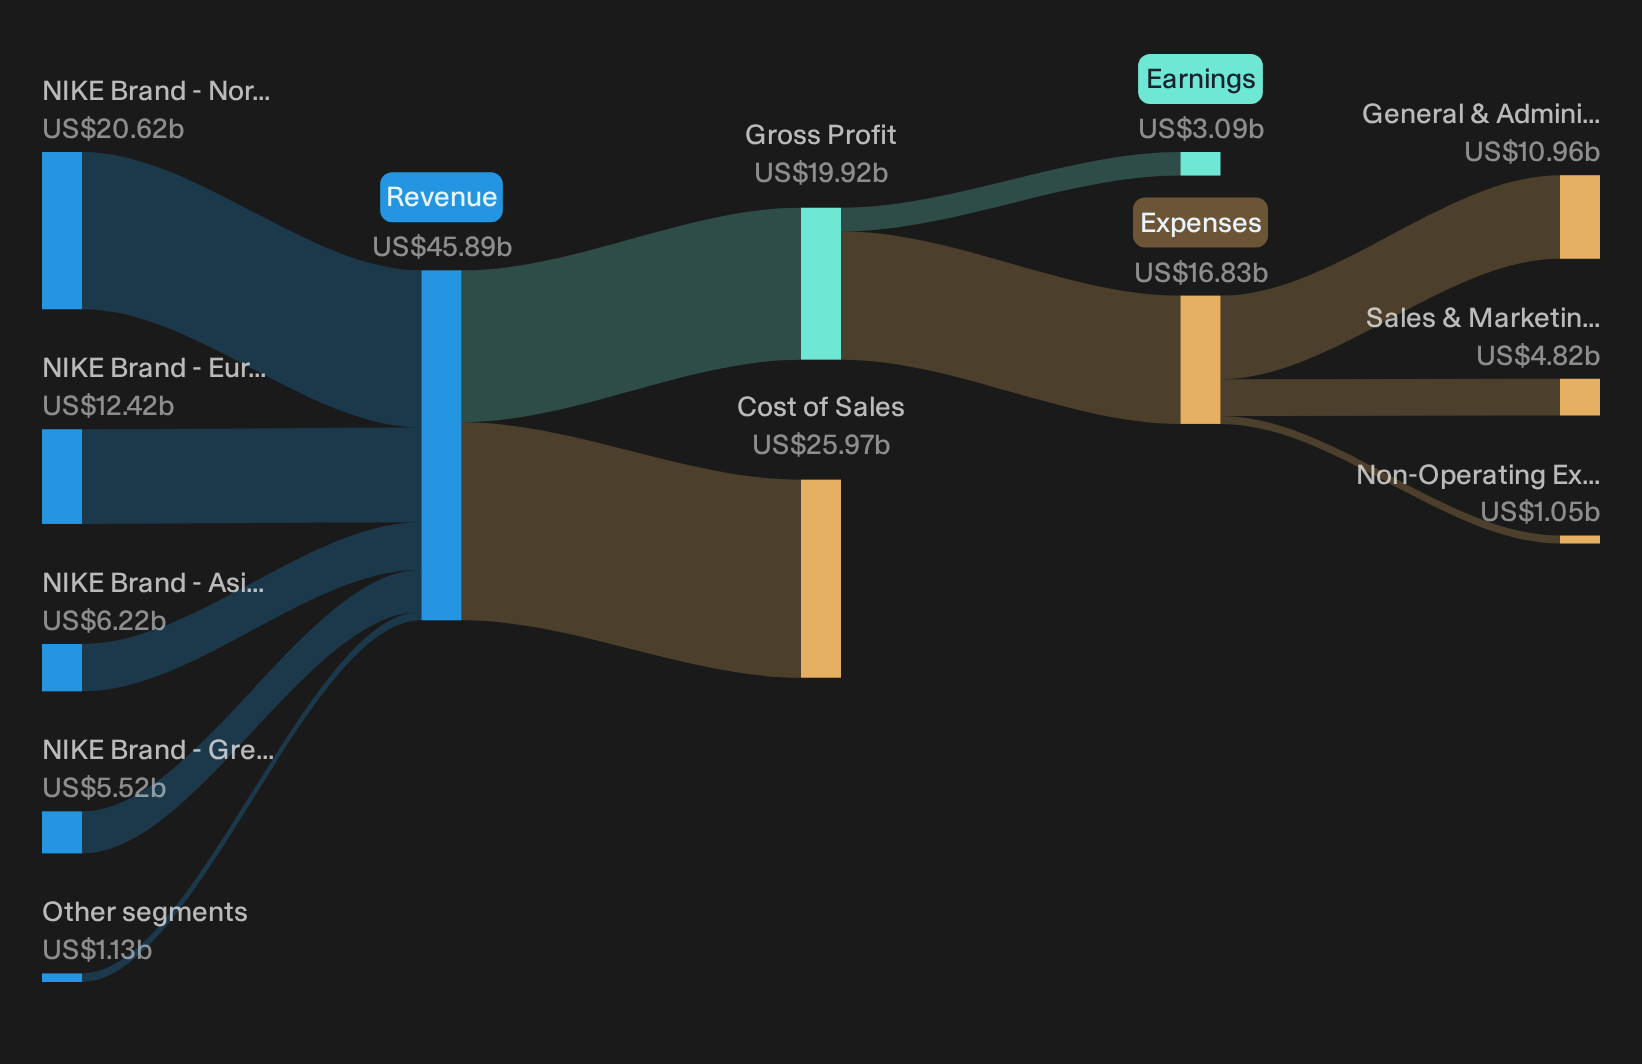
NIKE (NKE)
NIKE is best known for sneakers and sportswear, yet for dividend hunters it is the steady cash coming from that global athletic business that matters most, according to ANTONI0, a Simply Wall St Community investor who wrote a detailed long term turnaround thesis.
"The big risk is that "restored" settles at a 9 to 11% margin, not 13%. If the dividend is defended out of cash, net cash could turn to net debt by around FY29 in the bear case."
What happens if one less visible pressure on NIKE’s cash generation shifts the wrong way will decide how secure that generous yield really feels.
If you want to see how that pressure, margin risk and future cash returns could interact, read the full narrative for NIKE for information on where NIKE’s story could accelerate next.
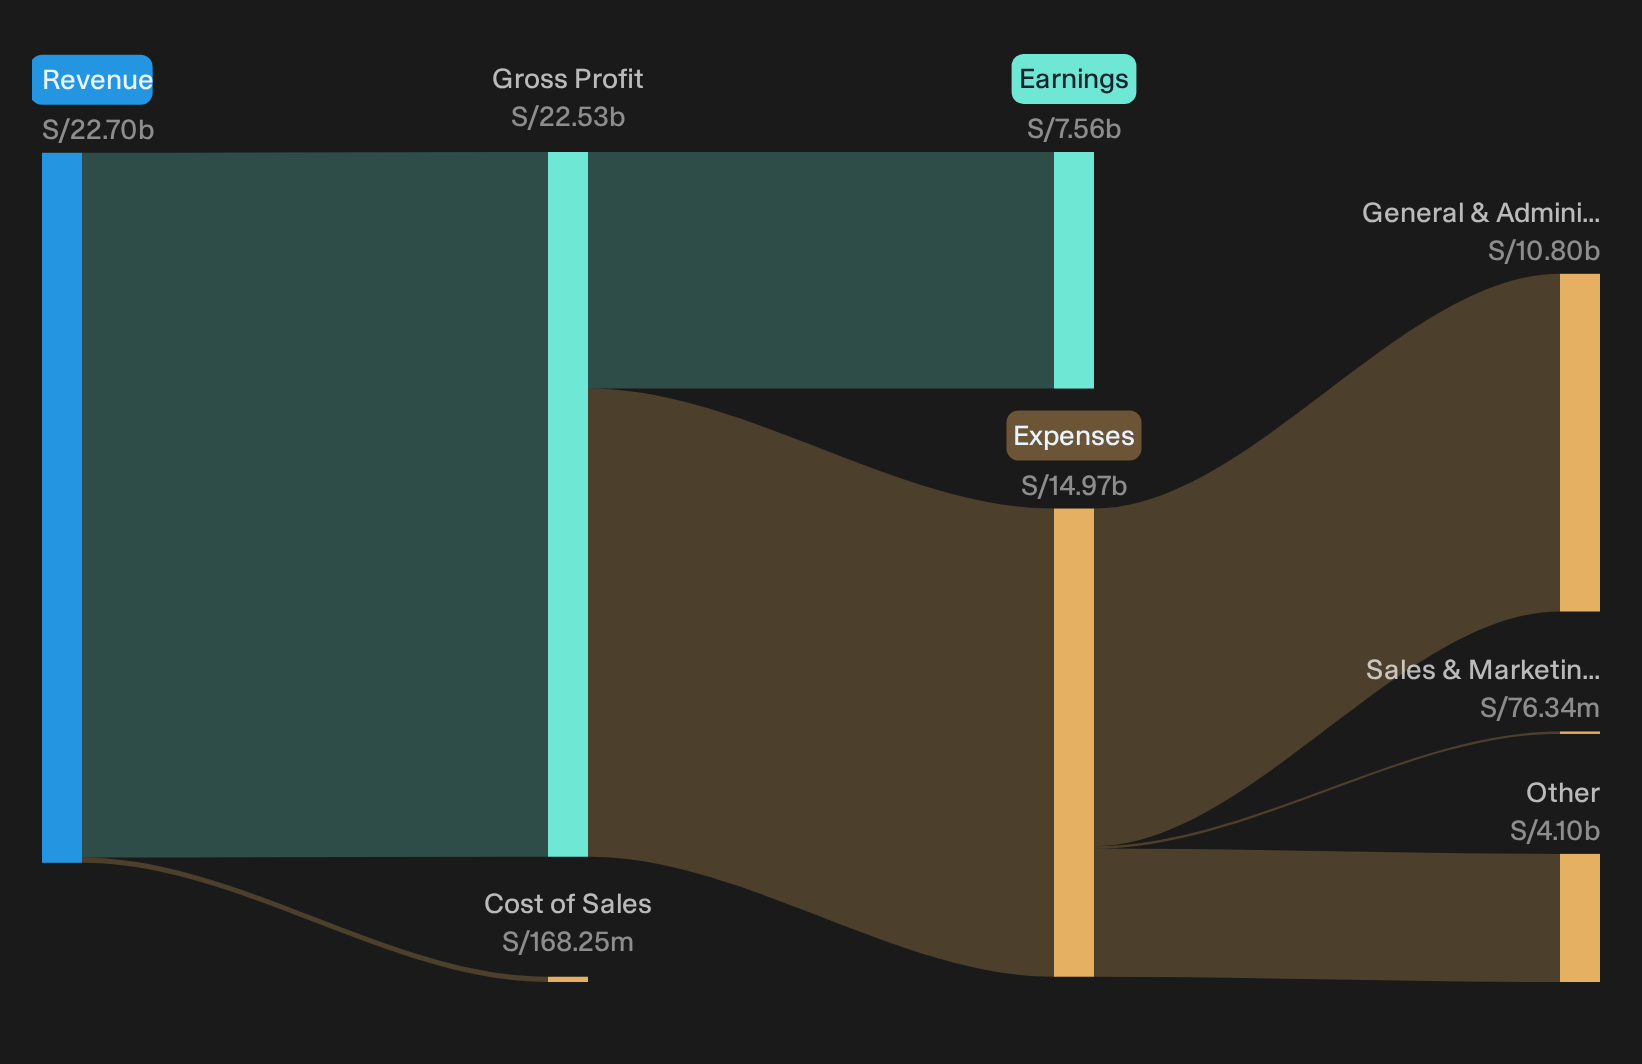
Credicorp (BAP)
Credicorp runs a broad financial services group across Peru and neighboring markets. It is the Universal Banking arm, with its steady deposits, loans and transaction services, that really aligns the stock with the Dividend Powerhouses theme according to the analyst consensus Narrative on Simply Wall St.
Credicorp Ltd. is a Latin American financial group spanning universal banking, insurance, pensions, microfinance and investment services. Its recurring retail and corporate banking earnings support a 3%+ yield, and the business is now valued by the market at about US$28.2b.
"Expansion of Credicorp’s digital financial services like Yape is now tied to a much larger base of more than 16 million monthly active users who transact frequently and already contribute close to 10% of risk adjusted revenues. Further product roll out and higher revenue per user could continue to lift fee income and earnings."
What happens if one unresolved pressure on credit quality moves in the wrong direction will decide how dependable that high payout really feels.
That credit risk cut both ways, and the full narrative for Credicorp lays out how digital traction, payout policy and future capital needs could interact if conditions accelerate rather than stall.
Global Ship Lease (GSL)
Global Ship Lease runs a containership leasing platform that owns 71 mid sized and smaller vessels and charters them out on fixed rate contracts, creating the kind of recurring cash flow income investors look for in a 3%+ dividend payer, and the stock is valued at about US$1.5b.
For income investors, Global Ship Lease matters because its fixed rate vessel contracts link directly to recurring cash that can support regular dividends, and the analyst consensus Narrative on Simply Wall St highlights how that visibility interacts with a strengthening balance sheet.
"The company’s contracted revenue base has expanded to more than US$3.2b with multi year cover, while leverage has fallen sharply and credit ratings remain supportive."
What happens if one less visible pressure on future charter rates moves in the wrong direction will decide how firm that dividend stream really feels.
When that charter risk really starts to bite or ease, the full narrative for Global Ship Lease shows how Global Ship Lease’s contracted cash flow could keep accelerating or stall abruptly.

Curious About What You Might Be Missing?
Fresh ideas move first. Breakout stories, new momentum and stocks flying under the radar for now rarely stay quiet for long. Do not get caught reacting late, act now.
- Spot income workhorses before everyone else by scanning a curated 5 dividend fortresses that focuses on payouts investors may want to lock in while yields are still attractive.
- Back tomorrow’s infrastructure backbone by reviewing the hand picked 41 power grid technology and infrastructure stocks built around companies supplying the hardware behind energy transition and grid resilience while it still feels under followed.
- Ride the build out around AI by checking the focused 53 AI infrastructure stocks that zeroes in on businesses powering data centers, chips and networking before capital chases them aggressively.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com