


- Paramount Resources reported third quarter 2026 revenue of C$257.1 million and a net loss of C$387.2 million, alongside a confirmed C$0.05 per share dividend for November.
- The combination of higher quarterly and year to date revenue with sizable losses and continued cash payouts highlights the pressure on profitability and capital allocation discipline at Paramount Resources.
- Next, the focus turns to how this sharp swing to losses at Paramount Resources could reshape its long project runway investment narrative.
Paramount Resources Investment Narrative Recap
To own Paramount Resources, you need to be comfortable with a story built on a long inventory of Canadian oil and gas projects and a manufacturing style development model at Willesden Green and Sinclair. The analyst consensus Narrative on Simply Wall St views this as key to more predictable volumes and costs. The sharp move from prior profitability to a quarterly loss of C$387.2 million raises questions about how smoothly that build out is running.
The near term swing factor is whether management can keep capital programs on time and on budget while limiting further strain on free cash flow. The biggest risk right now is that this period of heavy investment and reported losses overlaps with weaker commodity pricing or new regulatory headwinds in Canada. This could pressure balance sheet flexibility and curb future room for shareholder payouts.
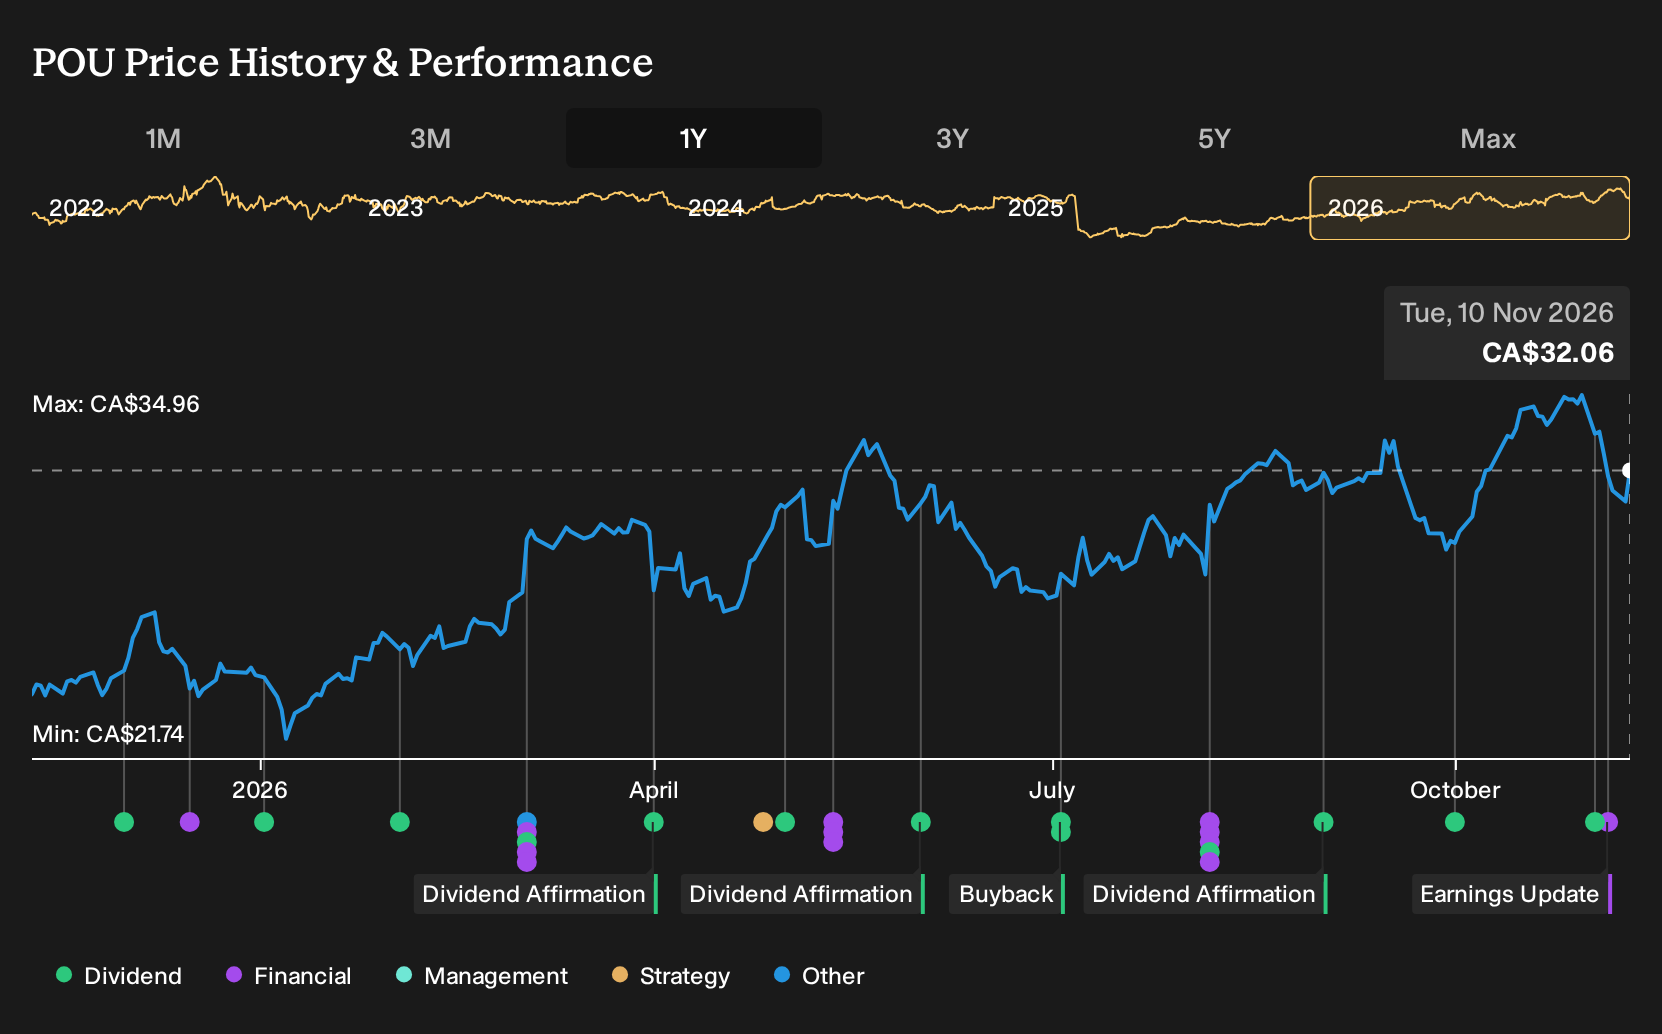
The November dividend affirmation of C$0.05 per share, despite a third quarter loss and a C$265.7 million loss over the first nine months of 2026, is the clearest announcement to focus on here. It ties directly into the existing story of C$3.2b already returned since 2021 and a policy built around regular cash distributions alongside growth spending.
For you as a shareholder, that payout decision sets up a simple monitoring job. Track whether operating cash flow from the Willesden Green, Sinclair and Montney programs can cover both development capital and dividends without leaning too hard on the C$750 million of undrawn credit. If losses persist while capital spending stays high, the sustainability of that C$0.05 monthly dividend becomes a central risk to watch.
Paramount Resources is framed around analyst expectations that revenues could reach C$1.7b and earnings C$659.5 million by 2029, built on forecast revenue growth of 17.7% a year and a move from earnings today of C$117.3 million to that 2029 consensus, which represents an increase of about C$542 million.
Uncover how Paramount Resources' fair value indicates a 22% potential upside to its current price that could narrow quickly if sentiment turns.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between C$28.88 and C$39.90, which already shows how far opinions on Paramount Resources can stretch, even before the latest loss of C$387.2 million. Treat this as a prompt to weigh fresh earnings, dividend commitments and Canadian regulatory risk against those earlier viewpoints.
Explore 2 other Paramount Resources fair value estimates, including one that suggests as much as 24% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Paramount Resources research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Paramount Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paramount Resources' overall financial health at a glance.
Looking for more investment ideas beyond Paramount Resources?
Once you have formed a view on Paramount Resources, it can help to compare its risk, income profile and balance sheet strength with other companies that fit your style of investing. The Simply Wall St Screener gives you a way to do that quickly without getting lost in noise.
- If capital preservation matters most to you, focus on resilient businesses by scanning a 9 resilient stocks with low risk scores that already pass strict risk filters.
- If income is your priority, look at companies that combine higher yields with staying power through our 3 dividend fortresses to see which payouts might better suit your goals.
- If you prefer strong financial foundations before anything else, build a shortlist from the list of solid balance sheet and fundamentals (5 results) and compare their metrics against Paramount Resources.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com