


MercadoLibre (MELI) just posted Q3 2026 results that combined strong revenue of US$10.75b with thinner profitability, and the stock has slipped as investors reassess the trade off between expansion and margins.
MercadoLibre’s share price has come under pressure, with a 7 day share price return of down 10.34% and a 30 day move of down 21.15% that extends the slide since Q3 results as investors focus on thinner margins and higher credit risk.
At the latest share price of US$1,490.24, the year to date share price return is down 24.50%, while the 1 year total shareholder return of down 29.02% contrasts with a modest 3 year total shareholder return of up 4.18%. This signals that near term momentum is fading even though long term holders are only slightly ahead overall.
Spot fresh ideas alongside MercadoLibre’s pullback by scanning our hand picked 20 high quality undiscovered gems with strong fundamentals that have not yet hit the mainstream.After MercadoLibre’s sharp pullback and a wide gap between the current US$1,490 price and bullish fair value models, the real puzzle is where a reasonable valuation range actually lands now.
Most Popular Narrative: 38% Undervalued
Against MercadoLibre’s last close of $1,490, the most followed narrative on Simply Wall St works off a fair value around $2,395 and a discount rate of roughly 11.45%, which puts the spotlight firmly on how much of today’s rapid expansion will ultimately turn into cash that stays with shareholders.
Under my modeled revenue path, a $1,530 share price can be reproduced if MercadoLibre's owner-cash-flow margin improves from an illustrative starting level near 3.2% to approximately 5.1% over the next decade. My central case assumes 8.5%.
See why 159 investors see MercadoLibre as 38% undervalued.
Result: Fair Value of $2,395 (UNDERVALUED)
Still, the MercadoLibre story can break if credit losses start to erode those lending economics, or if heavy shipping and fulfillment spend keeps crushing operating margins.
Find out about the key risks to this MercadoLibre narrative.
Another View: MercadoLibre Through The P/E Lens
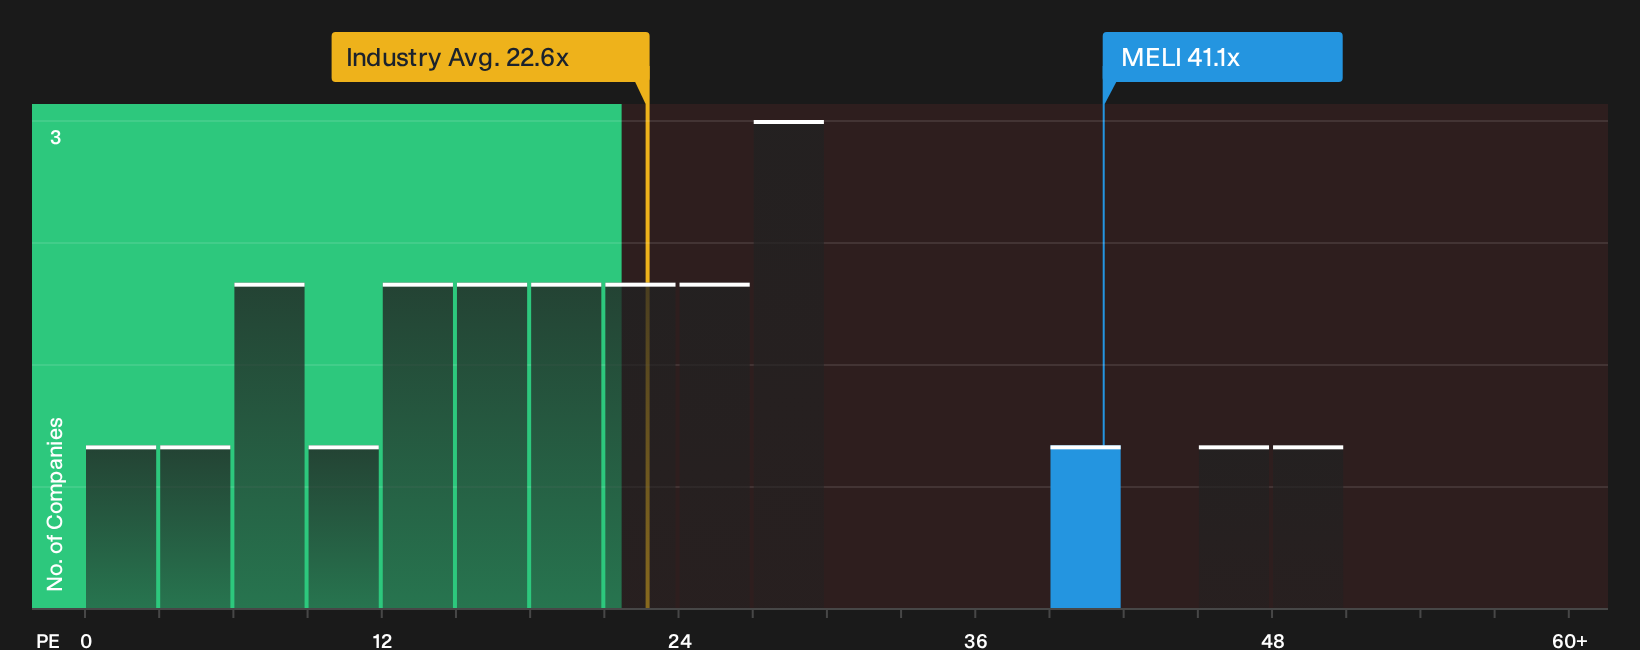
The DCF work around MercadoLibre paints one picture of value. A simple earnings multiple tells a tougher story. At roughly 40x earnings, the stock trades well above the North American Multiline Retail group near 22.6x and above its own fair ratio of 36.4x, which raises the risk that even strong execution does not easily translate into a bargain for new buyers.
That kind of premium can reflect belief in future profit expansion, or it can highlight how much good news is already in the quote. The real question is whether you think the business can grow into this multiple before the market pulls the ratio closer to that fair level.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the recent margin worries and the long term MercadoLibre story is normal, so move quickly, review the data for yourself, and weigh both sides by starting with 3 key rewards and 2 important warning signs
Looking for more MercadoLibre style investment ideas?
Do not stop your work at MercadoLibre alone. Fresh opportunities constantly appear, and casting a wider net now can influence long term outcomes.
- Target resilient compounding by scanning a 36 high quality undervalued stocks that couples quality fundamentals with prices that still sit below intrinsic estimates.
- Prioritise peace of mind with a 30 resilient stocks with low risk scores that filters for stronger balance sheets and lower overall business risk scores.
- Hunt for early stage potential through a carefully curated 9 elite penny stocks with strong financials that screens for solid financials rather than hype.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com