


Pet Valu Holdings (TSX:PET) just reported higher third quarter and year to date earnings and completed a share buyback of 4.11% of its stock, a combination that gives investors fresh numbers to reassess.
At a share price of CA$23.15, Pet Valu Holdings has seen a sharp shift in sentiment, with a 30 day share price return of 23.93% and a 90 day gain of 14.77%. However, the year to date share price is still down 16.55% and the 1 year total shareholder return has declined 16.92%. This suggests that recent earnings and the completed buyback are being interpreted as fresh momentum following a weaker stretch.
Scan how Pet Valu Holdings compares to other retailers showing fresh momentum and earnings support by reviewing our curated list of 5 high quality undervalued stocks.
Pet Valu Holdings has rallied hard off the recent results, yet the share price still trails both analyst targets and intrinsic estimates by a wide margin. Where does a fair entry actually line up in that spread?
Most Popular Narrative: 5% Undervalued
On the analyst consensus Narrative on Simply Wall St, Pet Valu Holdings screens as modestly undervalued, with a fair value of CA$24.40 against the latest close at CA$23.15. This frames the recent rally as only a partial catch up to intrinsic estimates.
The rapid rollout and enhancement of Pet Valu's premium culinary pet food experience taps into ongoing growth in pet humanization and premiumization, enabling higher spending by affluent, frequent in store customers and supporting sustained revenue and margin expansion.
Upgrades to digital properties, rising loyalty program penetration (reaching nearly 90% of sales), and investments in AutoShip subscriptions strengthen customer engagement and repeat purchases. This drives increases in average basket size and lifetime value, thus enhancing top line growth and supporting profitability.
See why 9 investors see Pet Valu Holdings as 5% undervalued.
Result: Fair Value of CA$24.40 (UNDERVALUED)
Still, Pet Valu Holdings depends heavily on the Canadian market and faces rising online competition. Weaker consumer demand or digital share loss could quickly challenge this upbeat narrative.
Find out about the key risks to this Pet Valu Holdings narrative.
Another View: What Pet Valu’s P/E Says
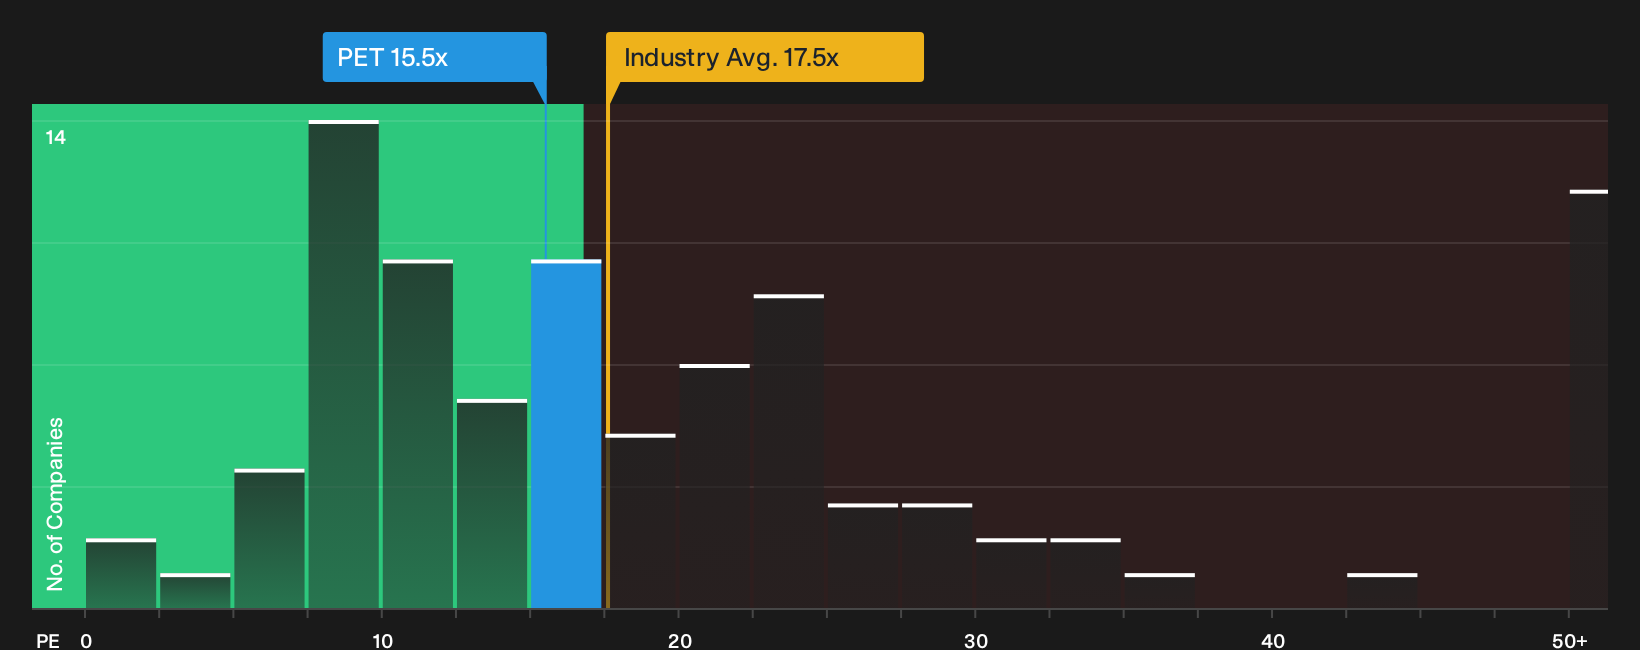
On multiples, Pet Valu Holdings trades on a P/E of 15.5x, which is very close to its fair ratio of 15.3x. The stock is cheaper than the North American Specialty Retail group at 17.5x and well below its peer average of 47.5x. This points to less multiple pressure but also less obvious mispricing. If the market edges closer to that fair ratio, this may be closer to fully valued than the DCF work suggests, or it may simply be a pause before sentiment shifts again.
For a cleaner picture of how this pricing compares with the wider market, take a look at our breakdown using earnings ratios, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data, or a clear setup taking shape? If you want to move fast and think for yourself, consider both sides of the story by checking the 2 key rewards and 1 important warning sign.
Looking for more Pet Valu investment ideas?
Do not stop your research with Pet Valu Holdings alone. Broader context often surfaces opportunities you did not expect and flags risks you do not want to ignore.
- Target stability first by scanning a 9 resilient stocks with low risk scores that focuses on businesses with more resilient risk scores and potentially steadier return profiles.
- Hunt for quality at a discount through our 7 high quality undiscovered gems which highlights lesser known companies with stronger fundamentals than their current pricing implies.
- Prioritize financial strength by reviewing a list of solid balance sheet and fundamentals (5 results) so you are not caught off guard by weak balance sheets when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com