


Intercontinental Exchange has delivered strong gains in recent years, and the question now is whether the current share price is adequately grounded in the returns the business earns on the capital it deploys. With the stock moving on product launches, partnerships and its core data and trading platforms, investors are increasingly focused on what the underlying economics really justify.
- Over the past 3 years, Intercontinental Exchange has returned 65.8%, which puts real weight on whether that share price performance lines up with the returns it is generating on its invested capital.
- Recent plans to launch new futures and tokenized products, from European wind output contracts to perpetual futures and tokenized securities, can influence expectations for how efficiently ICE can earn on each incremental dollar it commits to technology, clearing and market infrastructure.
- If you'd rather focus on earnings, this one's for you. See what Intercontinental Exchange's 23.7x P/E says about the price.
The issue now is whether the returns Intercontinental Exchange earns on its capital are strong and durable enough to justify where the stock trades today.
If you are weighing whether Intercontinental Exchange's recent 65.8% three year return is justified by the returns it earns on its capital, a focused stock screen can offer a useful comparison point through 36 high quality undervalued stocks.
Does Intercontinental Exchange Look Pricey on Excess Returns?
The Excess Returns model looks at how much profit Intercontinental Exchange can earn above its estimated cost of equity, then builds a value from those surplus profits and the capital base that supports them. For ICE, the inputs show a book value of $53.58 per share and a stable book value estimate of $56.34 per share. Together, these figures frame how much equity the business is assumed to keep compounding over time.
Stable EPS is set at $8.88 per share against a cost of equity of $4.71 per share, which implies an excess return of $4.18 per share backed by an average return on equity of 15.77%. That spread suggests the model expects ICE to keep earning meaningfully above its required return on capital. However, the Excess Returns projections put Intercontinental Exchange's estimated intrinsic value meaningfully below the current share price of $176.36. Because the planned tokenized securities and perpetual futures platforms could require significant ongoing investment and carry regulatory and execution risk, the premium price may partly reflect optimism that extends beyond these excess return assumptions. Find out what Intercontinental Exchange could be worth using our Excess Returns estimate.
The Intercontinental Exchange Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Intercontinental Exchange pick up where the excess returns puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the stock to be worth significantly more or less than it is today. Instead of giving you just a single figure from a ratio or model, Narratives set out the future that number leans on so you can watch in real time whether Intercontinental Exchange's story is actually matching that script. They live on Simply Wall St's Community page, where you can see how those expectations compare with what the business is currently doing.
Intercontinental Exchange now has two clear stories pinned to it, one seeing room for upside and the other arguing the ceiling is already close.
Bull case: 8% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which rolls together mainstream forecasts on Intercontinental Exchange.
"Intensifying demand for high quality, real time market data and analytics, reflected in record Fixed Income and Data Services recurring revenue and higher guidance for that business…"
Discover why this Narrative puts Intercontinental Exchange at 8% undervalued.
Bear case: 6% overvalued
This angle is set out in the bearish analyst Narrative on Simply Wall St, built around the most cautious forecast set on ICE.
"Although Intercontinental Exchange is seeing record activity in energy and interest rate derivatives tied to rewiring of global energy supply chains and shifting rate expectations, the current spike in volumes may reset if volatility fades…"
Explore why this Narrative puts Intercontinental Exchange at 6% overvalued.
One more Intercontinental Exchange signal that deserves a closer look
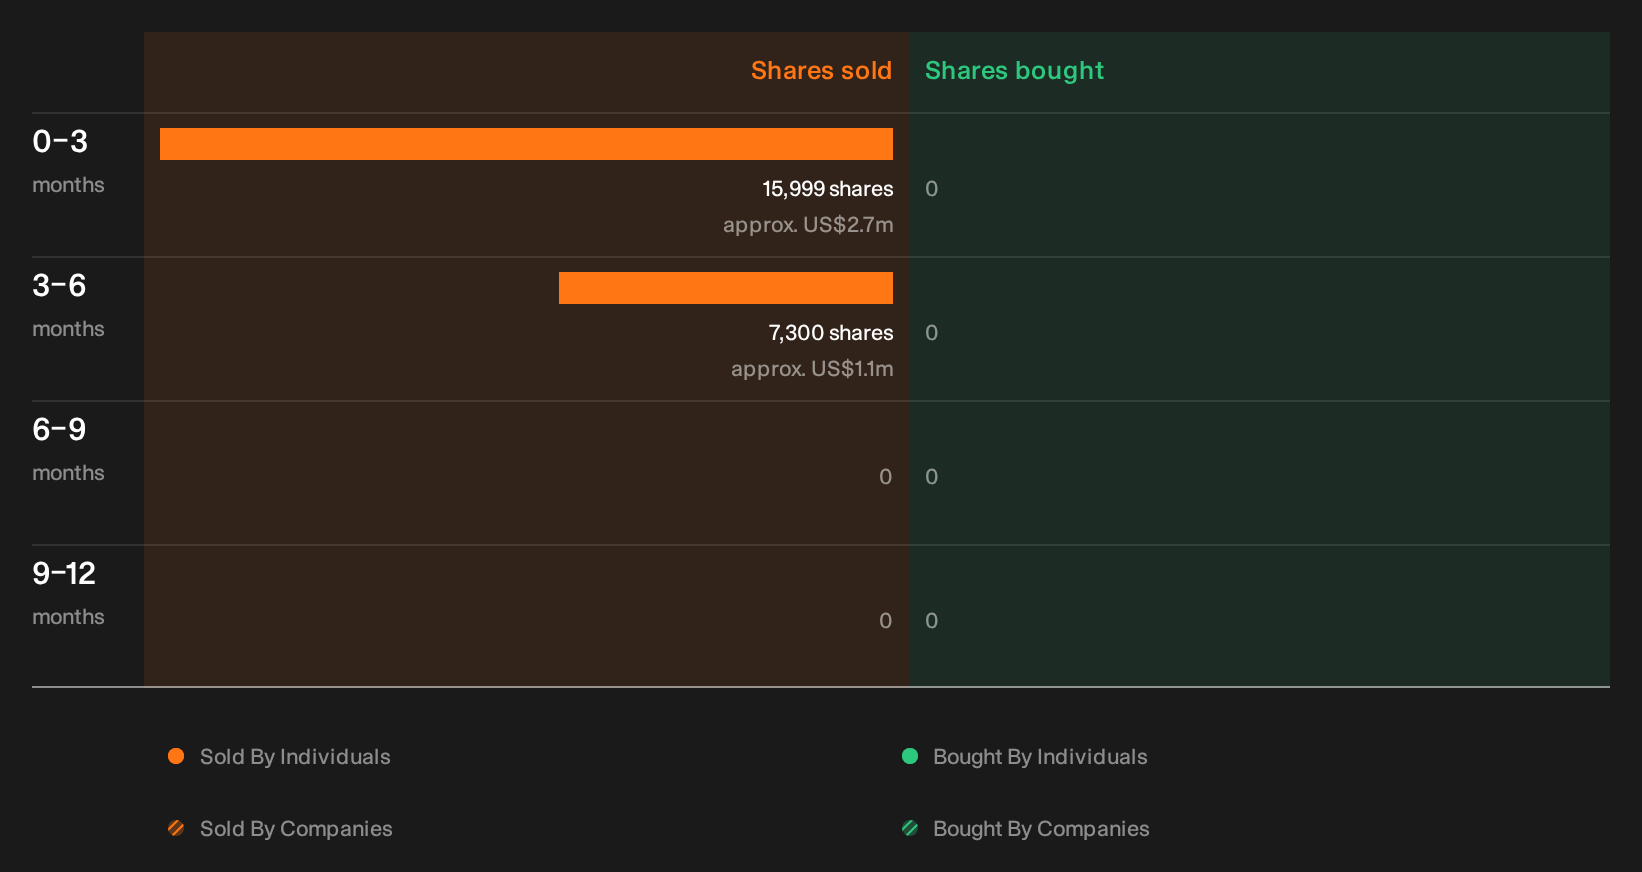
Before you move on from Intercontinental Exchange, it is worth knowing that Simply Wall St's checks have picked up recent selling by people inside the business, with the identities, scale and possible read across left for you to inspect. See the recent insider selling flagged for Intercontinental Exchange.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com