


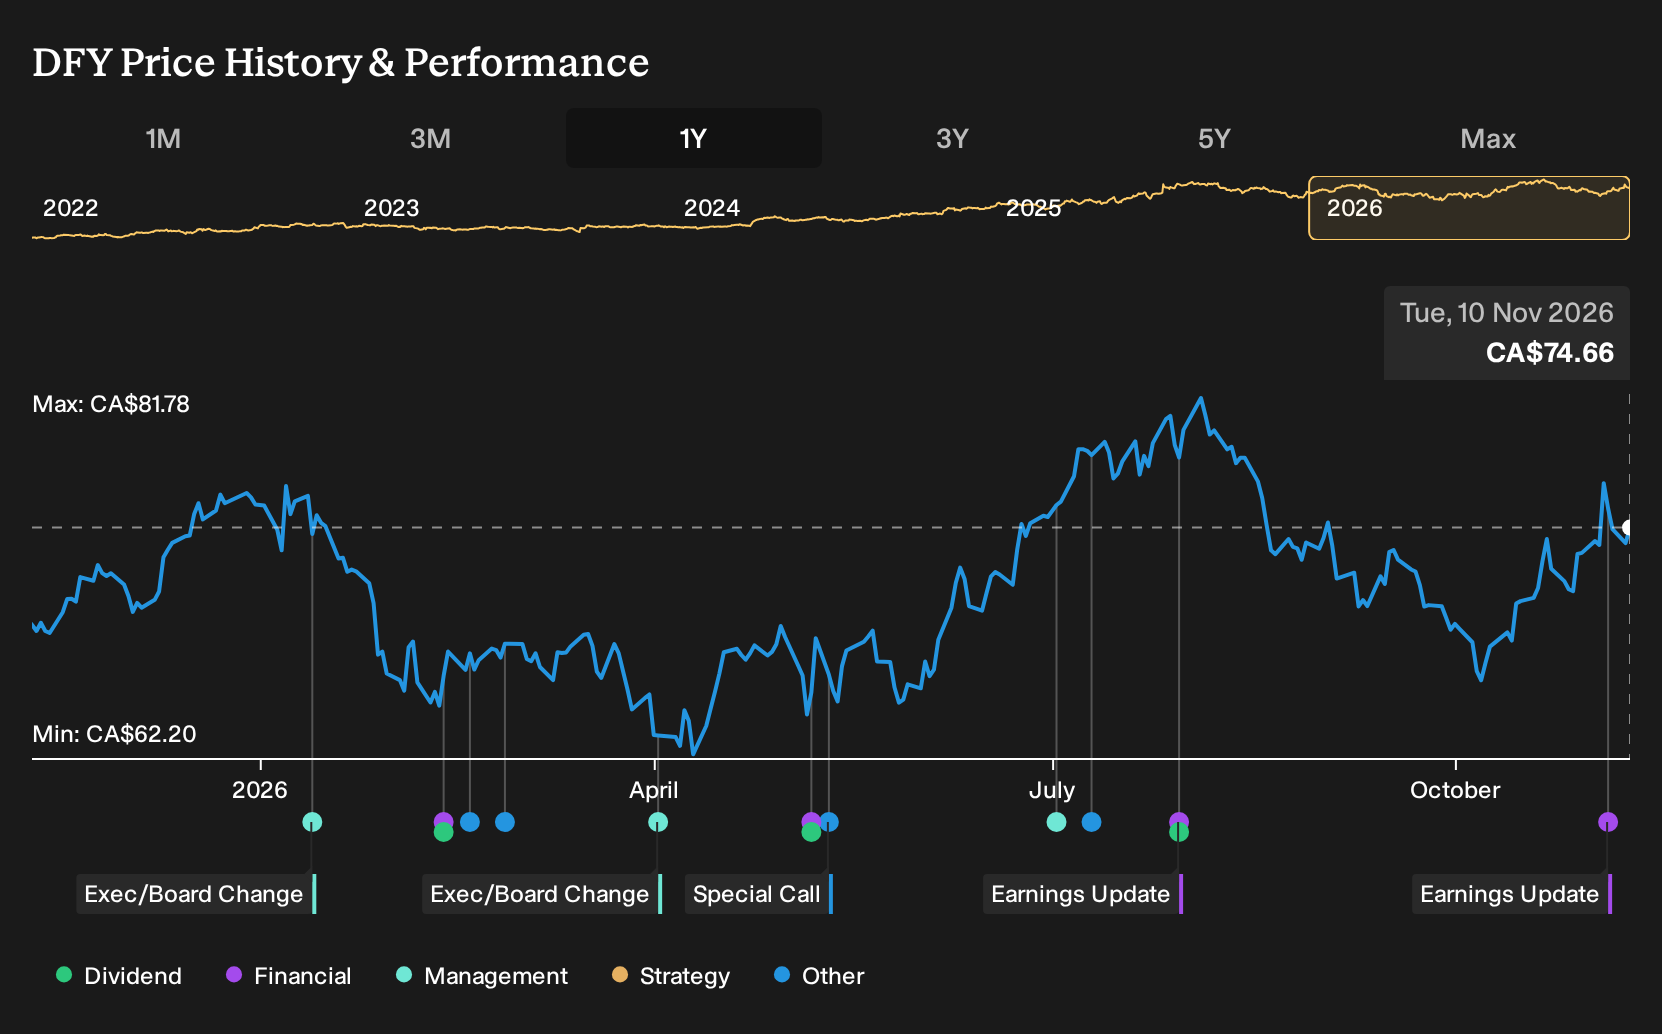
- Definity Financial reported a third quarter 2026 net loss of CA$32.4 million, compared with net income of CA$193.1 million in the same period a year earlier, with basic and diluted loss per share from continuing operations of CA$0.27.
- Over the first nine months of 2026, Definity Financial remained profitable with net income of CA$183.9 million. However, earnings per share from continuing operations were lower than the prior year, highlighting pressure on underwriting results and overall profitability.
- Next, we examine how Definity Financial's swing to a quarterly loss affects the existing investment narrative that has focused on profitability improvements.
Compare Definity Financial's earnings reset with other insurers facing similar profit pressure by scanning the hand picked list of solid balance sheet and fundamentals (5 results) for potential ideas.
Definity Financial Investment Narrative Recap
For an investor to stay with Definity Financial, the belief needs to be that this insurer can turn its larger Canadian P&C footprint and technology spend into steadier underwriting results. The analyst consensus Narrative on Simply Wall St hinges on mid teens operating ROE over time. The third quarter loss, driven by weaker profitability and catastrophe costs, raises questions about how quickly that kind of earnings profile can be built.
The near term swing factor is whether underwriting performance stabilises after the recent weather losses and pressure on margins. The biggest risk is that climate related catastrophes keep hitting loss ratios, making earnings more volatile and keeping ROE closer to current levels rather than where analysts expect it to be in a few years.
The most relevant update alongside this earnings reset is still the Travelers Canada acquisition, which is moving from deal completion into execution. Management reports CA$52 million of run rate cost savings already in place, with a target of CA$125 million. That potential cost base reduction matters a lot more now that margins look squeezed and profit has come under pressure.
For you as a shareholder, the question is how effectively Definity Financial can keep capturing those Travelers synergies while integrating new commercial and specialty lines without further hits to underwriting quality. Execution on technology projects such as Guidewire, Vyne and AI tools can help loss ratios and expense levels, but the benefit needs to show up consistently in reported earnings to offset catastrophe volatility and justify the current P/E premium to peers.
Definity Financial's narrative projects CA$7.7b revenue and CA$744.1 million earnings by 2029. This implies 8.5% yearly revenue growth and an increase in earnings of about CA$276.7 million from CA$467.4 million today.
Uncover why Definity Financial's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly CA$83.64 to CA$122.14, so private investors are treating Definity Financial as anything from modestly discounted to richly priced. Those views were set before the Q3 loss and catastrophe impacts, so you may want to reassess how earnings volatility could reshape that spread.
Explore another Definity Financial fair value estimate, including one that suggests as much as 64% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Definity Financial research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Definity Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Definity Financial's overall financial health at a glance.
Looking for more investment ideas beyond Definity Financial?
Once the Definity Financial story is clear in your mind, it can help to put it alongside other opportunities so you can compare balance sheet strength, income potential and valuation side by side.
- If capital preservation sits high on your list, scan a group of companies that combine resilience with measured risk using the 9 resilient stocks with low risk scores.
- For investors focused on finding quality at a reasonable price, line up businesses that currently screen as attractively priced through the 5 high quality undervalued stocks.
- If you want ideas with cleaner finances and fewer leverage concerns, sort for companies that clear strict balance sheet and fundamentals checks using the list of solid balance sheet and fundamentals (5 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com