


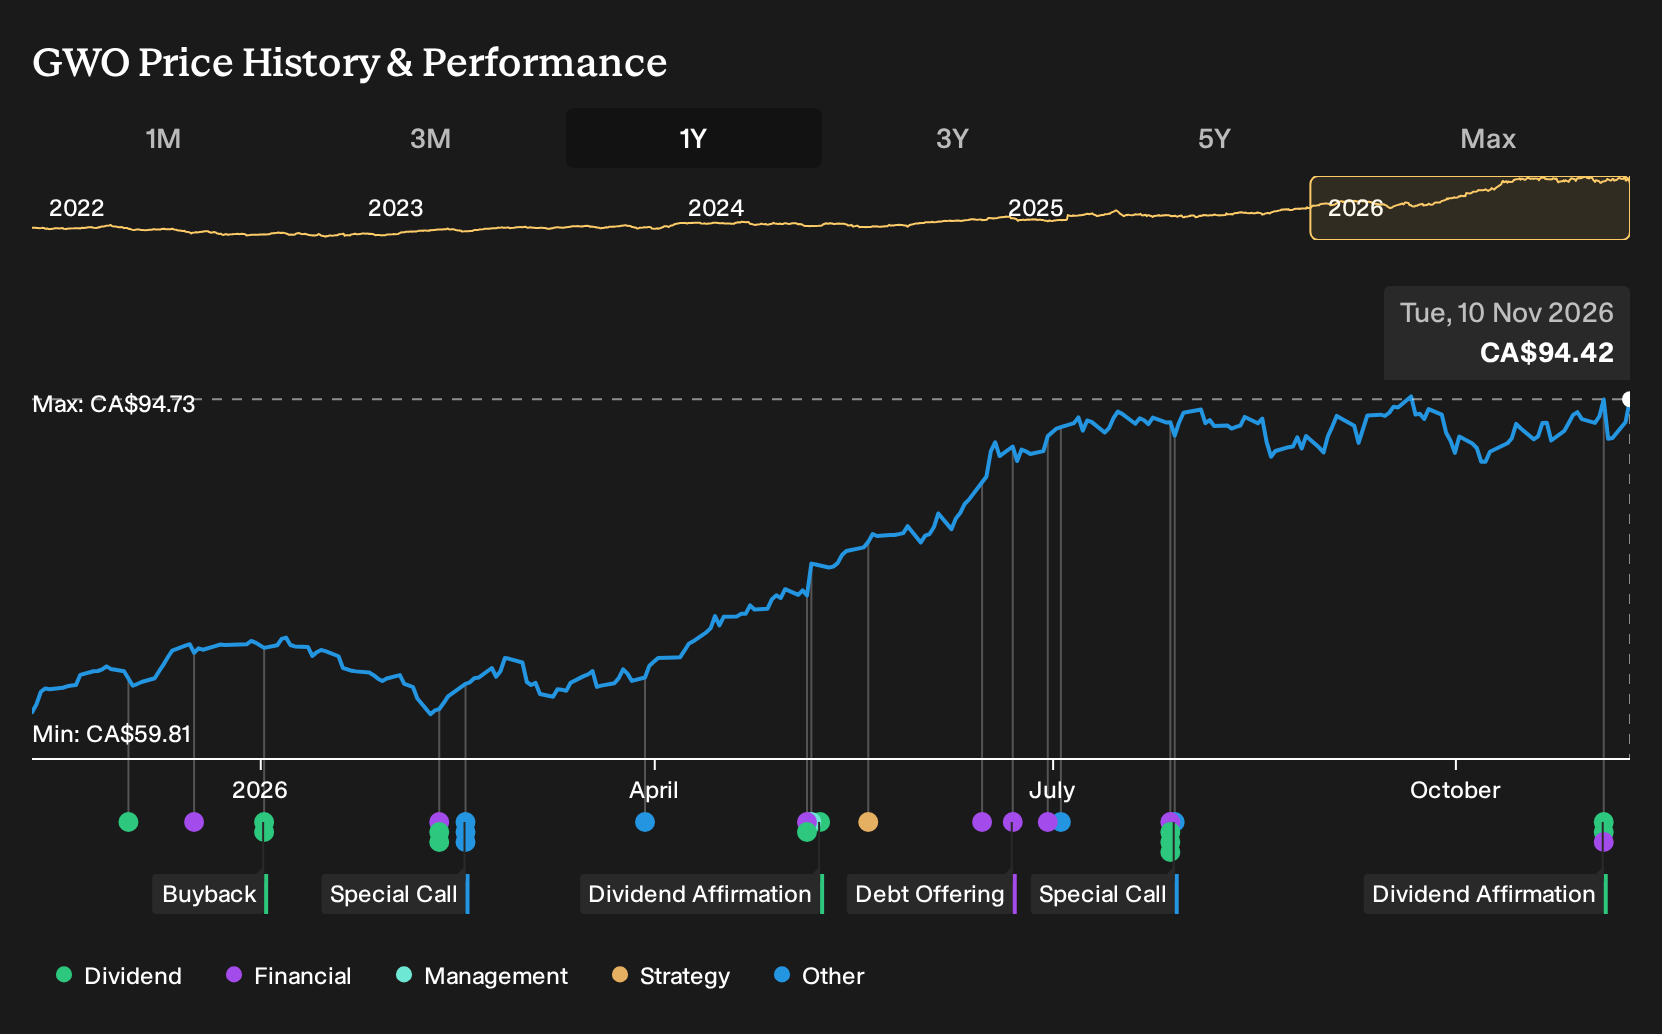
- Great-West Lifeco reported Q3 2026 net income of CA$1,193 million and approved a CA$0.67 quarterly common dividend, alongside a full slate of preferred share dividends including the first payout on its new Series 24 shares.
- The earnings update highlighted Empower as a key profit engine, with the Milliman retirement acquisition lifting participant numbers and assets while supporting higher base earnings and cash generation.
- We will now see how Great-West Lifeco’s investment narrative could be influenced by record base earnings and Empower driven scale benefits.
Compare Great-West Lifeco’s dividend and earnings story with a curated group of resilient income payers and capital compounders using the 3 dividend fortresses.
Great-West Lifeco Investment Narrative Recap
To own Great-West Lifeco, you need to be comfortable with a business that leans heavily on retirement, wealth and fee based earnings, while still carrying traditional insurance exposure. The analyst consensus Narrative on Simply Wall St frames the key short term swing factor as execution at Empower and in Capital and Risk Solutions, with recent record base earnings reinforcing that story rather than changing it.
The biggest near term risk still sits in softer organic flows at Empower and fee compression, alongside pressure in Canadian group disability claims. None of the new Q3 numbers or dividend decisions remove those issues. They simply show the group generating enough profit and cash to keep funding its current capital plan.
The most relevant announcement to this update is the reaffirmed CA$0.67 quarterly common dividend and the detailed preferred share payouts, including the Series 24 schedule. That decision sits on top of Q3 2026 net income of CA$1,193 million and record base earnings, which together give a clearer picture of current capital generation.
For you as a shareholder, that dividend detail ties directly to the catalyst of higher capital light earnings and strong free cash flow highlighted in the analyst consensus Narrative on Simply Wall St. It also highlights a key risk. The stated view that the dividend is not well covered by free cash flow makes future payout decisions more sensitive to any setback in Empower flows, reinsurance demand or Canadian group claims.
Great-West Lifeco's current earnings are CA$4.4b and analysts expect earnings to reach CA$5.3b by 2029, which implies an increase of about CA$0.9b. The same forecasts point to revenues of CA$45.6b by 2029, based on an assumed 7.7% yearly revenue growth rate.
Uncover why Great-West Lifeco's fair value is essentially consistent with its current price.
Exploring Other Perspectives
One alternate view on Great-West Lifeco puts Empower driven upside front and center. The most optimistic analysts were modelling revenue of about CA$46.6b and earnings reaching roughly CA$7.1b by 2029, before this dividend and earnings news. That more upbeat story leans on Empower sustaining very strong profitability, which may or may not hold. Use this as a prompt to compare several narratives rather than rely on a single forecast set.
Explore 2 other Great-West Lifeco fair value estimates, including one that suggests as much as 72% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Great-West Lifeco research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Great-West Lifeco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Great-West Lifeco's overall financial health at a glance.
Looking for more Great-West Lifeco investment ideas?
If the Great-West Lifeco story has sharpened your thinking, use that momentum to size up other opportunities and pressure test your income, quality and risk preferences side by side.
- For investors who want stronger balance sheets and cleaner fundamentals, scan a focused list of solid balance sheet and fundamentals (5 results) that match those criteria.
- If you prefer opportunities where quality and valuation line up, review a curated 5 high quality undervalued stocks that combine robust financials with prices that may not fully reflect them.
- For a broader watchlist of resilient dividend and compounding candidates, check out a hand picked 7 high quality undiscovered gems that often sit off the usual radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com