


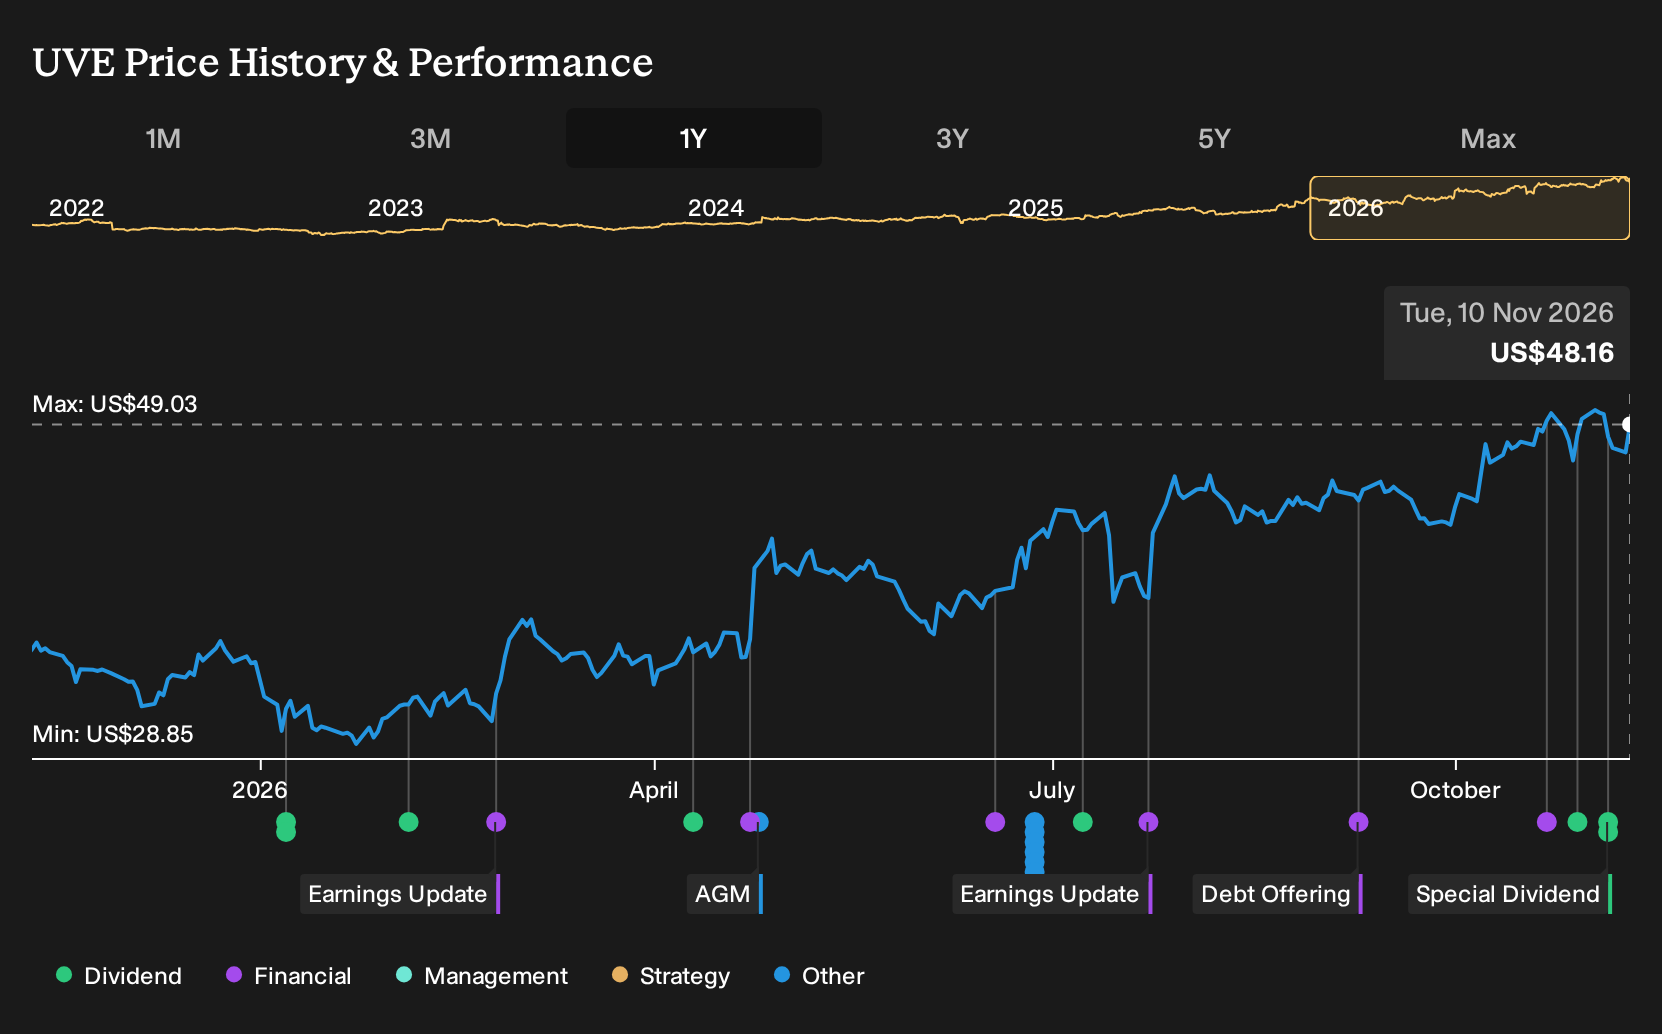
- Universal Insurance Holdings announced a special dividend of US$0.13 per share and affirmed its regular US$0.16 quarterly dividend, both paid on 11 December 2026, while also updating investors on recent share repurchases under its existing buyback program.
- The business combined a one-off cash return with continued quarterly payouts and an expanded US$40 million repurchase authorization, reflecting active capital management alongside efforts to balance shareholder distributions with other uses of cash.
- This article examines how Universal Insurance Holdings' investment narrative is influenced by the expanded buyback authorization alongside these dividend decisions.
Universal Insurance Holdings Investment Narrative Recap
To own Universal Insurance Holdings, you need to believe the business can keep turning solid underwriting and reinsurance execution into resilient cash generation, even while the analyst consensus Narrative on Simply Wall St points to declining revenue and earnings over the next three years. The special and regular dividends do not change that central question. The near term hinges on holding loss and expense ratios in check while growing outside Florida to offset pressure in its core market.
The biggest immediate swing factor remains reinsurance cost and availability, given exposure to US property events and higher claims severity. Elevated ceded premium costs, more competition in Florida and inflation in reconstruction expenses are still front and center. The latest cash returns are meaningful for investors, but they do not materially alter those operational risks.
The most relevant announcement for that backdrop is the expanded US$40 million buyback authorization, following US$18.84 million of repurchases completed since January 2026. That sits alongside the US$0.13 special dividend and the affirmed US$0.16 quarterly payout, both scheduled for 11 December 2026. Together, these moves signal that Universal Insurance Holdings is committing real cash to reduce share count and maintain distributions.
For you as a shareholder, the key question is whether this capital return profile can coexist with the earnings path implied in the analyst consensus Narrative on Simply Wall St. Forecasts there point to revenue and profit contraction and a lower future return on equity. Execution on underwriting quality, reinsurance programs and geographic diversification will likely matter more for the medium term story than any single dividend or buyback headline.
Universal Insurance Holdings' current analyst narrative points to revenues of US$1.6b and earnings of US$147.3 million by 2029, based on an assumed 1.6% yearly revenue decline and an earnings decrease of about US$85.3 million from US$232.6 million today.
Uncover how Universal Insurance Holdings' fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between US$51 and about US$60.9 per share, showing retail opinions can sit almost US$10 apart. When you set those side by side with risks around higher loss ratios, Florida competition and reinsurance dependence, you see why exploring multiple Universal Insurance Holdings viewpoints matters.
Explore another Universal Insurance Holdings fair value estimate, including one that suggests it could be worth just $51.00.
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Insurance Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Insurance Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Insurance Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Universal Insurance Holdings?
If Universal Insurance Holdings has sharpened your focus on risk, income and capital returns, it can be useful to line it up against a wider field of potential opportunities using the Simply Wall St Screener.
- If you want income with resilience, start with companies that combine generous payouts with strong coverage by scanning our 5 dividend fortresses.
- If capital preservation matters most to you, narrow your watchlist to businesses with sturdier finances and lower risk profiles using the 30 resilient stocks with low risk scores.
- If you are hunting for future standouts before the crowd pays attention, broaden your research with our 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com