


- HCI Group reported third quarter 2026 revenue of US$244.91 million and net income of US$83.5 million, with higher basic and diluted earnings per share from continuing operations compared with the same period in 2025.
- The insurer’s push beyond Florida into Northeast and Southeast markets, alongside its technology driven underwriting approach, is reshaping how it spreads catastrophe exposure and sources future premium and fee income.
- This article examines how HCI Group's investment narrative is affected by strong quarterly earnings alongside its ongoing geographic expansion.
Compare HCI Group's earnings momentum with other insurers by reviewing a hand picked set of 30 resilient stocks with low risk scores that prioritize balance sheet strength and disciplined underwriting.
HCI Group Investment Narrative Recap
For HCI Group, the core belief is that a concentrated Florida insurer can keep turning strong underwriting, reinsurance discipline and technology into resilient earnings, while gradually easing its catastrophe exposure through other states. The third quarter numbers, with US$244.91 million in revenue and US$83.5 million in net income, support that operating story rather than changing it.
The near term swing factor is still catastrophe experience against the 2026 to 2027 reinsurance program, followed closely by execution on new Northeast and Southeast books. The biggest risk remains a severe Florida event that stresses reinsurance and pricing. This quarter’s results do not materially reduce that exposure.
The recent earnings release for the third quarter and nine months to September 30, 2026 is the clearest reference point for today’s HCI Group discussion. Over nine months, revenue of US$734.44 million and net income of US$230.7 million, together with basic EPS from continuing operations of US$18.04, show how the current underwriting and reinsurance setup is feeding into profitability.
That update also matters for the analyst consensus Narrative on Simply Wall St, which assumes earnings decline over the next few years even as catalysts like Exzeo, reciprocal exchanges and the catastrophe reinsurance program support the business. The latest results give you fresh inputs to judge whether those expectations and the identified risks still line up with how HCI Group is actually executing.
HCI Group's analyst narrative projects about US$1.1b in revenue and US$205.8 million in earnings by 2029, based on an assumed 5.9% yearly increase in revenue and a forecast earnings decline of US$92 million from current earnings of US$297.8 million.
Uncover why HCI Group's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
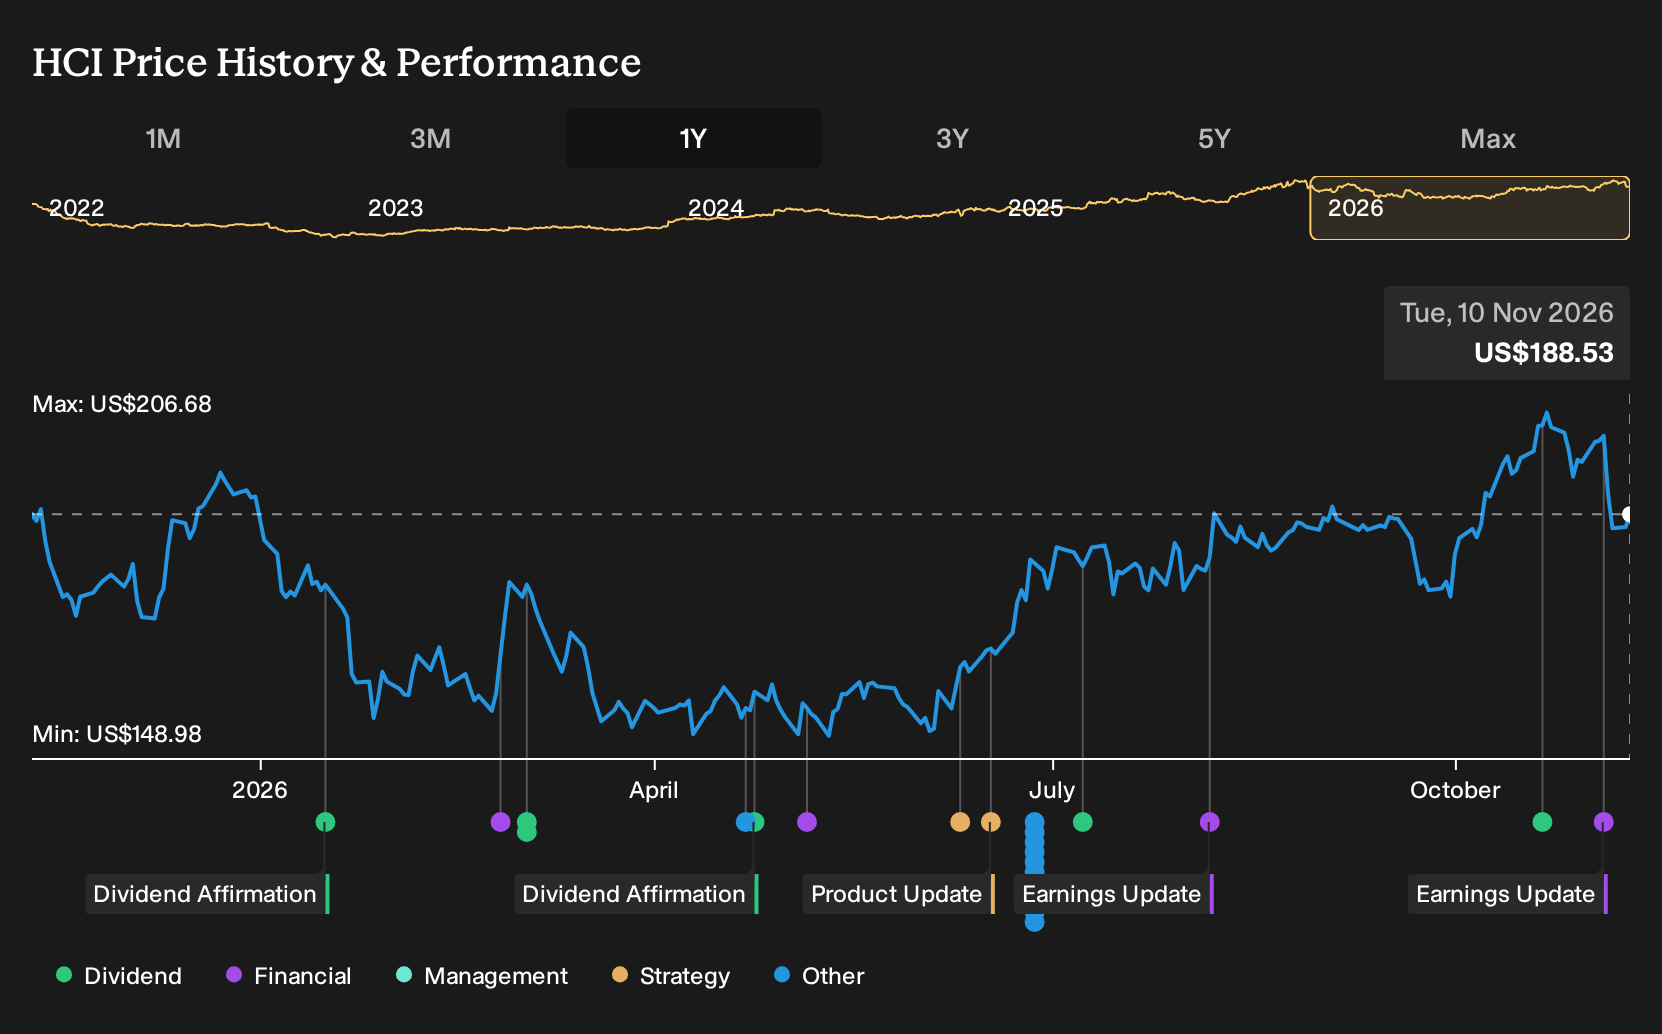
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from about US$241.67 to US$768.14 per share, so private investors are clearly split on HCI Group’s longer term earnings potential. Layer in Florida catastrophe risk and the push into new states, and you are looking at very different future earnings paths.
Explore 2 other HCI Group fair value estimates, including one that suggests it could be worth just $241.67!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your HCI Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for HCI Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HCI Group's overall financial health at a glance.
Looking For More Ideas Beyond HCI Group?
If HCI Group has sharpened your thinking about risk, return and underwriting quality, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- Prioritise financial resilience by focusing on companies that pair modest volatility with strong fundamentals through a 30 resilient stocks with low risk scores that filters for resilience first.
- If value is your anchor, cast a wider net across a 20 high quality undiscovered gems that surfaces quality businesses the market may be overlooking.
- For investors who care most about dependable balance sheets, build out a watchlist from a list of solid balance sheet and fundamentals (24 results) that keeps weak financial structures off the table.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com