


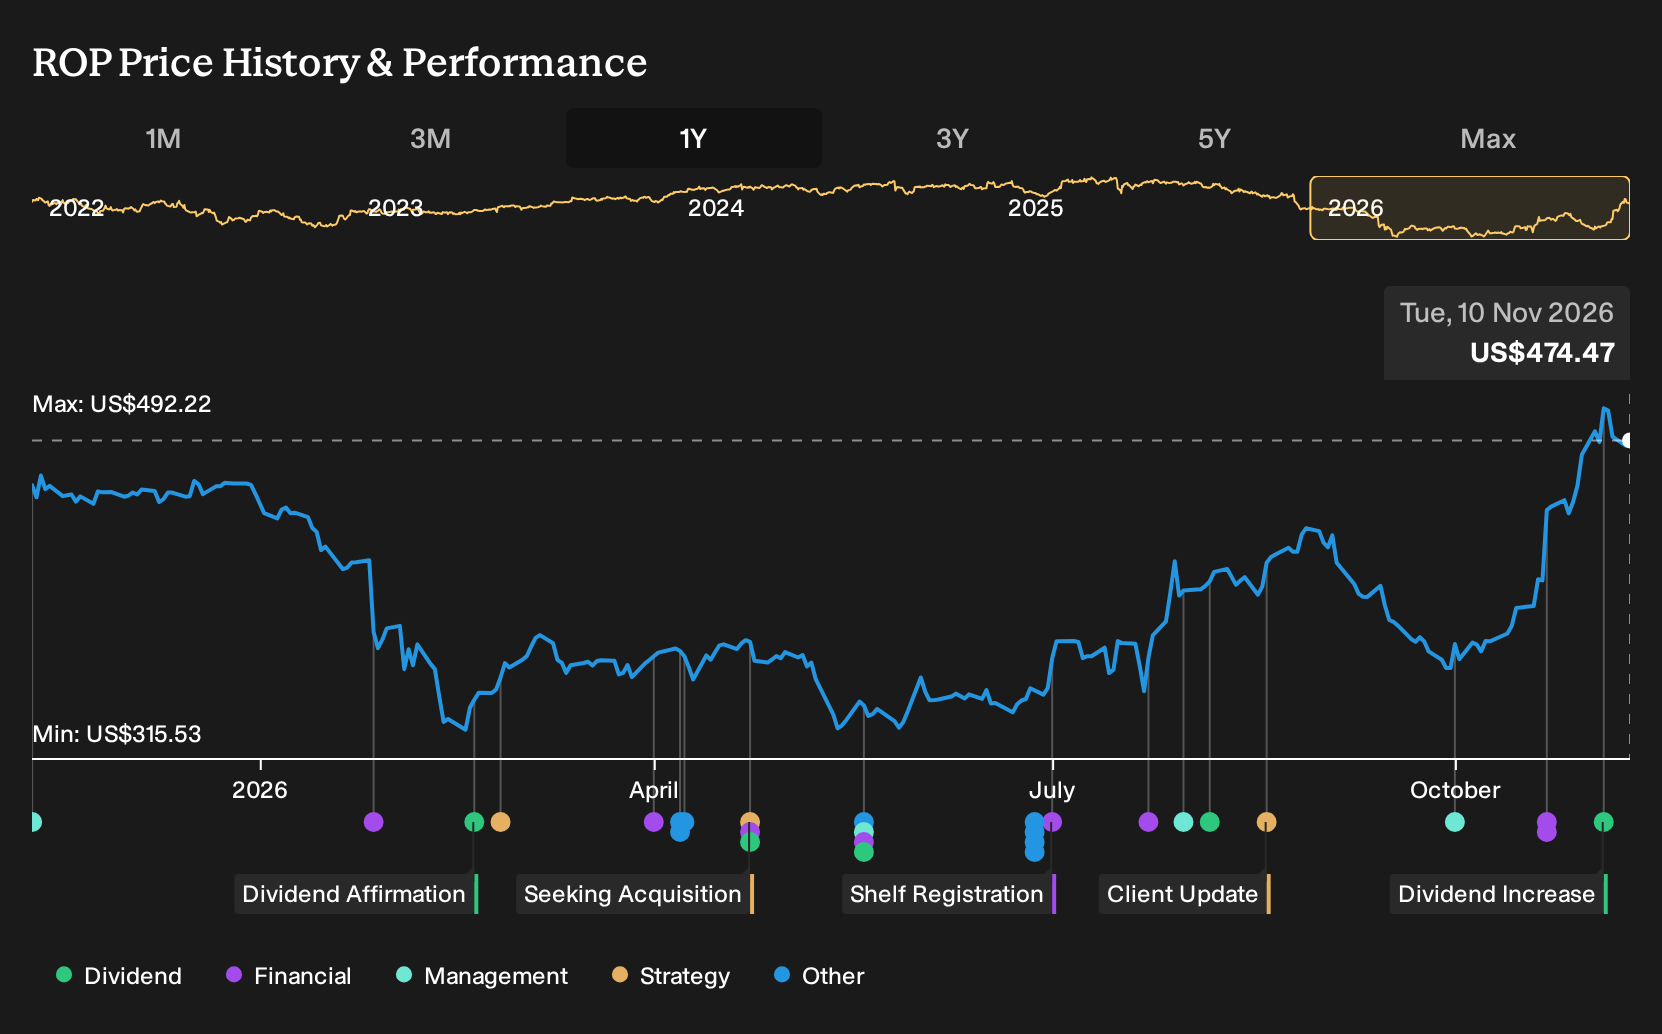
- Roper Technologies has already announced a higher quarterly cash dividend of $1.00 per share, payable on January 19, 2027 to investors on record as of January 4, 2027. This represents a 10% uplift compared with the payout in each quarter of 2026.
- This 10% dividend increase signals that Roper Technologies’ board is comfortable returning more cash even as the group continues to fund vertical software expansion, AI initiatives and ongoing acquisition plans.
- We will now look at how Roper Technologies’ higher quarterly dividend intersects with its cash flow compounding and acquisition driven investment narrative.
Compare Roper Technologies’ dividend move with peers and scan for other resilient cash generators using our hand picked 5 dividend fortresses as a starting watchlist.
Roper Technologies Investment Narrative Recap
To own Roper Technologies, you need to believe its vertical software portfolio can keep compounding cash flow even as it leans on acquisitions and AI driven product development. The analyst consensus Narrative on Simply Wall St already factors in a period where earnings are expected to decline by about 7.7% per year over the next 3 years, so the 10% dividend lift does not materially change the near term story.
The more immediate swing factors still look operational. Execution on more than US$5b of planned software deals, and the health of end markets such as government, utilities and freight, matter more to the outlook than this dividend change. AI driven competitive pressure around pricing and product differentiation also remains a key risk to watch.
Against that backdrop, this higher dividend sits alongside a business that recently reported revenue of US$8.4b, net income of US$2.6b and low 30% free cash flow margins, according to the analyst consensus Narrative on Simply Wall St. Analysts also describe Roper Technologies as trading at a discount to their estimate of future cash flow value, with a P/E of 18.1x compared with a peer average of 37x.
The same analyst set expects earnings to soften and highlights issues such as high debt, significant insider selling in recent months and exposure to one off gains in the last 12 months. In that context, a 10% dividend increase may be read more as a data point on current cash generation than as a solution to risks around M&A execution, AI disruption or slower forecast profit growth.
Roper Technologies’ narrative projects US$10.2b revenue and US$2.1b earnings by 2029. That pathway assumes 6.5% yearly revenue growth and an earnings decline of US$500m from current earnings of US$2.6b to the 2029 consensus level.
Uncover why Roper Technologies' fair value is essentially in line with its current price.
Exploring Other Perspectives
Roper Technologies’ dividend increase looks different if you focus on the most pessimistic analysts. They worry that weaker Neptune results and softer free cash flow momentum could drag earnings toward about US$1.8b by 2029 on roughly 5.4% yearly revenue growth. You can treat that as one lens and compare it with other viewpoints that may adjust once this dividend news is fully absorbed.
Explore 2 other Roper Technologies fair value estimates, including one that suggests it could be worth just $466.79.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Roper Technologies research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Roper Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Roper Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Roper Technologies?
Once you have a view on Roper Technologies, it can help to widen the lens and compare it with other businesses that share similar income, quality or risk traits. The Simply Wall St Screener lets you do exactly that in a structured way rather than chasing headlines.
- If resilience and lower volatility appeal to you, start by scanning a set of 30 resilient stocks with low risk scores that may better match a more defensive approach.
- If strong balance sheets are your priority, focus on companies in our list of solid balance sheet and fundamentals (24 results) to see which ones align with your risk limits.
- If you like finding opportunities before they are widely talked about, shortlist ideas from our 20 high quality undiscovered gems and build a watchlist you can monitor over time.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com