


Hotter CPI data has put inflation and interest rates back in the spotlight, which pulls short term cash and money-market yields into focus for every investor sitting on idle cash. Higher yields can help some stocks earn more on client balances while squeezing others that rely on cheap funding. This article examines how that tension plays out by spotlighting 3 stocks from the U.S. Short-Duration Cash & Money-Market Yield Beneficiaries screener that are directly exposed to this inflation story.
The three stocks below are only a sample, and the full screen surfaced 52 more U.S. Short-Duration Cash & Money-Market Yield Beneficiaries with equally compelling stories around short-term rate exposure and client cash flows that are not covered here. To move beyond the highlights and start identifying your own high-conviction ideas, head straight into the U.S. Short-Duration Cash & Money-Market Yield Beneficiaries screener.
HBT Financial (HBT)
Overview: HBT Financial is a regional bank in Illinois and Eastern Iowa that gathers low cost deposits and provides loans, cash management, and money-market style services to consumers, businesses, and municipal clients.
Operations: HBT Financial generates its entire US$291 million of revenue from community banking activities in the United States, primarily through its community banking segment.
Market Cap: US$1.36b
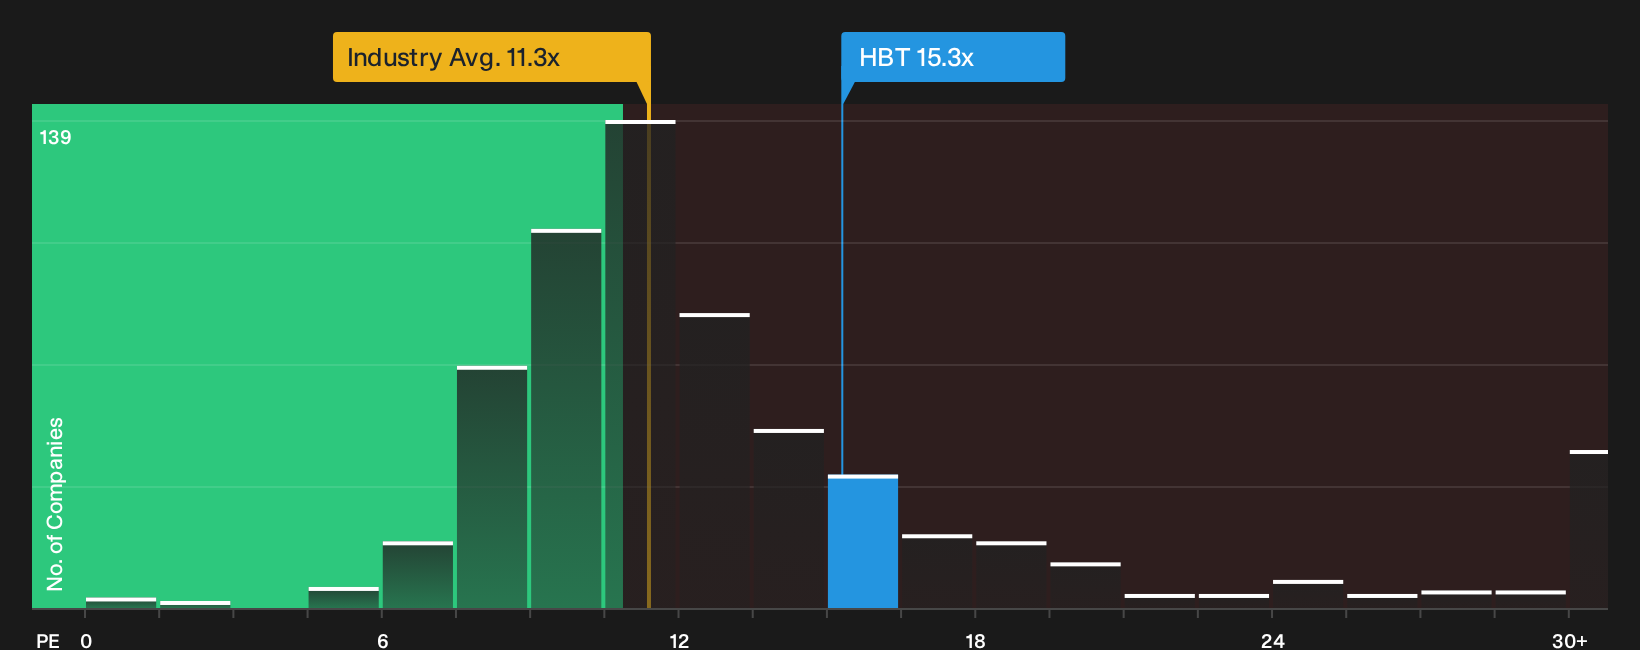
HBT Financial fits this screener because it leans on a large base of non interest bearing and low rate deposits that can earn more when short term yields stay firm. The stock trades on a P/E above many regional peers. Some investors may still see room for that premium to hold or widen depending on how one unseen pressure plays out.
To see how that pressure could reprice HBT Financial, review the 3 key rewards and 1 important warning sign and judge whether the premium truly matches the story ahead.
Bank of Marin Bancorp (BMRC)
Overview: Bank of Marin Bancorp is a California based lender focused on small and mid sized businesses and real estate investors, using operating deposits and cash management services that tie directly into short duration cash and money market style yields.
Operations: Bank of Marin Bancorp generates about US$65 million in revenue from community banking in the United States, primarily through its core banking segment.
Market Cap: US$460 million
Bank of Marin Bancorp sits squarely in this screener because its commercial deposits and sweep style cash products link directly to what higher short term rates mean for loan yields and securities income. The analyst consensus Narrative on Simply Wall St highlights how management is working to translate that rate backdrop into a more efficient, digitally enabled franchise.
"Ongoing targeted investment in digital infrastructure and technology, including mobile banking and online lending upgrades, positions the bank to drive operational efficiency and improve customer engagement, which should support margin expansion and lower long-term costs."
What may be particularly important from here is how one unresolved cost pressure shapes those future margins that rate sensitive investors monitor.
Those cost trends are exactly where the full narrative for Bank of Marin Bancorp steps in, explaining how Bank of Marin Bancorp could potentially turn rate sensitive pressure into a more efficient earnings engine.

Peapack-Gladstone Financial (PGC)
Overview: Peapack-Gladstone Financial is a New Jersey based private bank and wealth manager focused on deposits, lending, and cash management services.
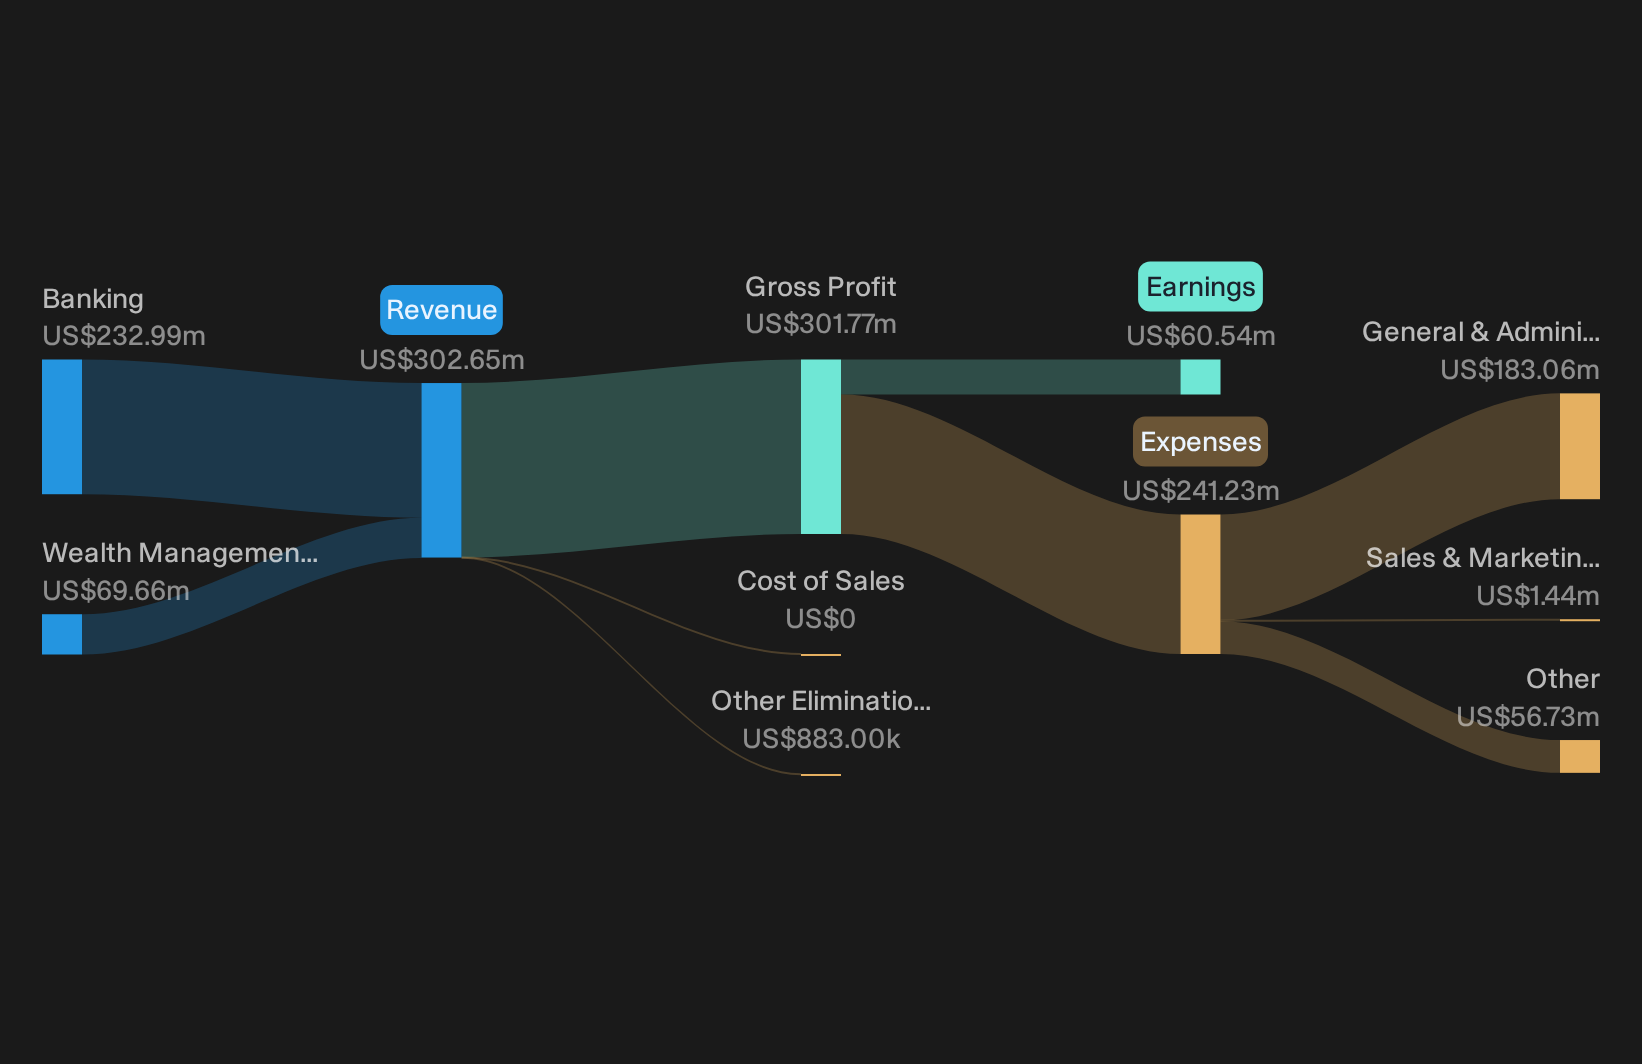
Operations: Peapack-Gladstone Financial generates about US$233 million from Banking and roughly US$70 million from Wealth Management, all within the United States.
Market Cap: US$815 million
Peapack-Gladstone Financial fits this screener because its private banking and wealth management focus means large client cash balances. The analyst consensus Narrative on Simply Wall St highlights how deposit mix can turn higher short term yields into a stronger earnings engine.
"Higher mix of noninterest-bearing deposits, which represented about 49% of quarterly deposit growth and about 2/3 of deposit growth over 12 months, reduces funding costs and supports net interest margin and overall profitability."
What may matter most from here is how one shift in client liquidity preferences shapes the pricing power behind those cash rich relationships.
If that shift accelerates, the full narrative for Peapack-Gladstone Financial shows how Peapack-Gladstone Financial could turn rate sensitive cash into a deeper, fee rich relationship engine.
Seeking Fresh Alternatives Before They Fly
New breakout stories rarely stay under the radar for long. Once momentum is caught by the crowd, ideal entry windows start dropping fast. Scan these fresh sets of ideas and act now.
- Spot stronger balance sheets early by running through the list of solid balance sheet and fundamentals (24 results) and see which businesses might handle shocks better while it matters most.
- Ride structural trends in automation by tracking the 91 robotics and automation stocks where curated operators could benefit if robots quietly take more share before the crowd notices.
- Tag along with potential AI cash generators through the 42 profitable AI stocks that aren't just burning cash and focus on businesses already funding growth from real earnings, not just hype-driven capital raises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com