


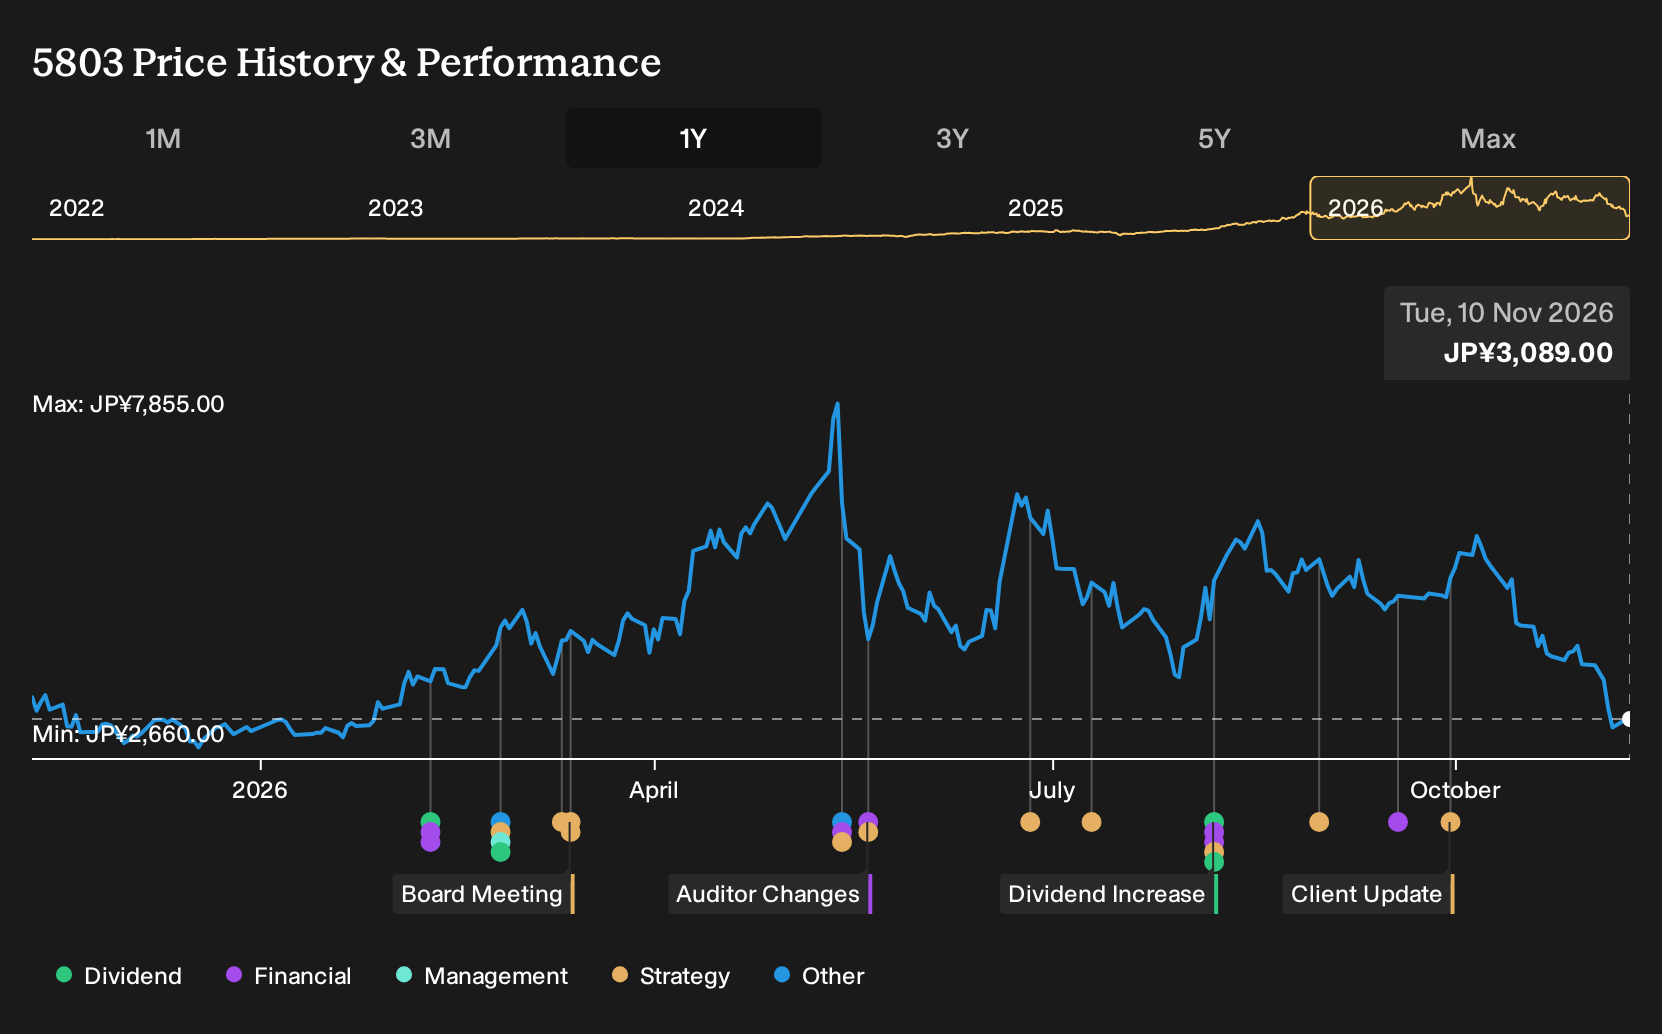
- Fujikura held a board meeting on 10 November 2026 and announced revisions to its consolidated financial forecasts for the fiscal year ending 31 March 2027, alongside decisions on interim dividends and updates to the year end dividend outlook.
- The combination of forecast changes and refreshed dividend plans gives investors a clearer read on Fujikura's current earnings power and capital allocation priorities, particularly how management balances investment needs with cash returns.
- Next, the focus turns to how Fujikura's updated earnings forecast and dividend stance could reshape the investment narrative for long term holders.
Compare how Fujikura’s refreshed forecasts and dividends stack up against other cash returning plays by scanning our 27 dividend fortresses in the same income focused bracket.
What Is Fujikura's Investment Narrative?
To stay invested in Fujikura you need to believe the group can keep turning its mix of telecoms, electronics, automotive, and power infrastructure into high quality earnings without stretching the balance sheet. Recent guidance revisions and dividend updates out of the November 10 board meeting point to management recalibrating expectations and cash returns in light of current demand, pricing, and capital spending needs, rather than chasing a headline payout.
In the short term, the key swing factors are execution on large infrastructure projects, capital intensity in power and telecom cables, and how consistently orders flow through to that 15.7% net margin and a 33% return on equity. The share price has been volatile despite earnings growth and valuation signals, so the fresh forecast and dividend stance mainly help investors judge whether that volatility reflects business risk or just sentiment.
That said, there is a quieter issue sitting behind those strong reported numbers that could matter if ...
There's only one way to know the right time to buy, sell or hold Fujikura. Head to Simply Wall St's company report for the latest analysis of Fujikura's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span from ¥3,587.07 to ¥7,005.38, so you are looking at a wide personal range on Fujikura before the November 10 guidance and dividend news. Treat this as a starting grid of opinions, and then compare it with updated earnings signals and your own expectations.
Explore another Fujikura fair value estimate, including one that suggests there could be up to 127% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fujikura research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fujikura. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fujikura's overall financial health at a glance.
Looking For More Investment Ideas Beyond Fujikura?
If Fujikura has sharpened your focus on earnings quality and dividends, it can be useful to widen the lens and compare it with other listed companies that share some of the same strengths you care about.
- For investors who want income without ignoring quality, scan a curated group of cash generators through the 27 dividend fortresses.
- If capital preservation ranks high on your checklist, review a 19 resilient stocks with low risk scores that screens for resilience and steadier risk profiles.
- When you are hunting for potential future leaders before they are widely followed, check out a 73 high quality undiscovered gems that highlights companies with strong fundamentals but limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com