


TC Energy (TSX:TRP) is back in focus after approving about $2 billion of new pipeline projects in the U.S. Midwest and expanding Canada’s Coastal GasLink system, alongside a higher 2026 EBITDA outlook.
TC Energy’s latest project approvals land on a rising share price, with a 1‑month share price return of 5.02% and a year to date share price gain of 17.10% signaling building momentum. A 1‑year total shareholder return of 25.04% and very large 3‑ and 5‑year total shareholder returns show how recent news and dividend payments have fed into longer term outcomes.
Scan the energy space for other pipeline and infrastructure stocks showing similar momentum to TC Energy with our curated 41 power grid technology and infrastructure stocks.
After TC Energy’s sharp move on project news and a higher 2026 EBITDA outlook, the real tension is clear: does fair value sit closer to the current CA$89.99 price or the analyst CA$100.91 target range?
Most Popular Narrative: 10% Undervalued
TC Energy’s analyst consensus Narrative on Simply Wall St pegs fair value at about CA$100.41, which sits above the latest CA$89.99 close and highlights the current gap between the market price and future cash flow expectations.
The company has sanctioned roughly $3b of new natural gas pipeline growth projects in 2026 at about 12% weighted-average unlevered after-tax IRRs and 5 to 7 times build multiples, while growing its late-stage and origination backlog. This may underpin future EBITDA as these projects enter service.
See why 72 investors see TC Energy as 10% undervalued.
Result: Fair Value of CA$100.41 (UNDERVALUED)
Still, TC Energy’s high net debt and the risk of delays on large pipeline or power projects could quickly challenge the current analyst optimism.
Find out about the key risks to this TC Energy narrative.
Another View: TC Energy Through The P/E Lens
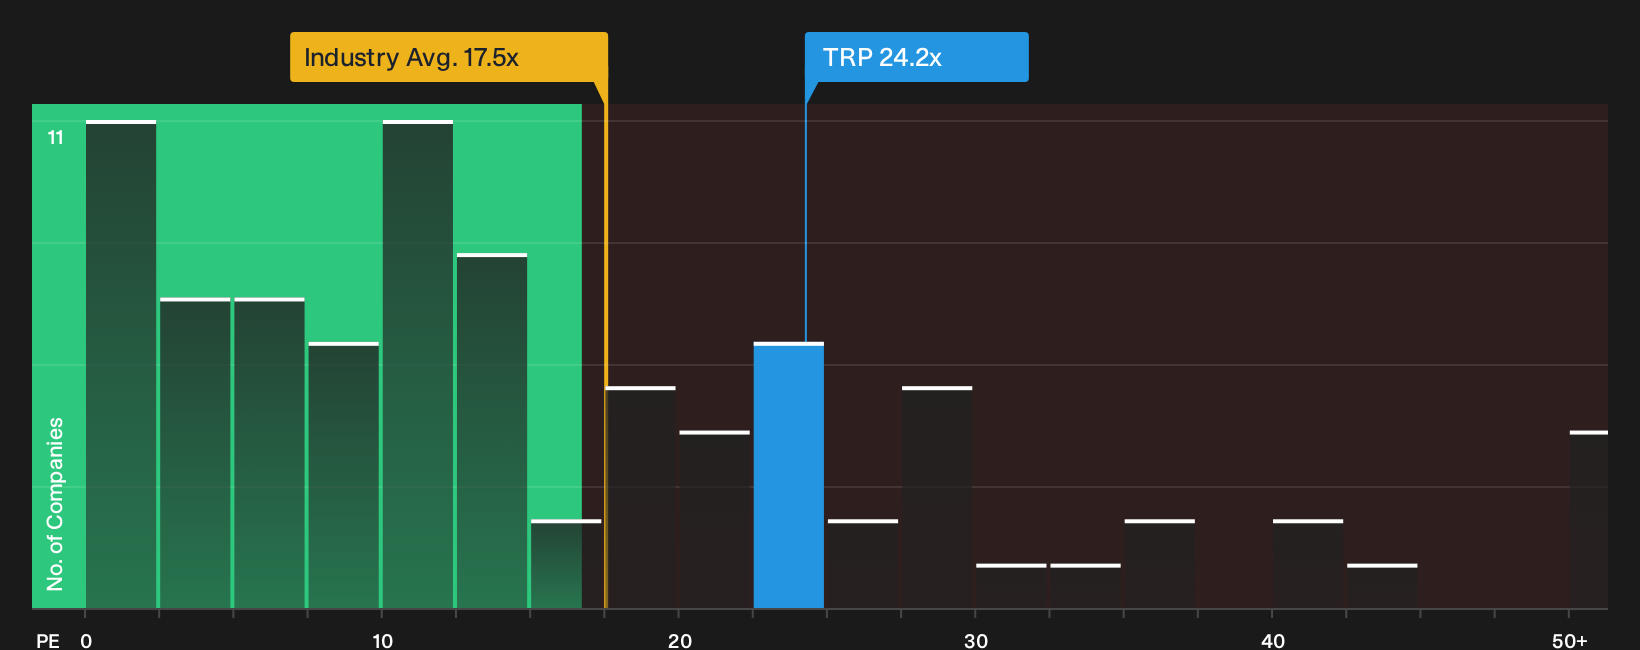
There is a different read on TC Energy when the focus shifts from analyst fair value to the current P/E. The stock trades on 24.2x earnings versus a Canadian Oil and Gas sector average of 17.5x and a peer group around 25.3x, while the fair ratio sits near 24.3x.
That combination presents a mix of comfort and risk. The valuation is close to the fair ratio and peer levels, yet carries a clear premium to the wider industry that could matter if sentiment or earnings expectations change again.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TC Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about whether TC Energy’s latest moves tilt the balance more toward promise or risk right now? Act quickly, stress test the numbers yourself, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond TC Energy?
Do not stop with a single stock. Broaden your watchlist with a focused set of ideas that match your goals before the next move in the market.
- Target potential mispricing by scanning a curated mix of quality companies on the 5 high quality undervalued stocks.
- Strengthen your income plan by reviewing dependable payers in the 3 dividend fortresses.
- Dial down portfolio stress by filtering for sturdier businesses using the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com