


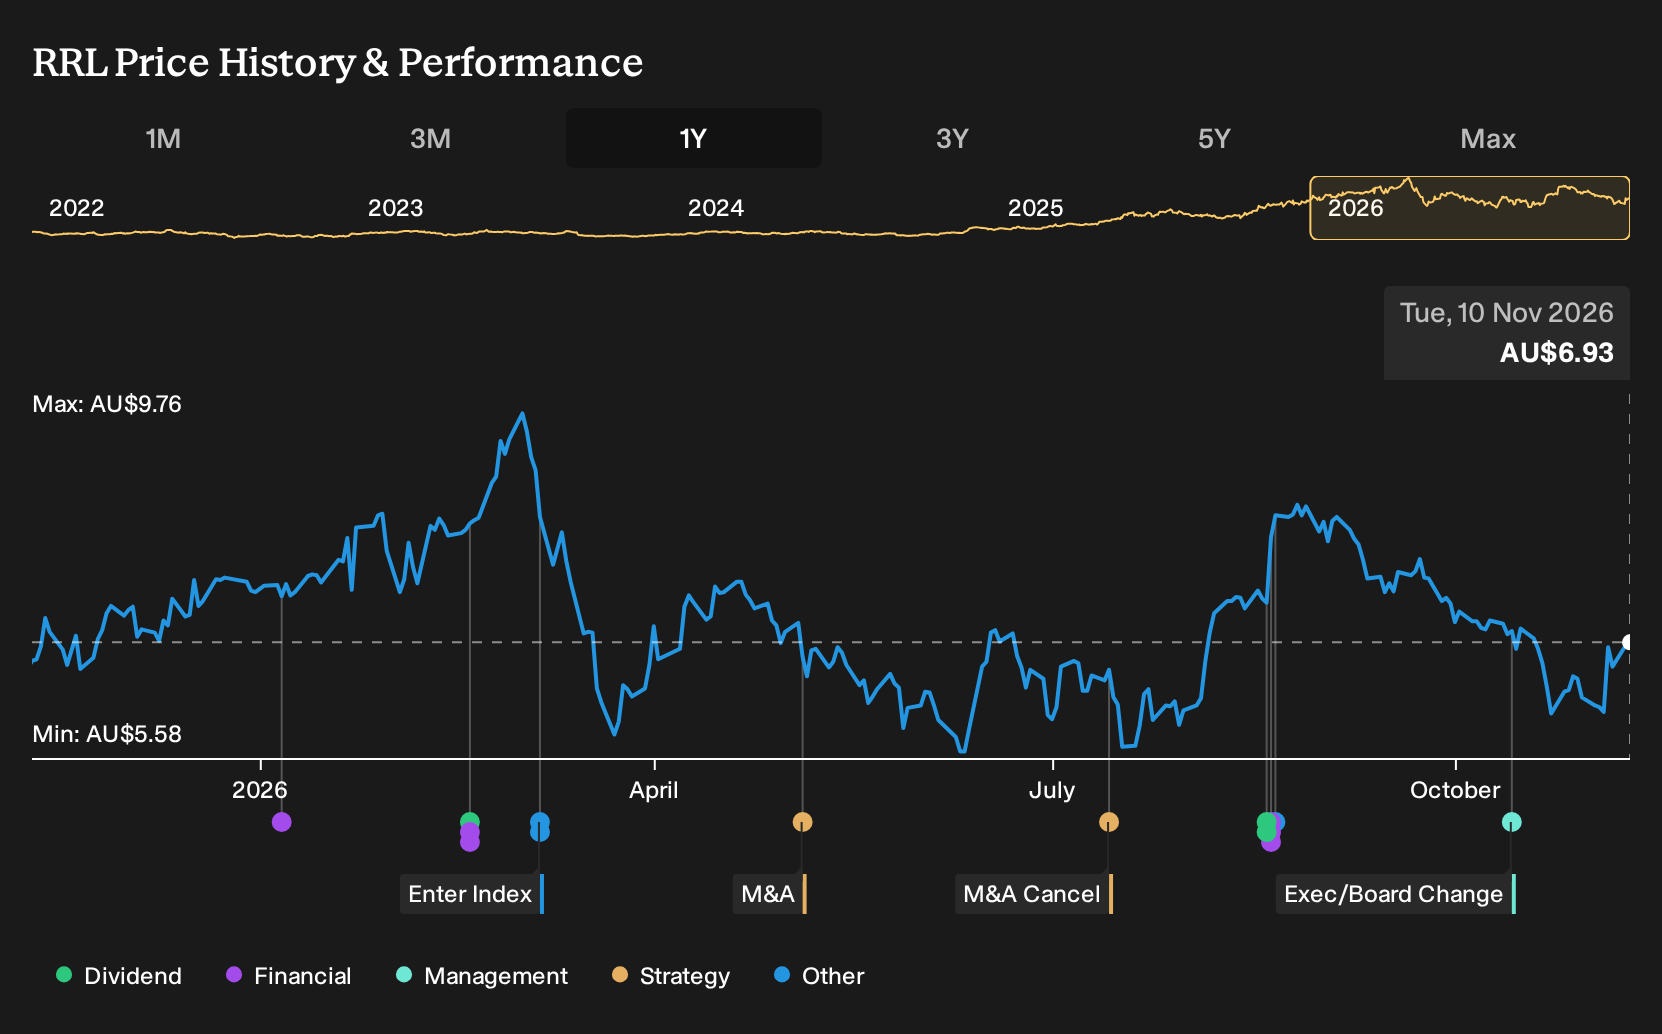
- Regis Resources has reported that a contract worker died following an incident at the Rosemont process plant at its Duketon South gold operation in Western Australia on 6 November 2026, raising serious questions about operational safety at the site.
- The fatality highlights how unplanned stoppages, investigations and potential regulatory responses can affect production reliability, cost control and project execution across Regis Resources' broader mine portfolio.
- We will examine how Regis Resources' investment narrative is tested by this fatal Duketon South incident and its implications for operational risk.
Stress test your thesis on Regis Resources by lining it up against hand-picked peers on safety, balance sheet strength and valuation using the 6 resilient stocks with low risk scores.
Regis Resources Investment Narrative Recap
To own Regis Resources, you really need to believe the business can keep turning its Australian gold assets into steady production while holding the line on all in sustaining costs that recently reached A$3,617 per ounce. The analyst consensus Narrative on Simply Wall St leans on that idea, alongside disciplined use of its A$1.28 to A$1.3 billion in cash and bullion and a debt free balance sheet.
The Duketon South fatality introduces a serious operational risk overlay. If investigations lead to extended shutdowns at Rosemont or broader regulatory interventions, the near term swing factor becomes production reliability and unit costs. Weather disruption, rising diesel costs and any downtime driven by safety reviews could all keep margins under pressure.
In the context of this incident, the most relevant piece of the recent analyst consensus Narrative on Simply Wall St is the focus on cost pressure and production execution at Duketon. All in sustaining costs already sit above guidance, and Q1 FY27 output of 83,000 ounces relies more heavily on low grade stockpiles after weather disruption.
When you layer a serious safety event on top of that, the near term story around Regis Resources shifts further toward operational delivery risk. Key catalysts now appear tied to how quickly Rosemont can return to stable, safe operations, how unit costs respond from the elevated A$3,617 per ounce level, and whether management can protect cash generation while progressing longer dated options like McPhillamys without leaning too heavily on dilution.
Regis Resources Forecasts Under Pressure From Safety Risk
Regis Resources' current analyst storyline rests on fairly flat revenue expectations and softer profitability, with forecasts pointing to A$2.3b of revenue and A$684.0m of earnings by 2029 while the business works through higher costs and now a serious safety issue at Duketon South.
Regis Resources' narrative projects A$2.3b revenue and A$684.0m earnings by 2029. This implies roughly flat yearly revenue trends and an earnings decline of about A$31.1m from A$715.1m today.
Uncover why Regis Resources' fair value indicates a 12% potential upside to its current price, a gap that may not last long once sentiment stabilises.
Exploring Other Perspectives
Some of the lowest analysts were already focused on a different risk before this Duketon South incident. They worried that tighter environmental and safety regulation could keep all in sustaining costs high and compress margins, with revenue projections closer to A$1.7b and earnings around A$378.5m by 2029. That is a much more cautious Regis Resources story. Use this event as a prompt to compare those pessimistic assumptions with your own expectations, and explore how both the upbeat and bearish narratives might shift once analysts update their views.
Explore 4 other Regis Resources fair value estimates, including one that suggests as much as 65% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Regis Resources research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Regis Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Regis Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Regis Resources?
If this Duketon South incident has you reassessing Regis Resources, it can be useful to set that thesis alongside a broader watchlist of alternatives that match your risk and return preferences.
- For investors who care most about capital preservation and steadier business models, consider scanning a curated 6 resilient stocks with low risk scores that focuses on resilience over excitement.
- If value is your priority and you are hunting for quality stocks that appear priced conservatively, weigh your Regis Resources view against a carefully filtered 2 high quality undervalued stocks that applies both balance sheet and cash flow checks.
- Those seeking opportunities with stronger growth potential away from the usual crowd can broaden their research with a focused 14 high quality undiscovered gems that highlights under followed companies with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com