


Knorr-Bremse (XTRA:KBX) just paired a fresh nine month earnings update with a reaffirmed 2026 outlook, giving investors new numbers on current profitability and a clearer view of management’s expectations for the full year.
At a share price of €96.5, Knorr-Bremse has seen short term momentum pick up, with a 1-day share price return of 1.42% and a 7-day share price return of 4.04%. The 1-year total shareholder return of 16.99% and 3-year total shareholder return of 83.95% point to a longer running rerating as investors weigh the latest earnings and reaffirmed 2026 outlook against the company’s risk profile and valuation.
Compare Knorr-Bremse’s momentum and guidance with a curated group of industrial peers by scanning the list of solid balance sheet and fundamentals (194 results) that currently combine financial resilience with earnings power.
Knorr-Bremse now trades about 17% below consensus targets and at an even steeper discount to one intrinsic estimate, despite the recent rebound. Is that caution protecting you from risk or causing you to miss potential upside?
Most Popular Narrative: 19% Undervalued
Knorr-Bremse’s analyst consensus Narrative on Simply Wall St points to a fair value of €119.6 per share compared with the last close at €96.5. This frames the current discussion around margin mix, cash generation and portfolio quality rather than headline growth alone.
Ongoing portfolio rotation, with around €750m of mainly sub 5% margin revenue divested and about €600m of 15% plus margin businesses acquired, including signaling and digital service assets, is shifting Knorr-Bremse toward a mix that can support higher group EBIT margins and cash generation.
See why 6 investors see Knorr-Bremse as 19% undervalued.
Result: Fair Value of €119.6 (UNDERVALUED)
Still, execution on shifting production to lower cost regions and integrating higher margin acquisitions like duagon could stumble. This would challenge the current Knorr-Bremse thesis.
Find out about the key risks to this Knorr-Bremse narrative.
Another View On Knorr-Bremse’s Valuation
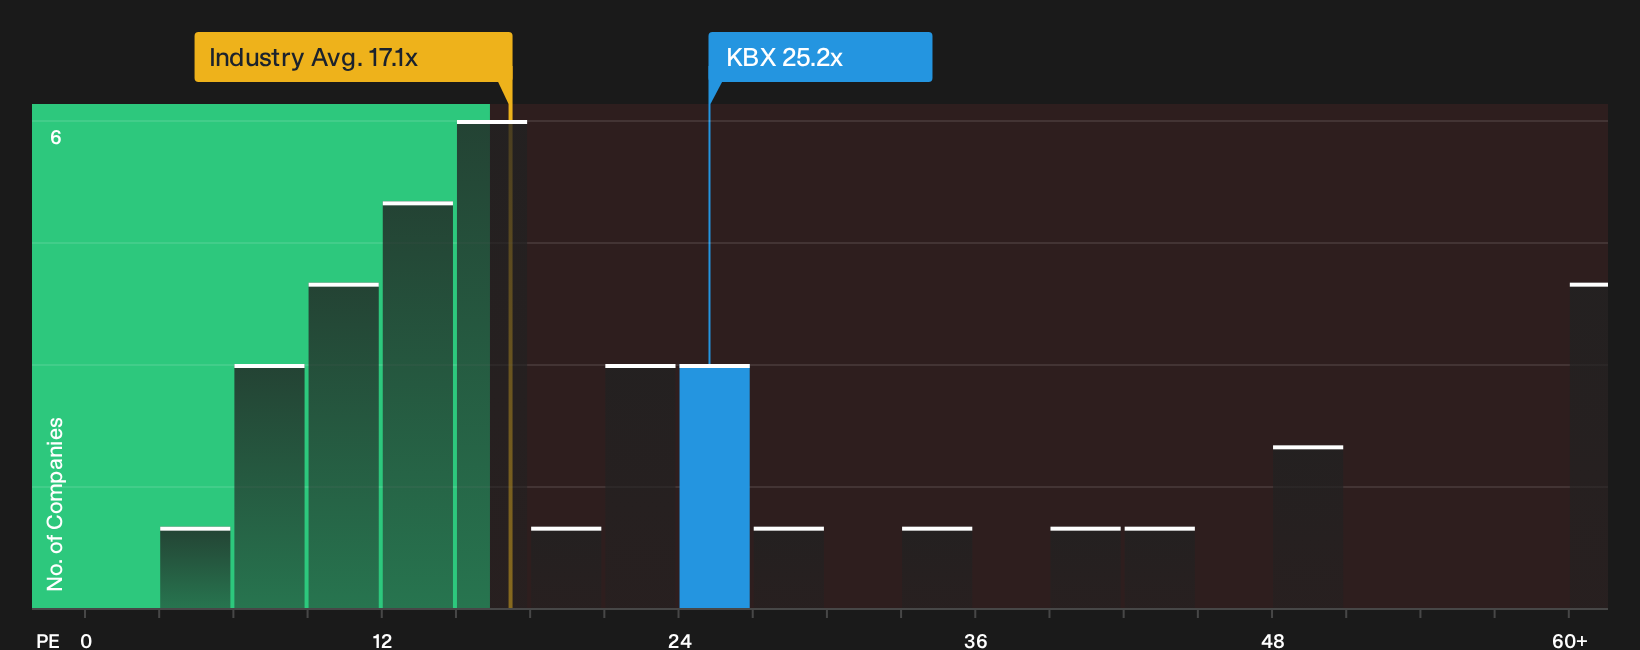
The story looks very different once the focus shifts from cash flows to earnings multiples. Knorr-Bremse trades on a P/E of 25.2x, compared with 23.2x for peers and 17.1x for the wider German Machinery group, while its fair ratio sits lower at 21.7x. That gap points to richer pricing on earnings. How comfortable are you paying above both sector and fair ratio levels for this margin mix narrative?
To see how these earnings based signals stack up in detail, including how far the current P/E diverges from the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Knorr-Bremse story so far, or a clear skew in one direction? Put the data in context quickly, weigh both the caution and the optimism, then ground your decision in the full picture of 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Knorr-Bremse?
If Knorr-Bremse has you thinking harder about pricing, quality and risk, use that same mindset to hunt for other opportunities before the crowd moves first.
- Target potential mispricings by reviewing a curated set of resilient businesses that still screen as attractively valued on cash flows and balance sheets through the 200 high quality undervalued stocks.
- Prioritise stability over drama by scanning companies that score well on financial strength and lower risk profiles using the 204 resilient stocks with low risk scores.
- Spot resilient operators with the capacity to reinvest or return cash by filtering for firms with stronger balance sheets and solid fundamentals via the list of solid balance sheet and fundamentals (194 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com