


- Sirius Real Estate reported a trading update with 11.3% year-on-year rental growth, with 5.1% from organic progress and the balance from acquisitions including defence-related properties.
- The mix of organic rental uplift and recently acquired, defence-linked assets points to a business model leaning heavily on asset management and value-add deals rather than simple yield collection.
- This article now explores how Sirius Real Estate's 11.3% rental growth update could influence the investment narrative built around value-add parks.
Scan other value-add real estate plays that show similar momentum in asset management and rent roll growth through our hand-picked 5 high quality undiscovered gems.
Sirius Real Estate Investment Narrative Recap
To own Sirius Real Estate, you need to believe that its value add business park model in Germany and the UK keeps generating steady rent roll progress from asset management, not just from buying yield. The analyst consensus Narrative on Simply Wall St leans on that pattern continuing as more properties move from value add to mature and support recurring income.
The recent 11.3% rental growth update speaks directly to that belief, because it mixes 5.1% organic growth with contributions from acquisitions, including defence linked sites. The short term swing factor remains how quickly refurbished or underperforming parks are leased, while the biggest risk is vacancy staying high as Sirius rotates tenants and keeps spending on capex heavy upgrades.
There have been no fresh company announcements listed alongside this trading update, so the cleanest reference point is still the analyst consensus Narrative on Simply Wall St. That view leans on Sirius using its balance sheet and cash to keep acquiring underperforming assets, then lifting rent and occupancy as those parks mature over time.
In that context, the 11.3% rent growth print acts as a live test of the value add thesis and of how well leverage and operating cash flow are being balanced. For you as a shareholder, the key watchpoints stay the same: tenant churn on both sides of the Channel, execution on refurbishments and leasing, and how comfortably debt is serviced as Sirius leans into acquisitions.
Sirius Real Estate's current analyst storyline points to €289.7 million in revenue and €222.1 million in earnings by 2029. That profile is built on revenue declining by 6.3% per year and an earnings reduction of €7.5 million from €229.6 million today.
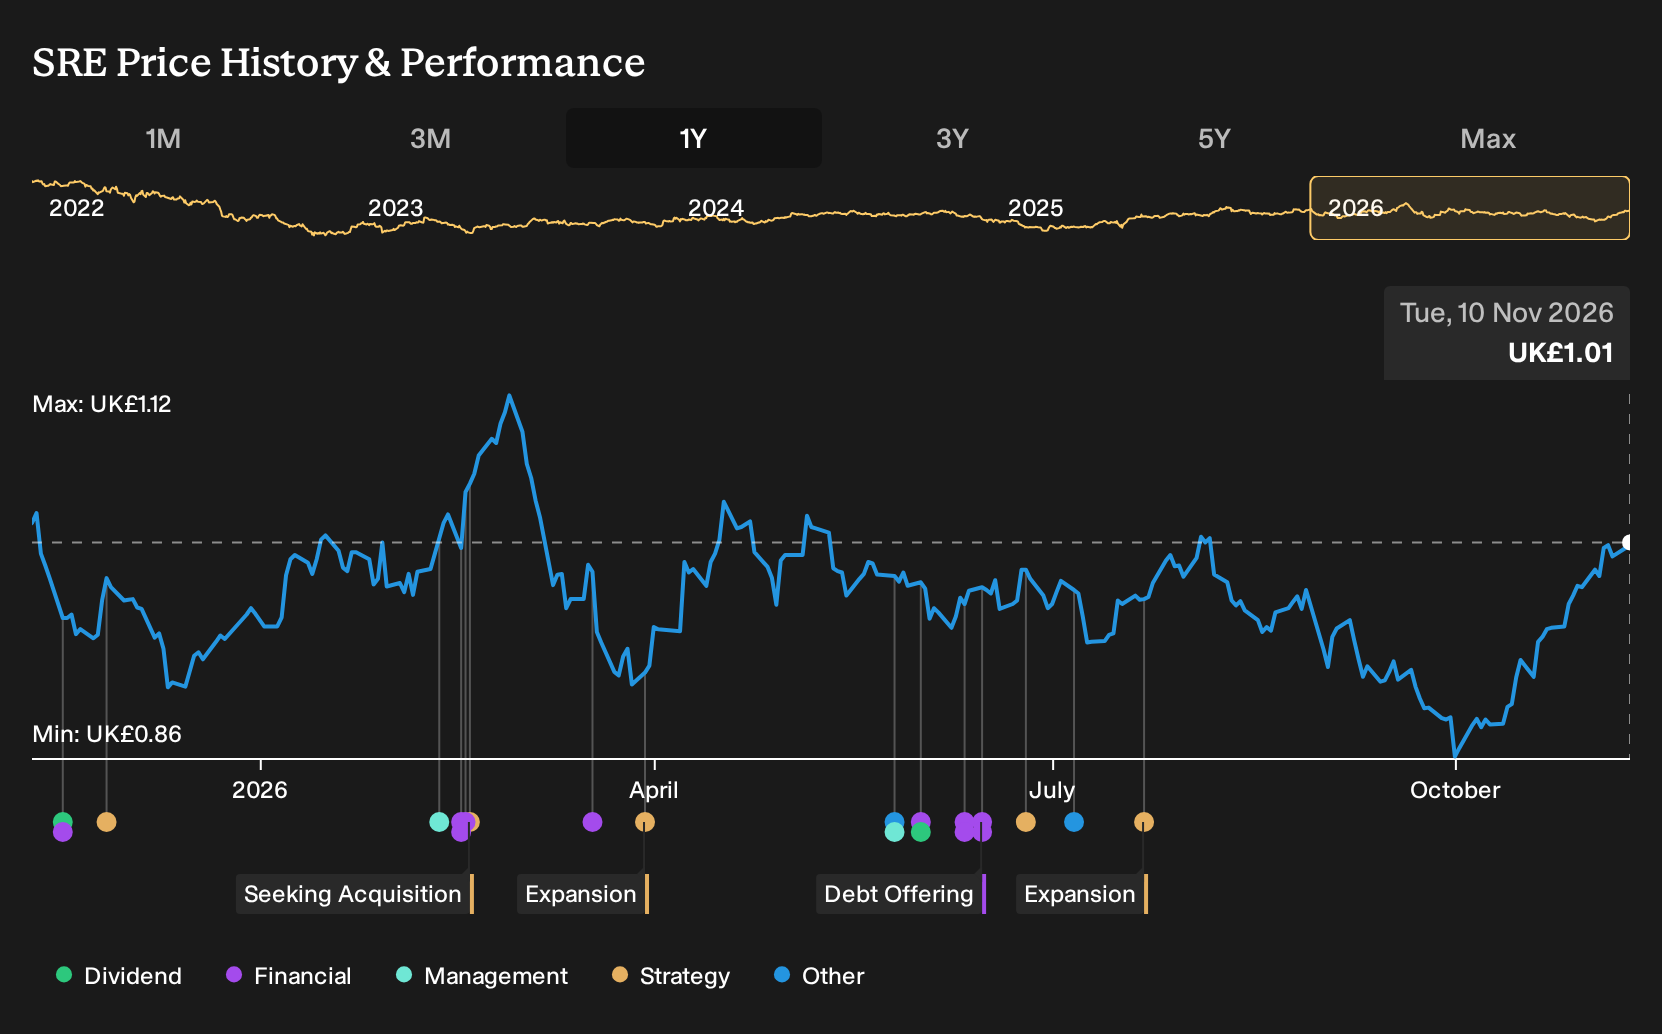
Uncover why Sirius Real Estate's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently has 2 fair value views on Sirius Real Estate, with estimates ranging from 1.254804x to 2.040524x the recent share price. Those opinions do not yet factor in the 11.3% rent update. Set that against risks around leverage, redevelopment spend and SME demand, then compare several contrasting viewpoints before committing fresh capital.
Explore another Sirius Real Estate fair value estimate, including one that suggests there could be as much as 101% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sirius Real Estate research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sirius Real Estate. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sirius Real Estate's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sirius Real Estate?
If the Sirius Real Estate story has sharpened your focus on quality, use that momentum to broaden your watchlist with other opportunities that match different risk and income profiles.
- For investors who care most about resilience and capital protection, start with a curated group of companies that screen as 4 resilient stocks with low risk scores and see which match your comfort zone.
- If income is a priority, build out your watchlist using a focused set of 6 dividend fortresses that aim to combine yield with business stability.
- When you want to focus on financial strength and balance sheet quality, scan a tight list of solid balance sheet and fundamentals (9 results) to find candidates that may better handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com