


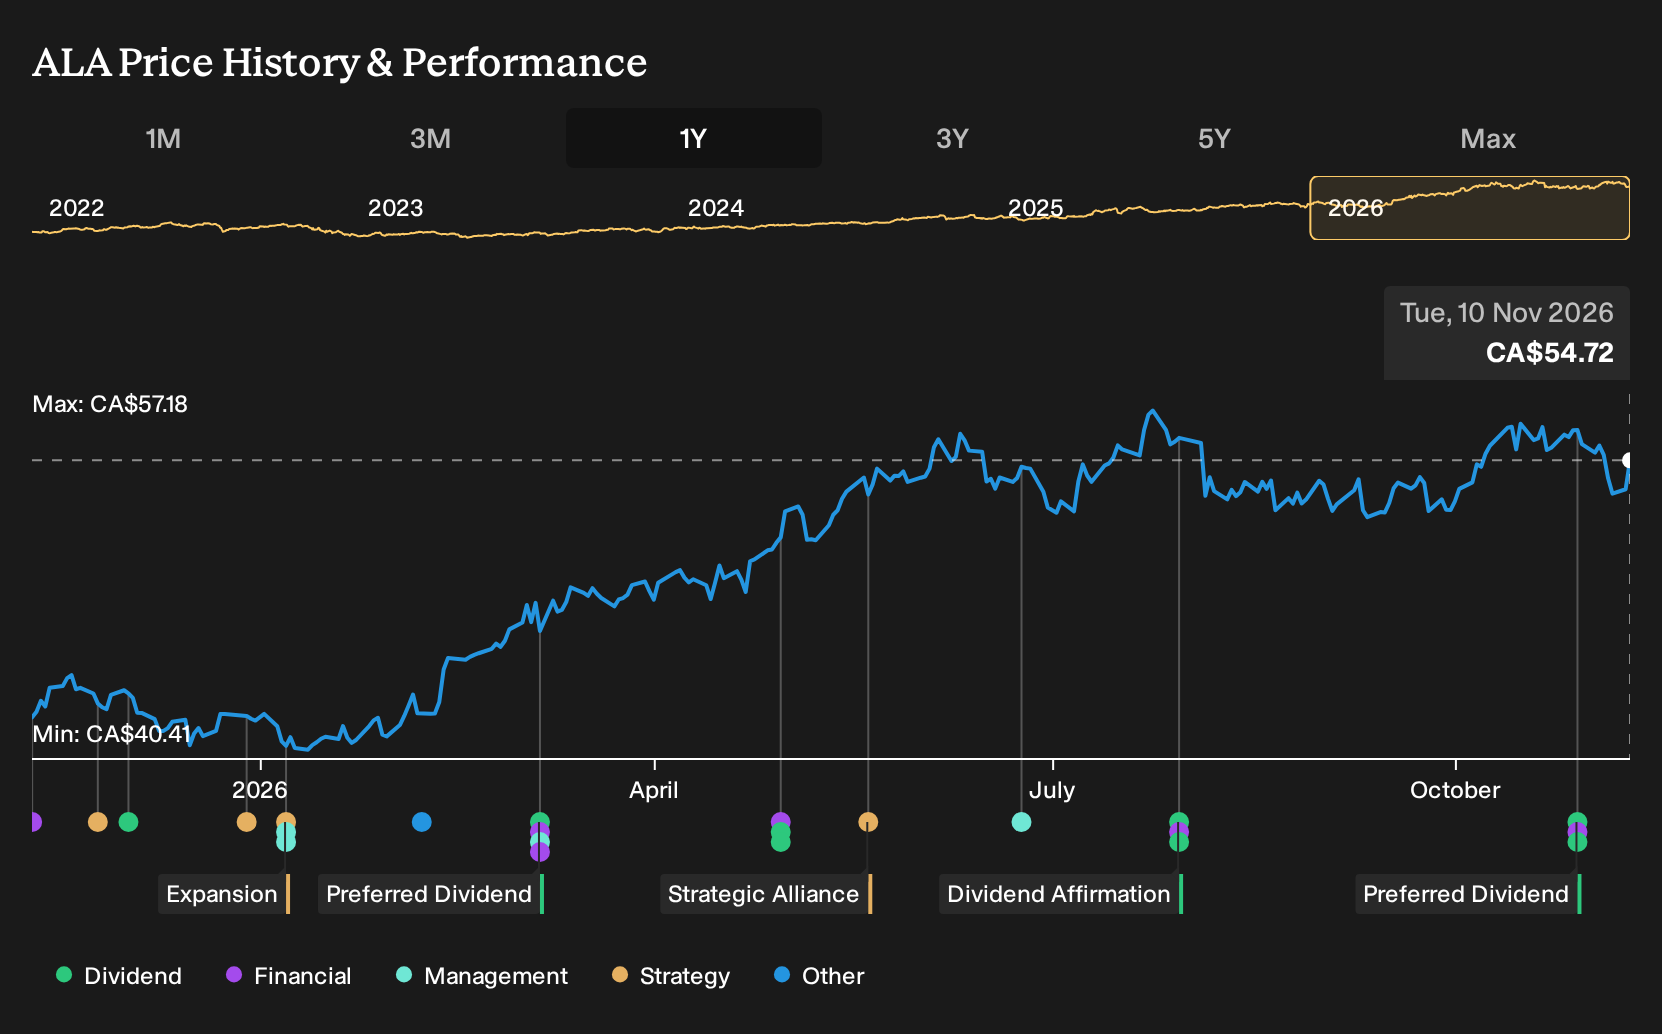
- AltaGas reported third quarter 2026 sales of C$3,431 million with a net loss of C$18 million and affirmed both common and preferred dividends payable on 31 December 2026.
- The mix of higher revenue, continued quarterly loss in the latest period, and ongoing dividend commitments highlights the pressure on AltaGas to fund shareholder payouts while managing earnings volatility.
- We will now look at how AltaGas's continued net loss alongside maintained dividends shapes the investment narrative that investors rely on.
Compare AltaGas's latest results with a hand picked 3 dividend fortresses that are also committing to regular payouts while balancing earnings pressure.
AltaGas Investment Narrative Recap
To own AltaGas, you need to be comfortable with a utility and midstream model that leans on regulated gas networks and fee based LPG exports, while accepting some earnings lumpiness quarter to quarter. The latest quarter showed higher sales alongside a small net loss, so the immediate story is about execution and cost control rather than headline growth.
The analyst consensus narrative on Simply Wall St focuses on long term projects such as the Ridley Island Energy Export Facility and ongoing pipe replacement. In the near term, the biggest swing factor remains delivering those large capital programs without further cost pressure. The key risk is that heavy investment and policy headwinds could compress returns on the regulated side.
The most relevant update for that thesis is the decision to affirm the quarterly common dividend of C$0.334 per share payable on 31 December 2026. That sits alongside commentary that current dividends are not well covered by free cash flows and that interest costs are not comfortably covered by earnings.
For you as a shareholder, the commitment to both common and preferred payouts indicates that AltaGas is still prioritising returning cash to investors while funding multi year projects and modernization. The trade off is tighter financial flexibility if earnings softness persists or if capital intensity at Ridley Island or across the utilities grid increases from here.
AltaGas is being modeled on the basis that revenues reach C$16.4b and earnings reach C$1.0b by 2029. This implies 6.2% yearly revenue growth and an earnings increase of about C$385m from current earnings of C$615.0m.
Uncover why AltaGas' fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly C$60 to C$86 per share, so even a small group of retail viewpoints on AltaGas lands far apart. Those opinions were formed before the latest quarterly loss and ongoing dividend affirmations, so you may want to test how regulatory risks and capital heavy projects could shift your own view.
Explore another AltaGas fair value estimate, including one that suggests as much as 58% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AltaGas research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AltaGas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AltaGas' overall financial health at a glance.
Looking for more AltaGas-sized investment ideas?
If the AltaGas story has sharpened your thinking about income, risk and balance sheet strength, it can help to line it up against other opportunities that share similar traits. The Simply Wall St Screener lets you quickly scan for shares that match the mix of dividends, quality and resilience you are trying to build into your portfolio.
- If you want income that aims to be resilient, start by comparing AltaGas with a curated group of 3 dividend fortresses that focus on sustaining regular payouts.
- For investors who care most about getting strong fundamentals at a fair price, run a quick check across a 5 high quality undervalued stocks that combine solid financials with attractive valuations.
- If capital preservation matters to you as much as upside, stress test your ideas against a 9 resilient stocks with low risk scores designed to highlight businesses with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com