


Amentum Holdings’ fusion partnership with Kyoto Fusioneering
Amentum Holdings (AMTM) has signed a Memorandum of Understanding with Kyoto Fusioneering to work together on fusion energy projects across the UK, Japan, and the US, focusing on engineering, plant integration, and advanced digital tools.
Amentum Holdings has seen its share price climb 19.9% over the past 30 days, including a 3.5% one-day share price return after the fusion announcement. However, the year-to-date share price return is still down 24.1%, while the 1-year total shareholder return is roughly flat at 0.7%, which hints at short-term momentum building after a tougher stretch.
Scan how Amentum Holdings compares with other contractors leaning into complex energy and infrastructure work by reviewing our hand picked 41 power grid technology and infrastructure stocks in one place.
Amentum Holdings now has a headline fusion partner and a sharp 30 day rebound, yet the shares are still down sharply this year. Is the business quality already fully reflected in today’s price, or not?
Most Popular Narrative: 22% Undervalued
At a last close of $23.13 against an analyst consensus fair value of about $29.58, the leading narrative on Amentum Holdings points to undervaluation. That analyst consensus Narrative on Simply Wall St ties this gap to a mix of contract backlog, margin execution, and long run spending on defense, digital, and nuclear work, all discounted at an 8.7% rate.
Ramp up of large, long duration awards such as the U.S. Space Force Range contract, Sellafield remediation and NASA Cosmos is set to convert the current $47 billion backlog and $20 billion of pending bids into higher run rate revenues and improved operating leverage, supporting sustained earnings growth.
See why 13 investors see Amentum Holdings as 22% undervalued.
This storyline leans heavily on margin quality. Analysts in that framework work with current net income of $204.0 million on $14.13b of revenue, and forecast profit margins at about 3.5% over time, compared with 1.4% today. The stronger earnings profile is then discounted at roughly 8.7% to reach that $29.58 fair value estimate.
Expectations inside the same Narrative extend further out. Revenue is modeled at $15.1b and earnings at $532.2 million by 2029, with a P/E of 17.7x applied to those earnings to support the target range. That assumed earnings path is faster than the 2.2% annual revenue growth embedded in the model, which means the thesis leans on mix, execution, and cost control rather than a surge in top line.
Analyst views feeding this approach are not uniform. Targets span from $21.00 at the low end to $40.00 at the high end, and commentary describes a mix of concern over softer sales growth and confidence in Amentum Holdings’ profit potential. The 21.8% discount to the $29.58 fair value estimate reflects where the consensus of those differing expectations sits today, not a guaranteed outcome.
Result: Fair Value of $29.58 (UNDERVALUED)
Still, the Amentum Holdings story can change quickly if execution slips on large government contracts or if U.S. funding disruptions delay awards and reduce visibility.
Find out about the key risks to this Amentum Holdings narrative.
Another View: Amentum Holdings on earnings multiples
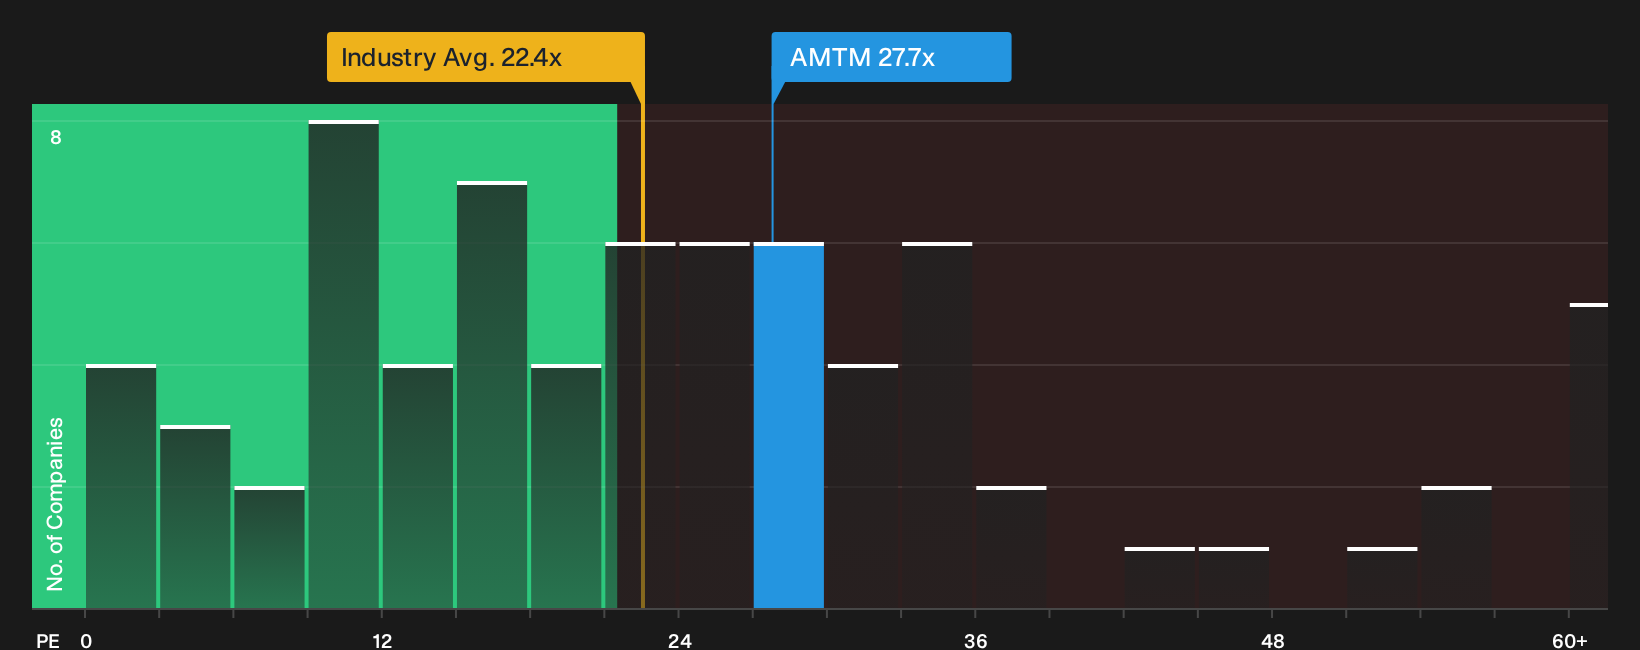
A different lens tells a less generous story. On a P/E of 27.7x, Amentum Holdings trades richer than both the US Professional Services industry on 22.4x and its peer group on 24.8x, and even above a 26.5x fair ratio that the market could eventually lean toward.
If that premium multiple drifts closer to the fair ratio or industry level while the business simply tracks existing forecasts, this raises a question: how much room does that really leave for upside from here, versus the risk of a valuation reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Amentum Holdings so far. If this mix of potential and concern feels finely balanced, it is worth moving quickly to examine the 3 key rewards and 2 important warning signs.
Looking for more Amentum Holdings investment ideas?
If the Amentum Holdings story has your attention, do not stop here. A wider watchlist can sharpen your judgment and reveal opportunities others miss.
- Target potential mispricing by scanning a 36 high quality undervalued stocks that combines strong cash flows with balance sheets that can shoulder tougher conditions.
- Prioritise resilience and cut down on nasty surprises through a 30 resilient stocks with low risk scores focused on businesses with steadier risk profiles.
- Get ahead of the crowd by reviewing a 20 high quality undiscovered gems built around quality fundamentals that have not yet attracted broad attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com