


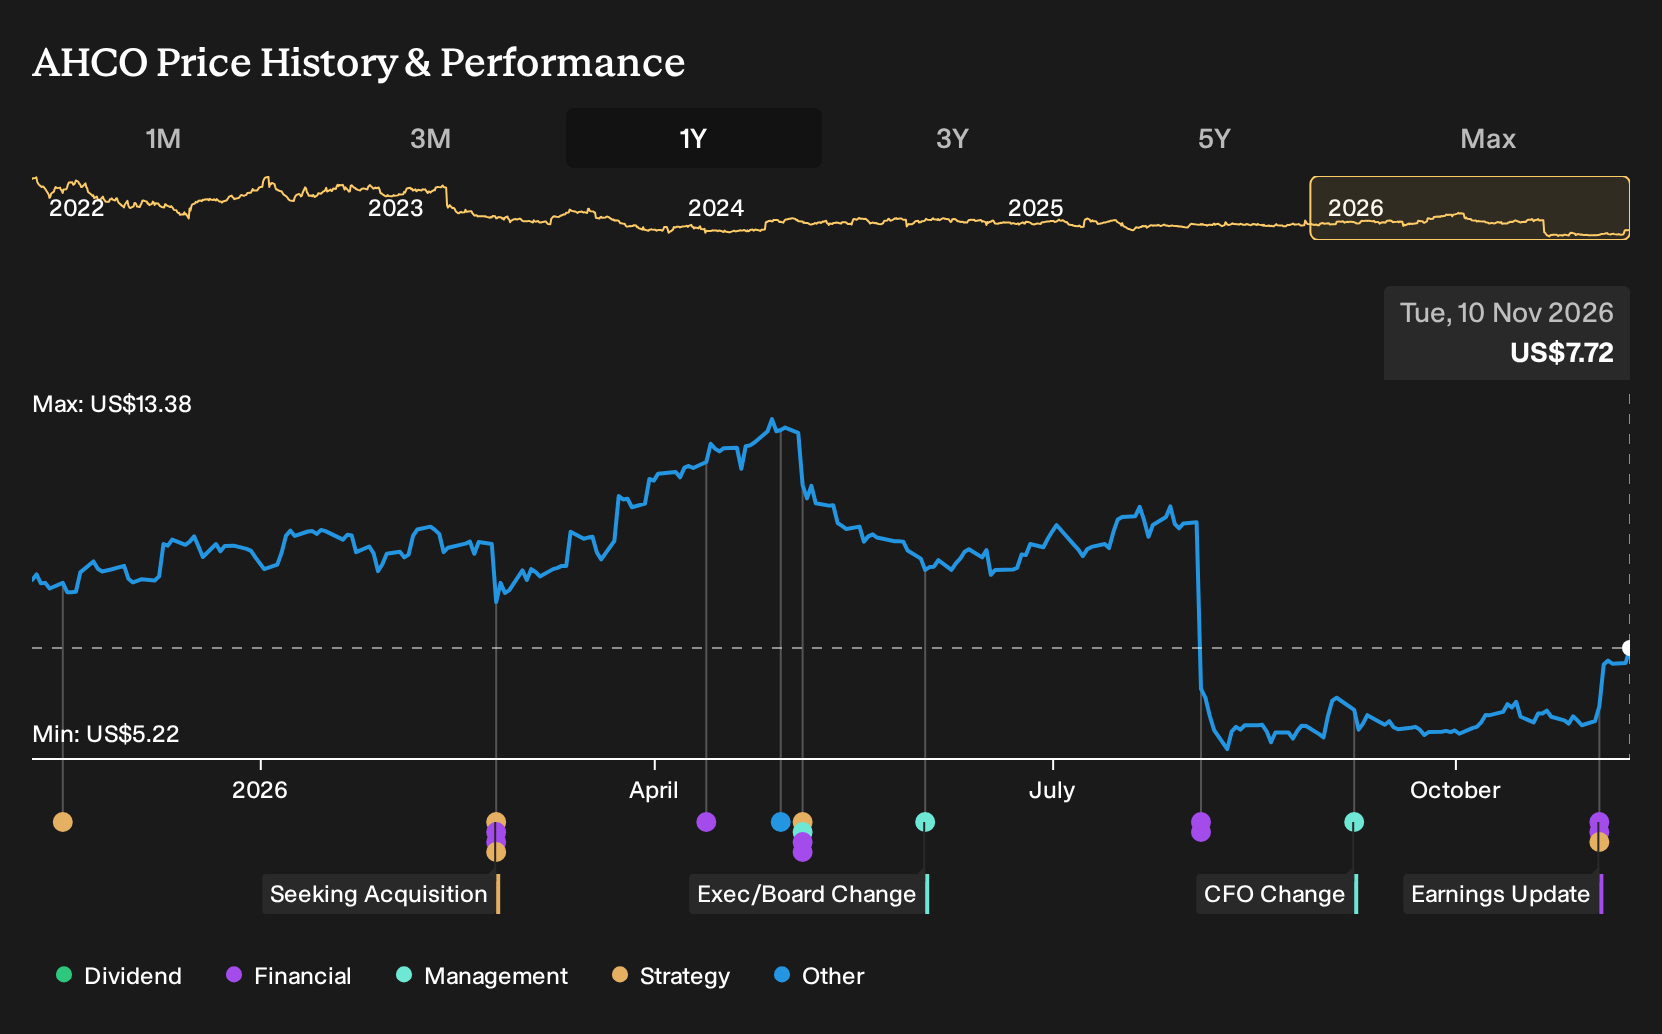
- AdaptHealth reported third quarter 2026 sales of US$745.65 million and a net loss of US$153.99 million after recording a US$184.75 million goodwill impairment, while also slightly raising full year 2026 net revenue guidance to a range of US$2.88 billion to US$2.90 billion.
- The combination of higher sales, a reported swing from profit to loss, and a modestly higher revenue outlook indicates that AdaptHealth is absorbing accounting and cost pressure while still signaling confidence in demand for its home healthcare services.
- The focus now turns to how AdaptHealth's raised 2026 revenue guidance, despite a large goodwill charge, may influence the investment narrative.
AdaptHealth Investment Narrative Recap
To own AdaptHealth, you need to believe the home healthcare at home model can turn higher sales into consistent cash, even with lumpier earnings. The raised 2026 net revenue guidance to US$2.88b to US$2.90b points to management seeing demand support, while the goodwill impairment keeps the spotlight on execution rather than headline profit prints.
The near term swing factor is whether capitated contracts and cost work can lift EBITDA and free cash flow toward prior expectations. The biggest risk is that issues seen on the West Coast contract or supplier pricing changes resurface, which could keep EBITDA margins under pressure despite the healthier revenue run rate AdaptHealth just guided to.
The earnings release on 3 November 2026 is the clearest reference point for this quarter. You are seeing a business that reported US$745.65m in third quarter sales and a net loss of US$153.99m for the period, after taking a US$184.75m goodwill impairment. That mix of higher revenue and a reported loss is where the current AdaptHealth debate really sits.
Those numbers tie directly into the catalysts and risks highlighted in the analyst consensus Narrative on Simply Wall St, which leans on capitated contracts, portfolio refocus and balance sheet repair. The quarter gives you fresh data on how quickly earnings can be hit by contract and supplier friction, and how much patience you need while management works to convert this bigger top line into durable cash generation.
AdaptHealth's narrative projects US$3.0b revenue and US$122.1 million earnings by 2029. This assumes revenue declines at 3.9% per year and requires an earnings swing of about US$530 million from current earnings of a US$407.5 million loss.
Discover why AdaptHealth's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist in the alternate AdaptHealth narrative is margin expansion. The most optimistic analysts were penciling in profit margins rising from a 6.9% loss-making level to 10.0% by 2029, with earnings climbing toward US$335.0 million on roughly flat revenue around US$3.3b. Those estimates came before this guidance tweak and goodwill hit, so you may want to compare several viewpoints and decide which story feels more realistic to you.
Explore 2 other AdaptHealth fair value estimates, including one that suggests as much as 296% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AdaptHealth research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for AdaptHealth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AdaptHealth's overall financial health at a glance.
Looking for more AdaptHealth investment ideas?
If the AdaptHealth story has sharpened your thinking about risk, cash generation and future expectations, it can help to compare it with other companies that share some of the traits you care about most. The Simply Wall St Screener lets you filter by quality, valuation, income profile and balance sheet strength so you can build a watchlist that genuinely fits your style.
- For investors who want potential mispricing backed by fundamentals, start with a 36 high quality undervalued stocks that combine strong cash profiles with supportive balance sheets.
- If portfolio resilience matters most to you, focus on a 30 resilient stocks with low risk scores that score well on volatility and financial health checks.
- Income focused readers can zero in on steady cash return potential by reviewing a 5 dividend fortresses that currently offer higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com