


- Karooooo has recently attracted attention as a growth-focused mobility and logistics software provider after analysts lifted current-year earnings estimates and highlighted expected EPS expansion above industry averages.
- The key insight is that upward revisions to earnings forecasts reflect confidence in Karooooo’s subscription-led model, which depends on scaling connected fleet and logistics services while maintaining strong unit economics.
- We will now examine how Karooooo's higher earnings estimates might influence the existing investment narrative built around subscription growth and unit economics.
Compare Karooooo’s upgraded growth story with a hand picked set of other potential compounders by scanning the 20 high quality undiscovered gems that share strong fundamentals and room to gain investor attention.
Karooooo Investment Narrative Recap
To own Karooooo, investors need to believe the subscription engine can keep adding connected vehicles and logistics users while protecting its strong unit economics. The analyst consensus narrative on Simply Wall St highlights expansion into Southeast Asia, the Middle East and Europe, as well as cross selling products such as AI video and Cartrack Tag. The recent earnings upgrade mainly reinforces confidence that this roll out is still on track.
In the near term, the key swing factor is whether heavier spending on sales, marketing and IoT hardware converts into higher ARR without squeezing margins further. The biggest operational risk remains the mix shift toward lower ARPU regions and ongoing reliance on South Africa. Either of these could cap revenue growth if pricing or demand weaken.
The most relevant piece of context for this earnings-focused news is management’s choice to step up commercial investment. Sales and marketing expenses grew 47% year over year in Q3 FY26 and 33% in Q1 FY27, as the group pushed harder into new geographies and logistics workloads. That spend is now being judged against upgraded profit expectations.
This matters because Karooooo’s potential catalysts are closely linked to execution on that spend. Higher ARR retention, cross selling of AI camera video and growth in Karooooo Logistics, which reached ZAR 177m revenue with an 8% operating margin in Q1 FY27, all need to support operating leverage over time. Analyst enthusiasm around EPS depends on these operational pieces continuing to line up.
Karooooo's narrative projects ZAR 9.1b revenue and ZAR 1.8b earnings by 2029. This assumes 16.5% yearly revenue growth and an earnings increase of about ZAR 0.8b from ZAR 1.0b today.
Uncover how Karooooo's fair value reflects a 15% potential upside to its current price before the market closes the discount.
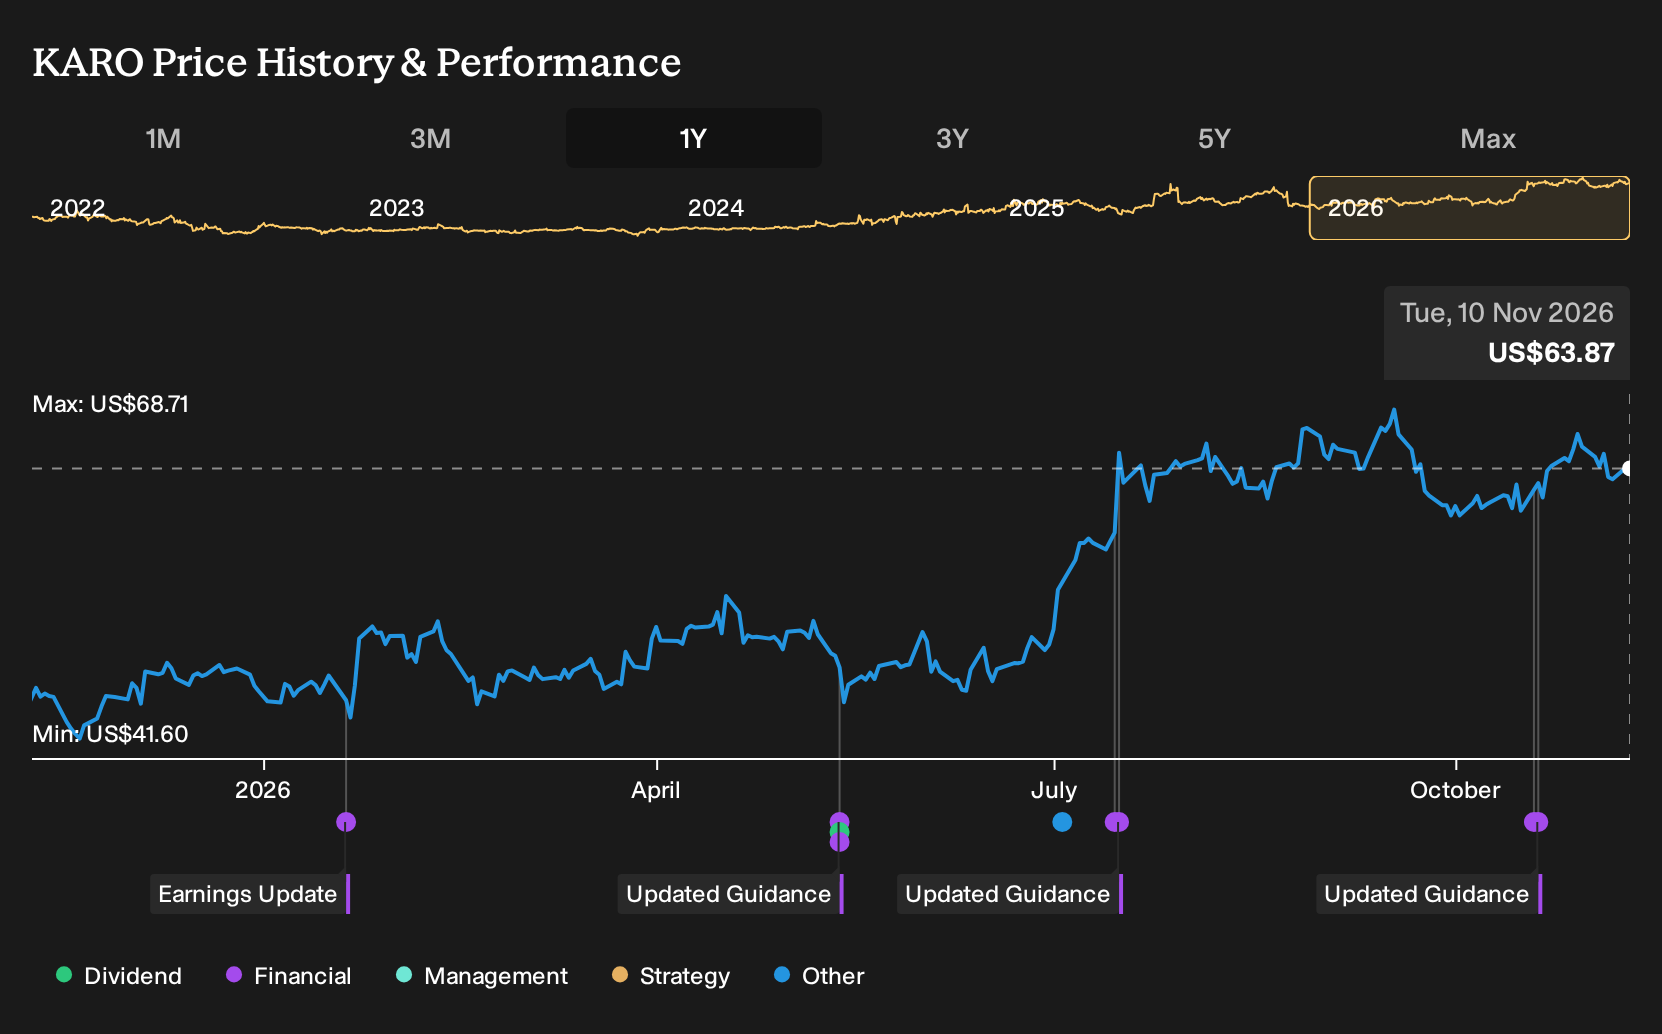
Exploring Other Perspectives
One alternate view focuses on free cash flow pressure rather than EPS upgrades. Before this news, the most cautious analysts were working off only ZAR 60m free cash flow in Q1 FY27 and building forecasts on revenue rising around 15.1% a year and earnings reaching about ZAR 1.8b by 2029. That is a meaningfully more restrained story than the consensus. This helps explain why opinions on Karooooo differ so widely. Treat this update as a prompt to compare those forecasts yourself and consider how both narratives might shift as new data comes through.
Explore 3 other Karooooo fair value estimates, including one that suggests as much as 22% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Karooooo research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Karooooo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Karooooo's overall financial health at a glance.
Looking for more investment ideas beyond Karooooo?
Once you have a view on Karooooo, it often helps to widen the lens and compare it with other opportunities that share similar quality markers or risk profiles. The Simply Wall St Screener can help you quickly find candidates that fit different roles in your portfolio, from stability to income to potential rerating stories.
- If capital preservation and smoother returns matter most to you, start by filtering for resilient businesses through the 30 resilient stocks with low risk scores that have historically carried lower risk scores.
- For investors who care about financial strength first and growth second, the list of solid balance sheet and fundamentals (24 results) can surface companies with sturdy balance sheets and fundamentals that hold up under closer inspection.
- If you want income to play a bigger part in your total return, focus on cash generators with meaningful payouts by scanning the 5 dividend fortresses that combine higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com