


Williams Companies earnings spark fresh look at the stock
Williams Companies (WMB) has moved back onto investor radars after its latest quarterly earnings and a new universal shelf registration filing. Together, these developments reshape the discussion around cash generation and future financing flexibility.
Over the past week the share price has slipped, with a 7-day share price return of 6.91% and a 30-day share price return of 7.17% lower. Williams Companies still sits at US$67.46 and carries a 1-year total shareholder return of 14.71% and a 5-year total shareholder return close to 2x, suggesting long term momentum remains in place even as shorter term moves reflect investors recalibrating growth prospects and risk after the strong earnings and fresh shelf registration.
Scan the Williams Companies setup against a curated field of resilient peers by lining it up next to 30 resilient stocks with low risk scores, which is built to hold up when conditions change.
Fresh earnings, a higher share price and a new shelf registration have already reset expectations for Williams Companies. Is most of the gain now reflected, or is the market still leaving clear upside on the table as valuation is tested next?
Most Popular Narrative: 21% Undervalued
On the latest numbers, the analyst consensus Narrative on Simply Wall St places Williams Companies' fair value at $85.61 compared with the recent $67.46 share price, which frames the current setup as materially discounted while hinging on specific growth projects being delivered.
The Power Innovation platform, backed by a US$5.34b equity funding commitment from partners, is supporting a series of behind the meter projects such as Socrates and Neo that carry multi year contracts, which can add incremental contracted earnings and improve overall returns on invested capital.
The commercialization of Neo, a 682 MW behind the meter power project with a 12.5 year contract and an expected build multiple of about 5x, together with continued phases of Socrates, provides Williams Companies with a growing base of long duration power cash flows that can support EBITDA growth beyond the traditional pipeline business.
See why 32 investors see Williams Companies as 21% undervalued.
Result: Fair Value of $85.61 (UNDERVALUED)
Still, the Williams Companies story can break if big Haynesville and LNG linked expansions stall on permitting, or if higher growth capex and leverage squeeze returns.
Find out about the key risks to this Williams Companies narrative.
Another View: What Williams Companies' P/E Is Signalling
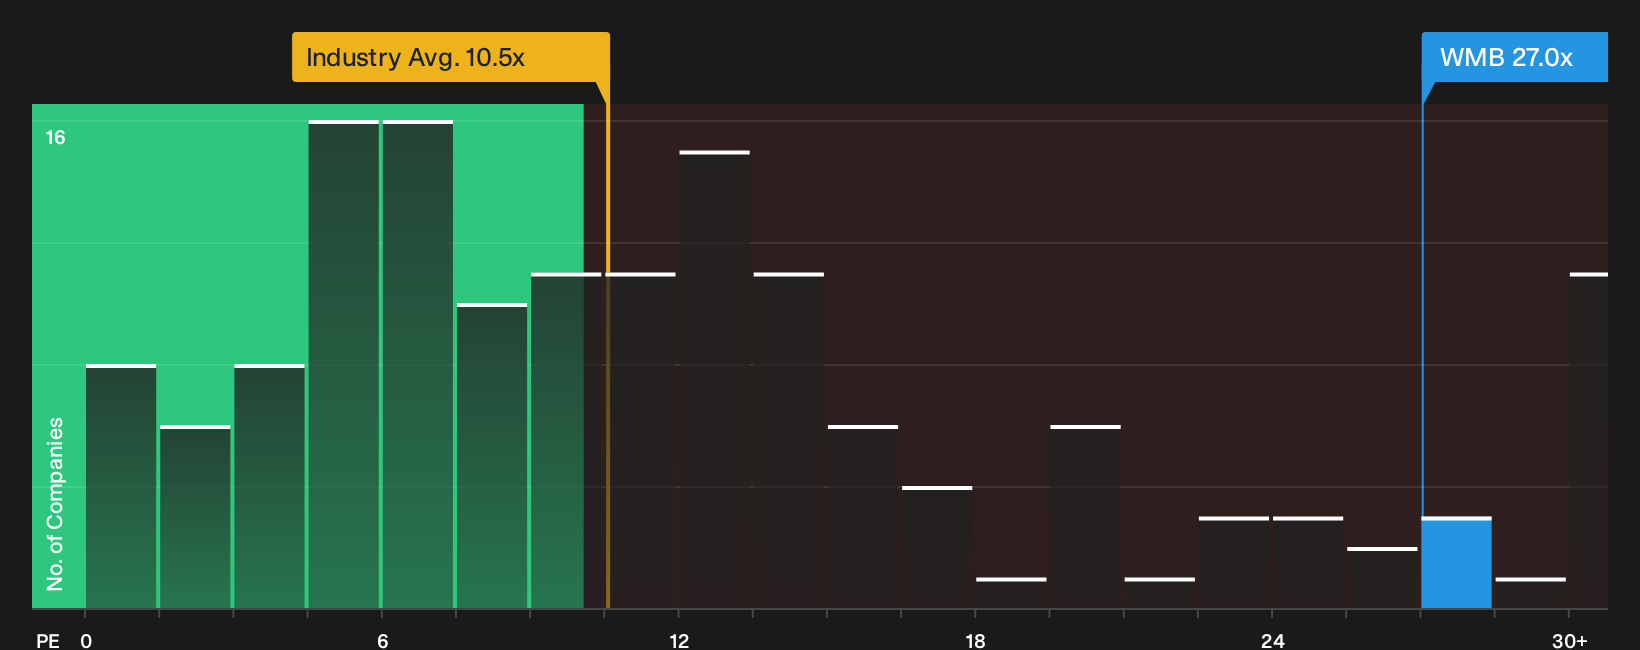
The story shifts once the focus moves from discounted cash flows to earnings multiples. Williams Companies trades on a P/E of 27x, which is far higher than the US Oil and Gas industry on 10.5x, its peer group on 14.4x and a fair ratio of 23.7x that the market could move toward. That kind of premium can signal quality and growth, or it can mean expectations leave less room for error. Which side of that line do you think this stock falls on?
For a closer look at how this earnings multiple gap stacks up against peers and what that might imply for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Williams Companies is split, with clear risks on one side and genuine upside on the other. Move quickly, test the numbers yourself and stress test the story against the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Williams Companies?
If Williams Companies has sharpened your focus on quality and risk, you can broaden your watchlist now with a few targeted screens that surface different types of opportunities.
- Target resilient compounding by scanning 36 high quality undervalued stocks that pair stronger fundamentals with prices that sit below their estimated worth.
- Lock in potential income streams by reviewing 5 dividend fortresses that offer higher yields while still passing core quality checks.
- Prioritize financial strength by filtering for list of solid balance sheet and fundamentals (24 results) so that shaky leverage profiles do not quietly drag on your returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com