


GCM Grosvenor has turned in a strong share-price run in recent years, and the latest earnings update has pushed the conversation back to a basic question. Are investors now paying a price that is fully justified by what the business earns today and what its profits may reasonably support over time?
- Over the past 3 years the stock has returned 77.7%, which puts real pressure on the current earnings base to support a much higher equity value.
- The company recently reported higher GAAP net income, fee-related earnings and adjusted net income year over year, which can shape how investors think about the durability and growth potential of its profit stream.
- The analysts covering GCM Grosvenor have run their own numbers. See what analysts think GCM Grosvenor's shares could be worth.
For investors, the debate is whether GCM Grosvenor's current share price lines up with what its earnings justify when viewed through this single lens.
If you are weighing GCM Grosvenor against other options that also put earnings front and center, it can help to compare it with 36 high quality undervalued stocks.
Has GCM Grosvenor Run Too Far on Earnings?
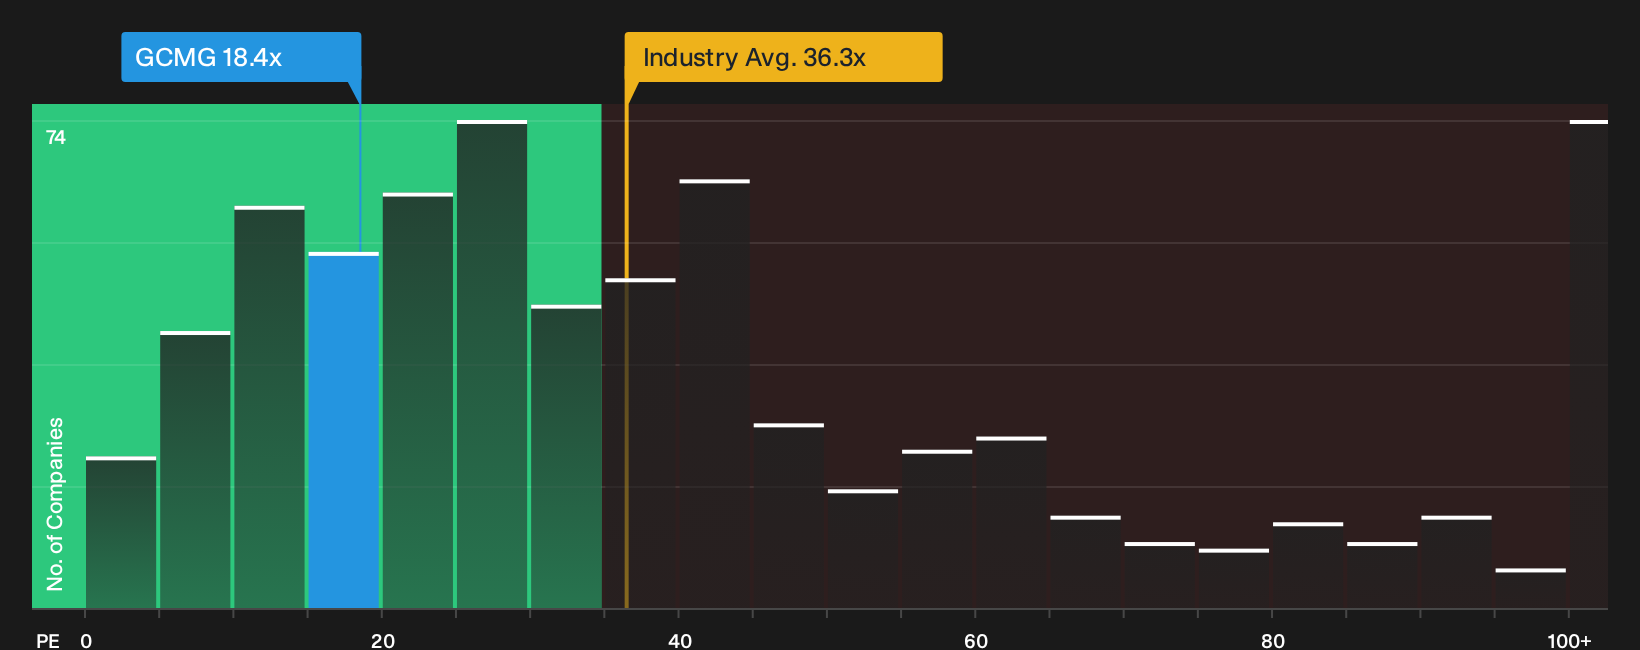
P/E is the cleanest fit for GCM Grosvenor because earnings drive how investors usually value listed asset managers. On this lens, GCM Grosvenor trades at about 18.4x earnings, which is close to the peer average of 18.6x and well below the broader Capital Markets industry on roughly 36.3x. The stock therefore carries a similar headline valuation to direct peers, even though the sector as a whole changes hands at a much higher multiple.
The fair-value model that blends growth, margins, size and risk suggests a lower P/E than where GCM Grosvenor currently trades. On this framework, the shares screen as overvalued. Because third quarter 2026 results showed higher GAAP net income and fee related earnings, the recent profit strength already looks well reflected in the P/E investors are being asked to pay. If you own or are researching the stock, the key question is whether the business can keep justifying a premium to this tailored fair-value anchor over time. Explore the numbers behind GCM Grosvenor's P/E valuation.
The GCM Grosvenor Narrative: What Would Justify Today's Price?
GCM Grosvenor’s valuation question only really comes into focus once you spell out what kind of future the current P/E is pointing to. Simply Wall St Narratives do that work on the Community page by setting out the growth, margin and earnings paths that would need to play out for the stock to be worth materially more or materially less than today’s price. Where a single ratio or model offers one neat output, these walk through the assumptions behind that figure so you can watch over time whether the real business performance matches the story.
Bulls and bears looking at GCM Grosvenor are really debating how much of its fee and carry story is already baked into today’s price.
Bull case: 6% undervalued
The analyst consensus Narrative on Simply Wall St focuses on earnings power tied to alternatives fundraising and unrealized economics.
"Large embedded economics from unrealized carried interest of US$965m gross, with about US$493m attributable to GCM Grosvenor and US$35m to US$40m of unrealized ARS performance fees linked to positions such as SpaceX, represent future crystallization events that can lift earnings and fee-related margins when realized…"
Discover why this Narrative puts GCM Grosvenor at 6% undervalued.
Bear case: 7% overvalued
The bearish analyst Narrative on Simply Wall St leans on concerns about fee-paying AUM and the cost of technology investment.
"Non GAAP G&A and other expenses of US$23 million in Q1 2026 were slightly higher than expected in part due to faster AI related technology investment…"
Explore why this Narrative puts GCM Grosvenor at 7% overvalued.
One more angle on GCM Grosvenor that could shift your view
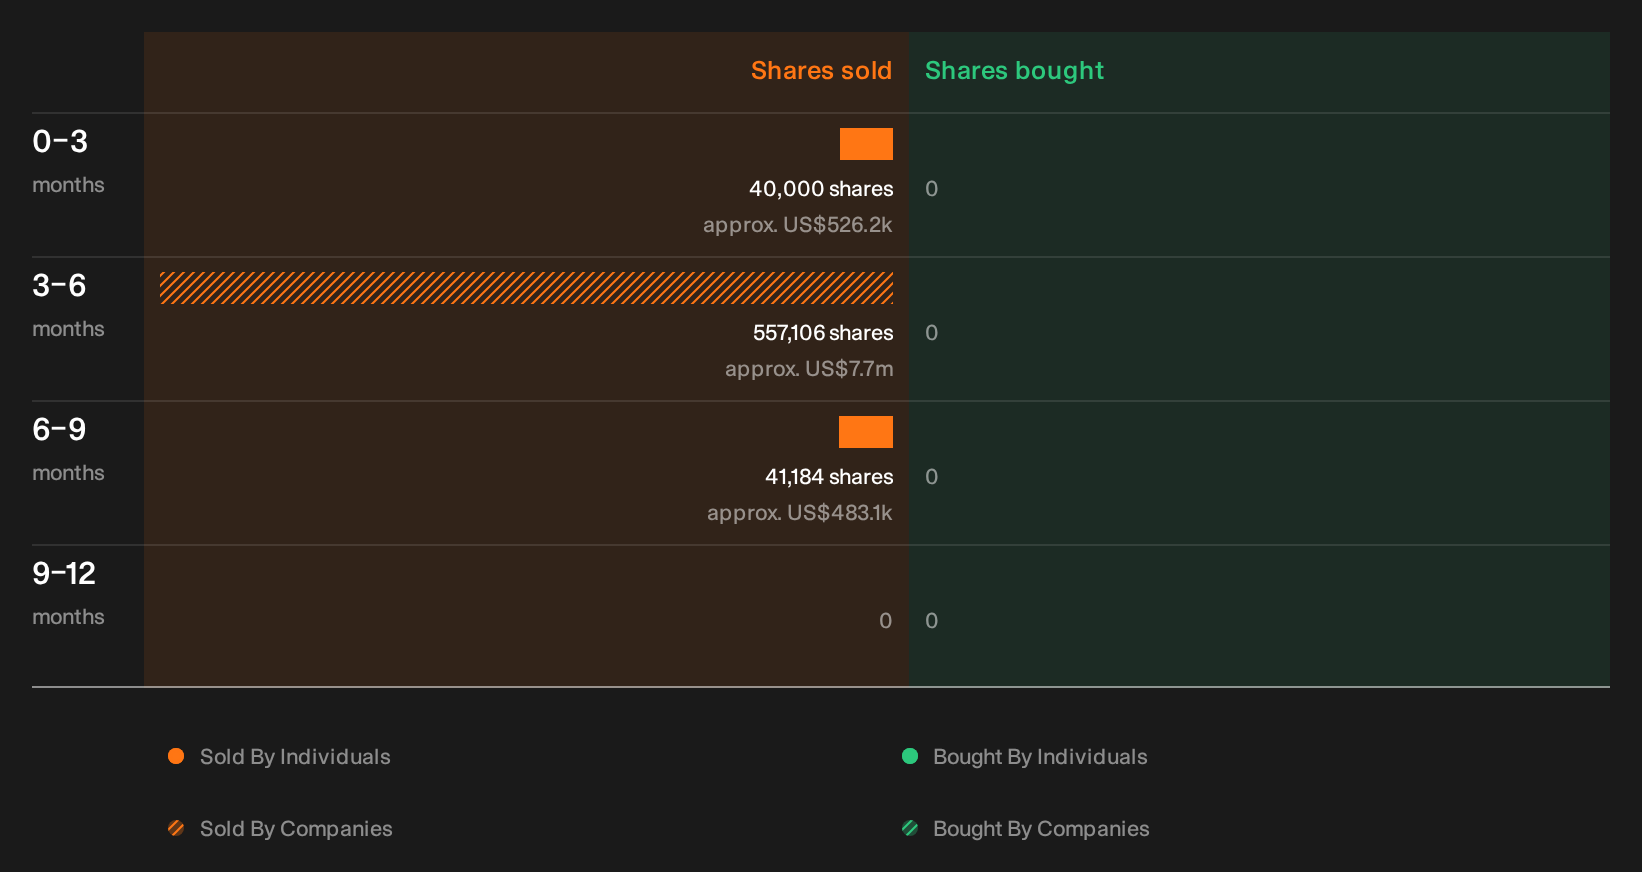
Valuation only tells part of the story for GCM Grosvenor, since recent insider trading activity has also been flagged by our checks and the individuals involved, the size of those trades and what they might signal are all left for you to unpack. See the recent insider selling flagged for GCM Grosvenor.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com