


UniFirst (UNF) highlighted income returns after its board approved higher quarterly cash dividends of $0.375 per common share and $0.300 per Class B share, both payable on December 15, 2026.
UniFirst now trades at US$238.50. While the share price has slipped over the past week and quarter, with 7 day and 90 day share price returns down 6.9% and 17.8%, respectively, the year to date share price return of 23.2% and 1 year total shareholder return of 56.8% point to momentum that has built over a longer horizon as investors respond to improving income and the higher dividend stream.
Scan for other dividend paying businesses with solid fundamentals by jumping into our curated list of 5 dividend fortresses alongside UniFirst's latest payout move.
After a sharp pullback from recent highs, but with richer dividends now locked in, does UniFirst still offer enough potential upside to justify the risk at US$238.50, or has the easy part of the rerating already played out?
Most Popular Narrative: 13% Undervalued
At a last close of $238.50, the analyst consensus Narrative on Simply Wall St points to a fair value near $273.33 for UniFirst. This frames the stock as modestly undervalued while tying the story tightly to execution on systems, new services and the proposed Cintas deal.
The main thing that has to go right is that UniFirst converts its heavy ERP and sales and service investments, along with the planned Cintas integration, into better profitability over time despite current cost and tariff headwinds.
UniFirst’s current valuation and this narrative’s fairly valued, bullish stance together imply that the share price already reflects meaningful long term benefits from digital transformation, higher organic growth and the proposed Cintas merger synergies.
See why 2 investors see UniFirst as 13% undervalued.
Result: Fair Value of $273.33 (UNDERVALUED)
Still, higher health care and legal expenses, along with ongoing tariff pressure on imported goods, could easily derail the upbeat UniFirst narrative investors are leaning on.
Find out about the key risks to this UniFirst narrative.
Another View: UniFirst Looks Expensive On Earnings
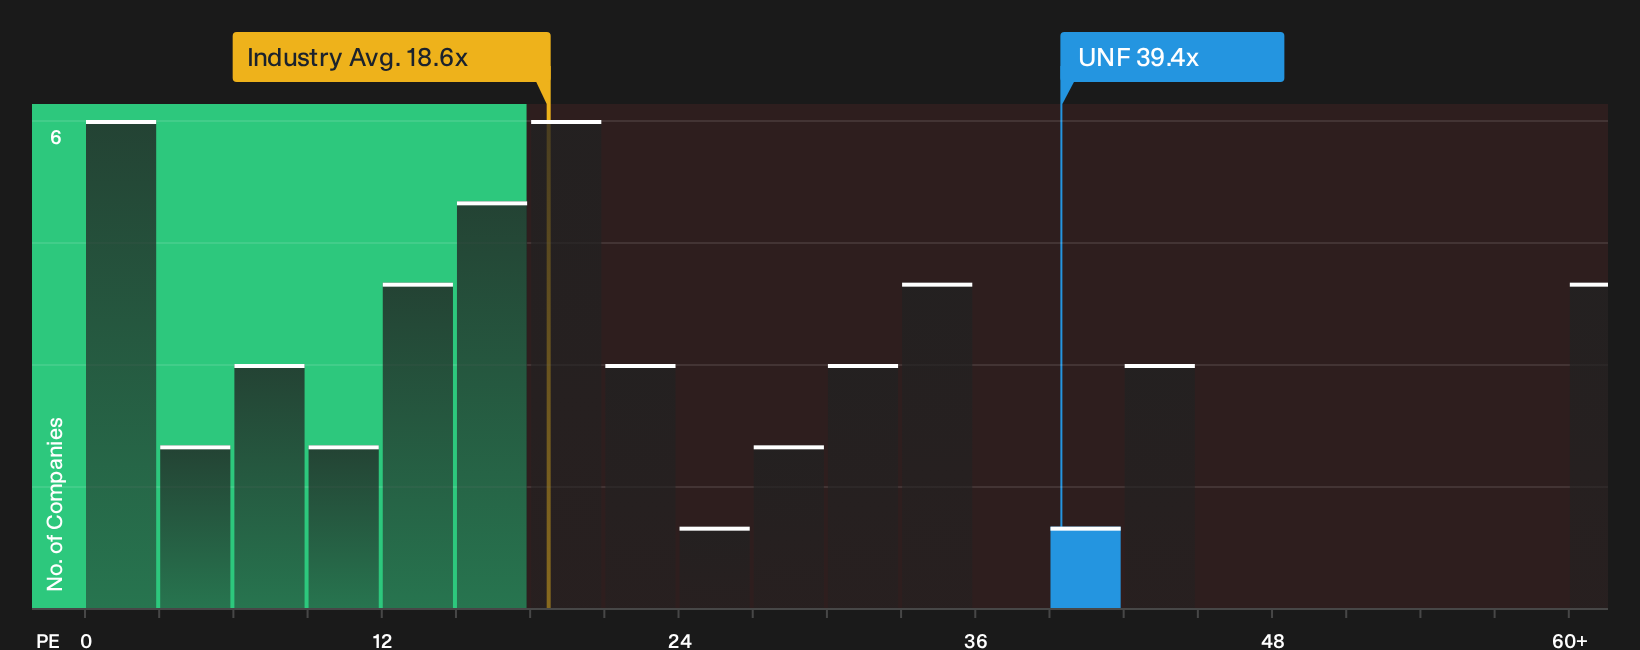
On cash flow assumptions, UniFirst screens as undervalued, yet the P/E ratio of 39.4x tells a different story. It sits well above the estimated fair ratio of 22.5x, the US Commercial Services industry at 18.6x, and peer average of 28.9x. That gap leaves investors weighing upside against valuation risk.
To see how those earnings multiples stack up against the underlying fundamentals in more detail, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around UniFirst is split, with clear positives sitting alongside flagged risks. Consider acting promptly, reviewing the underlying data, and weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond UniFirst?
If UniFirst has your attention, do not stop here. Fresh opportunities often sit just outside your current watchlist, and you will not want to miss them.
- Target steadier potential outcomes by focusing on businesses that pair resilience with financial strength through our 30 resilient stocks with low risk scores.
- Spot potential bargains early by scanning companies that combine quality fundamentals with attractive pricing using the 20 high quality undiscovered gems.
- Sharpen your income strategy by lining up high quality payers through the 5 dividend fortresses before the next round of distributions is set.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com