


- Marathon Petroleum reported third quarter 2026 revenue of US$56.5b and net income of US$7.4b, with earnings per share above US$26 from continuing operations and a 10% rise in its quarterly dividend to US$1.10 per share.
- Management is pairing recent profitability with multi site refinery upgrade projects that target higher value products and greater flexibility across domestic and export markets.
- This article explores how Marathon Petroleum's third quarter earnings shape its broader investment narrative and execution focused story.
Scan how Marathon Petroleum's latest refinery focused earnings story compares with other potential opportunities by reviewing the hand picked 41 power grid technology and infrastructure stocks in related energy infrastructure.
Marathon Petroleum Investment Narrative Recap
To own Marathon Petroleum, an investor needs to believe the refining system can keep running hard, capturing healthy spreads and turning large, complex plants into steady cash flow. The analyst consensus narrative on Simply Wall St already incorporates tight global capacity and solid execution, with expectations that earnings and revenue could trend lower from recent levels.
The key short term swing factor is how refining and marketing margins hold up after this very strong third quarter, especially with refinery upgrades shifting product mix toward diesel, jet fuel and premium gasoline. Policy risk around U.S. diesel exports and any squeeze on crude to product spreads remains the biggest operational threat.
The most directly relevant announcement to this earnings story is the 10% dividend increase to US$1.10 per share. That move accompanies very high recent profitability and indicates that Marathon Petroleum is comfortable committing more cash to regular shareholder payouts based on the current earnings base.
For catalysts, that larger dividend sits alongside active refinery projects at Galveston Bay, Garyville and Robinson, as well as MPLX midstream expansion, so cash demands are significant. Execution risk rises as the firm balances higher capital spending, a richer dividend and the possibility of softer refining margins if crude supply loosens or export policy tightens.
What Marathon Petroleum's Forecasts Are Really Pricing In
Marathon Petroleum's narrative projects US$140.2b in revenue and US$8.2b in earnings by 2029, based on analyst assumptions that revenue will decline 3.1% each year and that profits move from US$8.5b today to that US$8.2b level, which is a decrease of US$0.3b from current earnings.
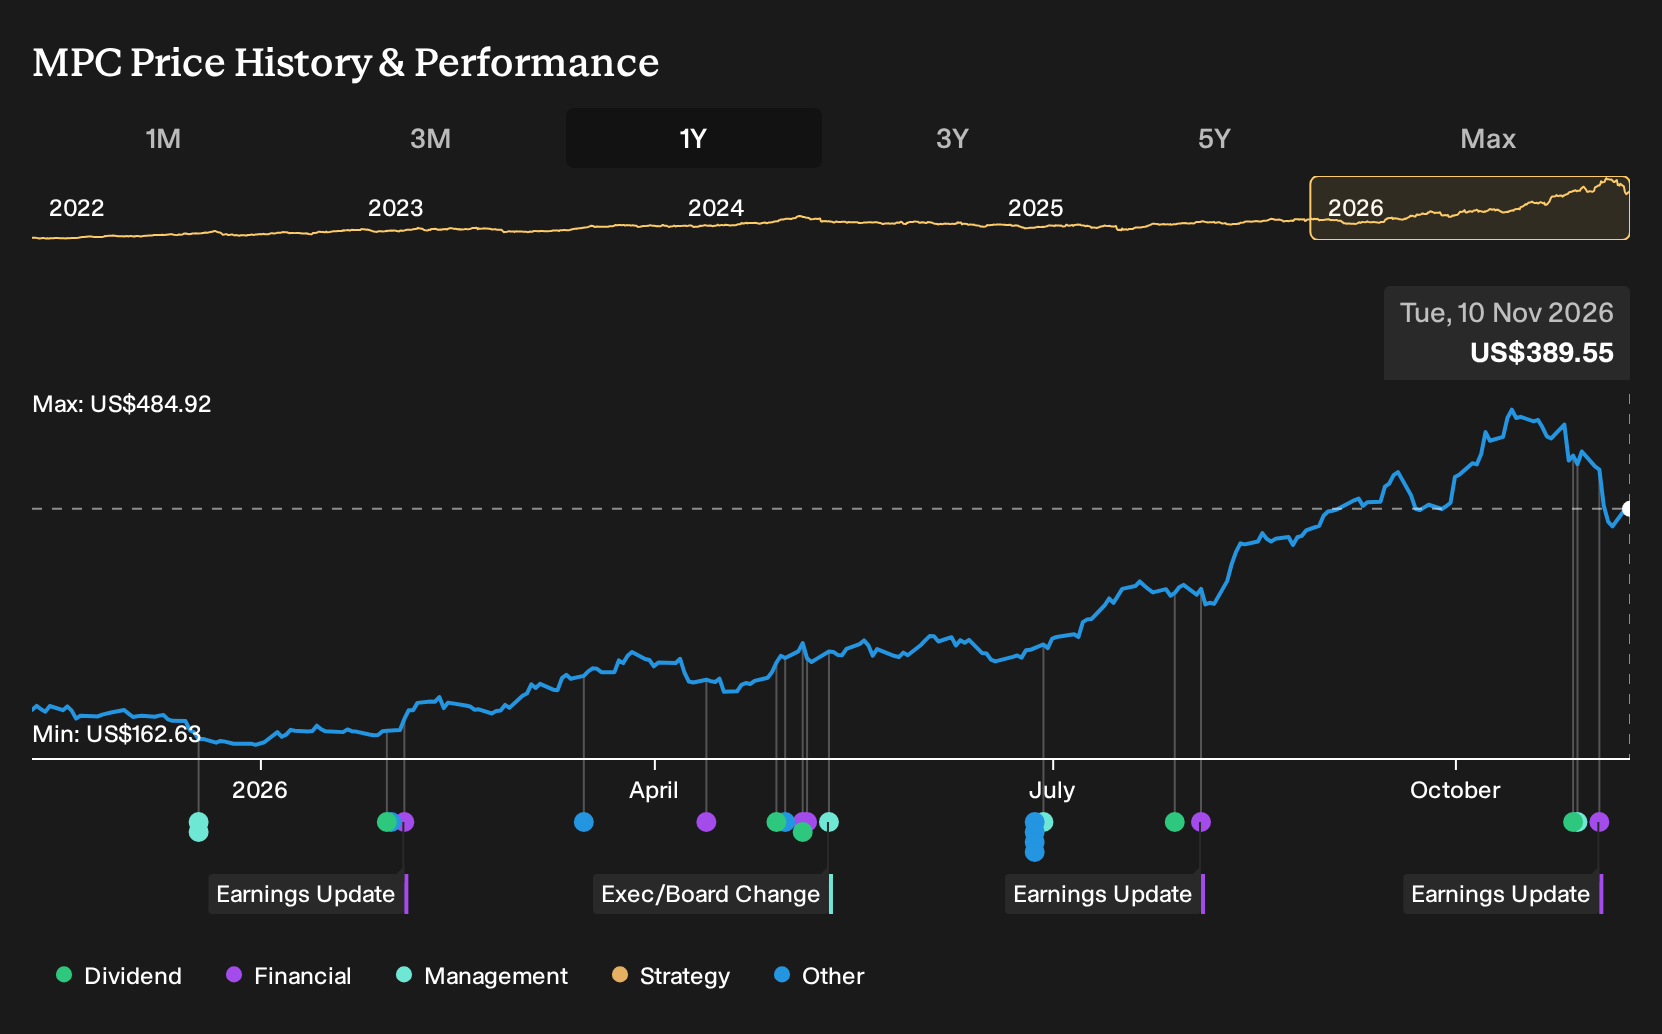
Uncover how Marathon Petroleum's fair value indicates an 18% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate angle focuses on capital project risk. The most optimistic Marathon Petroleum analysts were already pencilling in about US$196.8b of revenue and US$10.5b of earnings by 2029 before this third quarter jump in profit. You can treat these high conviction forecasts as one end of the range and explore how this latest report might shift them.
Explore 4 other Marathon Petroleum fair value estimates, including one that suggests there could be as much as 44% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marathon Petroleum research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Marathon Petroleum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marathon Petroleum's overall financial health at a glance.
Looking for more investment ideas beyond Marathon Petroleum?
If you want to put Marathon Petroleum in context and build a broader watchlist, use the Simply Wall St Screener to line it up against other listed businesses with different risk and return profiles.
- For investors who want quality and value working together, start with a focused group of companies showing strong fundamentals and potentially attractive pricing through the 36 high quality undervalued stocks.
- If balance sheet strength matters most to you, narrow the universe to businesses screened for conservative leverage and solid financial footing using the list of solid balance sheet and fundamentals (24 results).
- When income is a priority, look across companies that combine higher yield with resilience and see which ones make the cut via the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com