


- Bronstein, Gewirtz & Grossman, LLC has begun an investigation on behalf of investors in FirstCash Holdings after Q3 2026 results highlighted weaker operating income and lower gross transaction volume in the American First Finance segment, linked to merchant partner bankruptcies and a business mix shift.
- The pressure in American First Finance points to concentration and credit risk around merchant partners. This may reshape how FirstCash Holdings balances growth, underwriting discipline, and diversification within its consumer finance operations.
- Next, the focus shifts to how FirstCash Holdings' broader investment narrative holds up against the investigation tied to American First Finance underperformance.
Stress test your thesis on FirstCash Holdings against other lenders facing similar credit and concentration pressures by scanning our hand picked 30 resilient stocks with low risk scores that prioritize balance sheet resilience.
What Is FirstCash Holdings' Investment Narrative?
To own FirstCash Holdings, you need to be comfortable with a hybrid story. Most of the value still rests on a pawn network across the U.S., Latin America and the U.K., which throws off cash, recycles inventory quickly and does not require heavy capital expenditure per store. The newer American First Finance arm adds a more credit sensitive, merchant driven revenue stream. That is where the Q3 2026 disappointment and the Bronstein, Gewirtz & Grossman investigation are centered, tying the near term debate to underwriting discipline and partner quality.
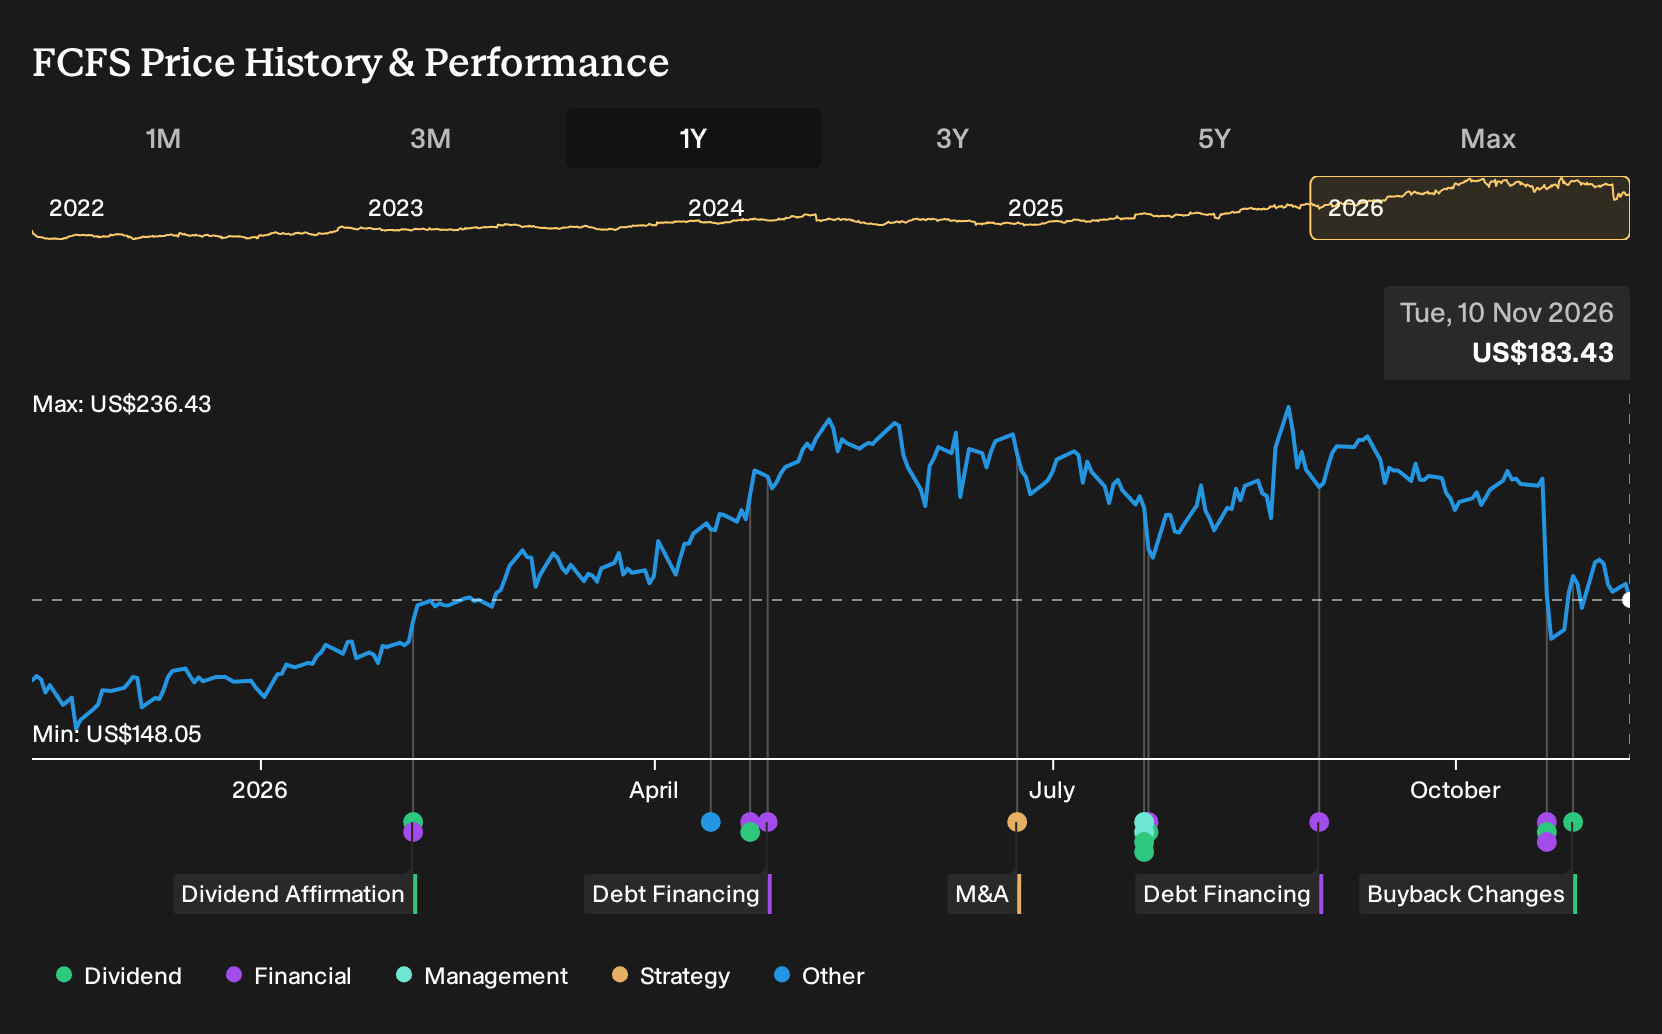
In the short term, the key questions are whether merchant concentration and bankruptcies at American First Finance stay contained and how management recalibrates growth, pricing and credit standards there. Recent share performance, with the stock down over the past month and quarter, suggests investors are already discounting higher risk around that unit. At the same time, FirstCash Holdings still reports group earnings growth forecasts of 17.05% a year and an 8.5% revenue growth outlook, alongside a 19.4x P/E that screens as rich versus consumer finance peers. The investigation fits directly into this tension between growth expectations, a high debt load and the need to prove the consumer finance portfolio can earn those multiples.
That said, one piece of the FirstCash Holdings story tends to get less attention, and it sits in the same bucket as the merchant and credit issues at American First Finance...
There's only one way to know the right time to buy, sell or hold FirstCash Holdings. Head to Simply Wall St's company report for the latest analysis of FirstCash Holdings's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community only shows two fair value views for FirstCash Holdings, yet they span a wide band from US$97.37 to US$247.50. That kind of spread signals sharply different opinions. When you layer the fresh investigation into American First Finance on top, you have a clear reason to compare several viewpoints before leaning on any single estimate.
Explore another FirstCash Holdings fair value estimate, including one that suggests as much as 47% downside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your FirstCash Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for FirstCash Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate FirstCash Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond FirstCash Holdings?
If the FirstCash Holdings story has you rethinking risk, it can help to widen the lens and compare it with other businesses that match your preferred profile on quality, valuation and balance sheet strength.
- For investors who care most about quality at a reasonable entry point, scan a curated set of 36 high quality undervalued stocks that pair stronger fundamentals with what may be undemanding prices.
- If reliable balance sheets sit at the top of your checklist, focus on companies from our list of solid balance sheet and fundamentals (24 results) to zero in on financial strength first.
- Income focused readers can concentrate on dependable cash returns by reviewing a hand picked group of 5 dividend fortresses that currently offer higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com