


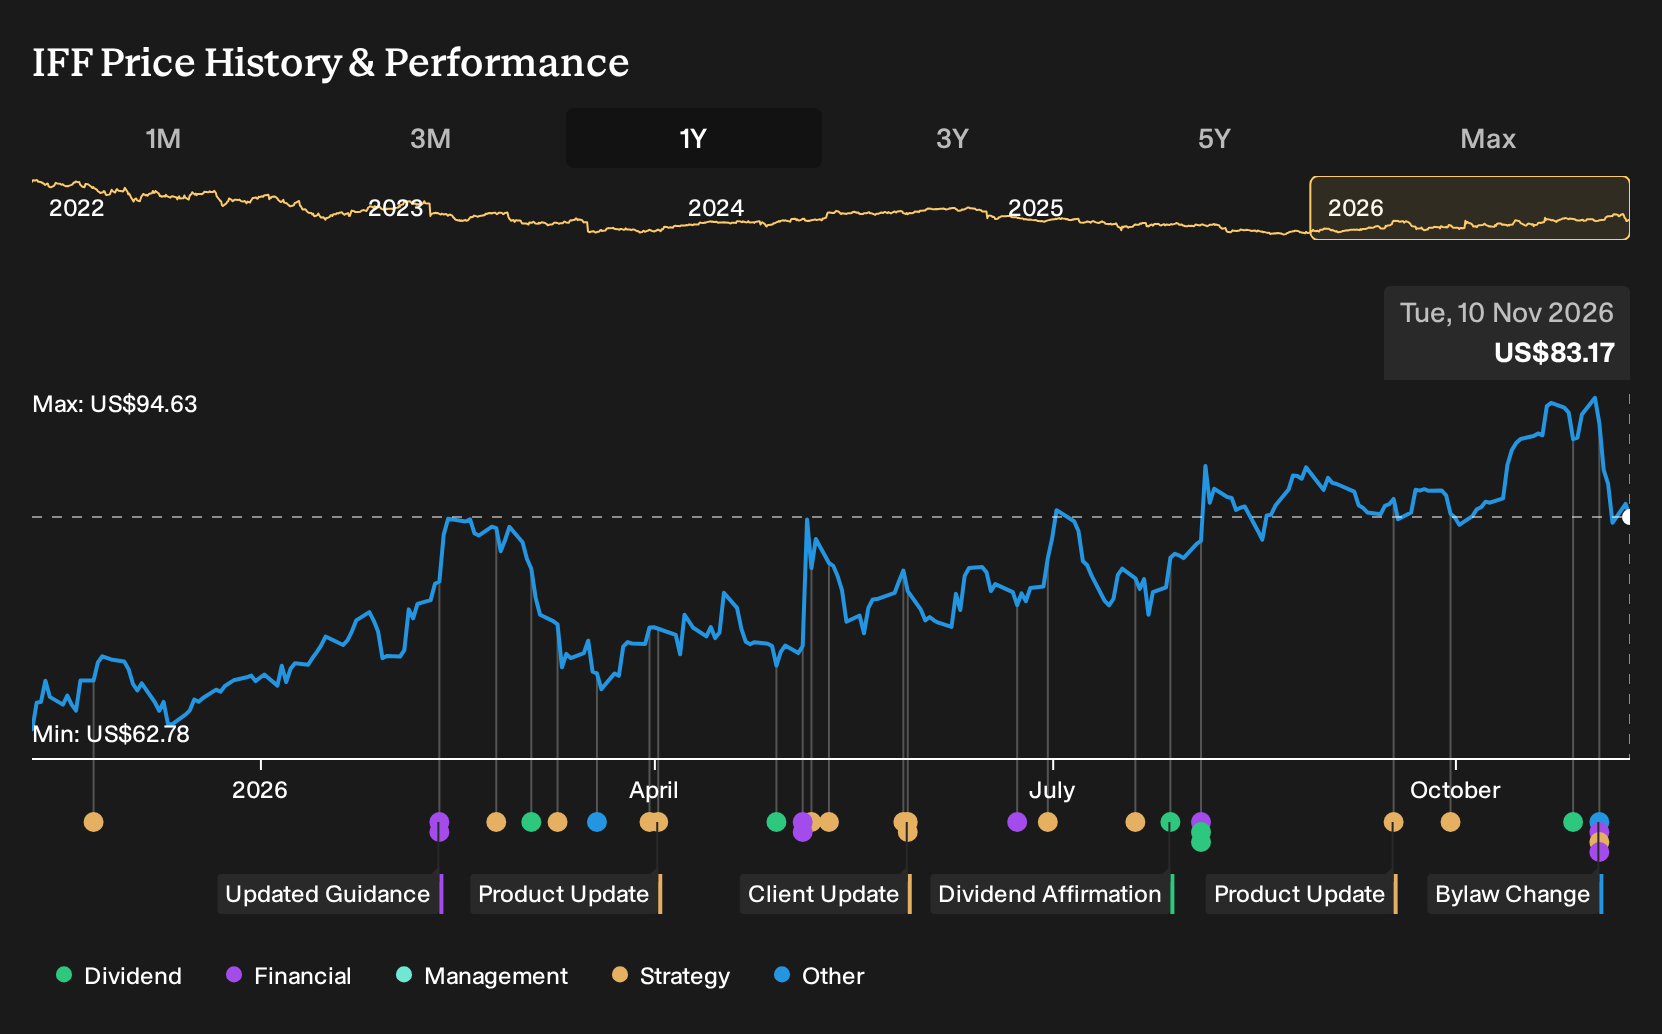
- International Flavors & Fragrances reported third quarter 2026 sales of US$1.94b with a net loss of US$55 million and recorded US$23 million of goodwill impairment. The board also updated bylaws to permit fully remote shareholder meetings and affirmed a US$0.40 quarterly dividend payable in January 2027.
- Despite weaker quarterly profitability and mixed regional performance, International Flavors & Fragrances raised full year 2026 sales guidance to a range of US$7.5b to US$7.6b, signaling management confidence in demand across its core Taste, Scent and Health & Biosciences activities.
- We will now look at how International Flavors & Fragrances' raised full year sales guidance could reshape the longer term investment narrative.
International Flavors & Fragrances Investment Narrative Recap
To stay invested in International Flavors & Fragrances, you need to be comfortable with a business that is still cleaning up its portfolio while dealing with choppy demand. The analyst consensus narrative on Simply Wall St leans on sharper focus in Taste, Scent and Health & Biosciences, as well as better use of R&D to improve margins over time. The raised US$7.5b to US$7.6b sales outlook points to management seeing enough demand support. The immediate swing factor remains how quickly weak regions and the Health segment can stabilise versus cost pressures and impairment charges.
The largest near term risk is that softer conditions in North America, China and parts of Health & Biosciences keep dragging on net margins even if sales hold near guidance. A reported quarterly net loss of US$55 million and US$23 million of goodwill impairment underline that earnings quality is still fragile. If mix, pricing and cost actions do not translate into cleaner profitability and cash generation soon, the execution gap against the current narrative on cost savings, R&D payback and balance sheet repair could stay wide.
The dividend affirmation of US$0.40 per share for January 2027 is the announcement that ties most directly into this setup. Cash payouts provide a tangible return stream while the turnaround plays out and signal that International Flavors & Fragrances intends to keep income on the table even as it works through impairments and restructuring. That said, Simply Wall St flags the dividend as not well covered by current earnings, so the real support comes from cash flow and the balance sheet rather than accounting profit.
For catalysts, that payout policy interacts with the broader plan to simplify the portfolio, remove roughly US$100m of stranded costs and apply more than US$1b of asset sale proceeds to debt reduction. If the business can keep funding the dividend while cutting leverage and sharpening margins in Taste, Scent and Health & Biosciences, investor focus is likely to remain on execution rather than capital strain. If cash generation weakens or international revenues fall faster than expected, the combination of ongoing losses, goodwill write downs and dividend commitments could compress management’s room to manoeuvre just as capacity projects in Health & Biosciences need funding.
International Flavors & Fragrances' current analyst narrative points to US$8.5b in revenue and US$897.6m in earnings by 2029, based on a forecast annual revenue decline of 7.9%, compared with earnings today of a US$1.0b loss. This implies an earnings swing of roughly US$1.9b if that 2029 consensus is met.
Uncover why International Flavors & Fragrances' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts legal risk front and center for International Flavors & Fragrances. Some of the highest analysts focus less on cost cuts and more on the chance that further antitrust or pricing actions absorb cash that was assumed to support about US$8.0b of revenue and US$1.2b of earnings by 2029. Those projections were set before this latest guidance and bylaw news, so you may want to compare them with your own expectations and see how opinions might shift as remote shareholder meetings, fresh impairment charges and the new sales outlook are incorporated into updated research.
Explore 2 other International Flavors & Fragrances fair value estimates, including one that suggests as much as 30% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your International Flavors & Fragrances research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for International Flavors & Fragrances. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate International Flavors & Fragrances' overall financial health at a glance.
Looking For More Investment Ideas Beyond International Flavors & Fragrances?
If this update on International Flavors & Fragrances has you reassessing your portfolio mix, it can help to line it up against other businesses with different income profiles, balance sheet strength and risk levels using the Simply Wall St Screener.
- For investors who want income to play a bigger role, you could review higher yielding companies screened as 5 dividend fortresses that still pass a basic quality and payout sustainability check.
- If capital preservation matters most to you right now, look across 30 resilient stocks with low risk scores that pair relatively resilient fundamentals with lower overall risk scores.
- To broaden your opportunity set beyond widely followed tickers, scan 20 high quality undiscovered gems that combine stronger balance sheets and fundamentals with less attention from the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com