


- Rockwell Automation reported fourth quarter sales of US$2,332 million and net income of US$346 million, with full year fiscal 2026 net income of US$1,409 million and diluted EPS from continuing operations of US$12.54.
- Alongside profit strength, Rockwell Automation lifted its quarterly dividend to US$1.45 per share and issued fiscal 2027 guidance that indicates higher reported sales and earnings, supported by productivity efforts and international demand.
- We will now look at how Rockwell Automation's profitability and 2027 guidance shape the existing investment narrative around the stock.
Compare Rockwell Automation's earnings strength with other industrial automation players by scanning the hand picked 91 robotics and automation stocks that could benefit from similar spending and productivity themes.
Rockwell Automation Investment Narrative Recap
To own Rockwell Automation, you need to be comfortable with a pure-play automation specialist that leans heavily on its installed base, recurring software and productivity gains. According to TradingClimbers, an investor in the Simply Wall St Community, the most important near term catalyst is execution against guidance as volumes recover. The latest earnings, with US$8.99b in sales and US$12.54 EPS, support that story.
The biggest risk TradingClimbers flags is valuation sensitivity if orders or margins disappoint, especially with a rich P/E and high debt. Fiscal 2027 guidance and recent profit strength help ease that concern slightly, but do not remove exposure to delayed large projects or regional demand swings.
The dividend increase to US$1.45 per share looks most relevant right now. It ties directly into whether Rockwell Automation can keep turning productivity work and international demand into reliable cash returns. For investors watching income plus growth, a higher regular payout can make short term execution on margins and free cash flow feel even more important.
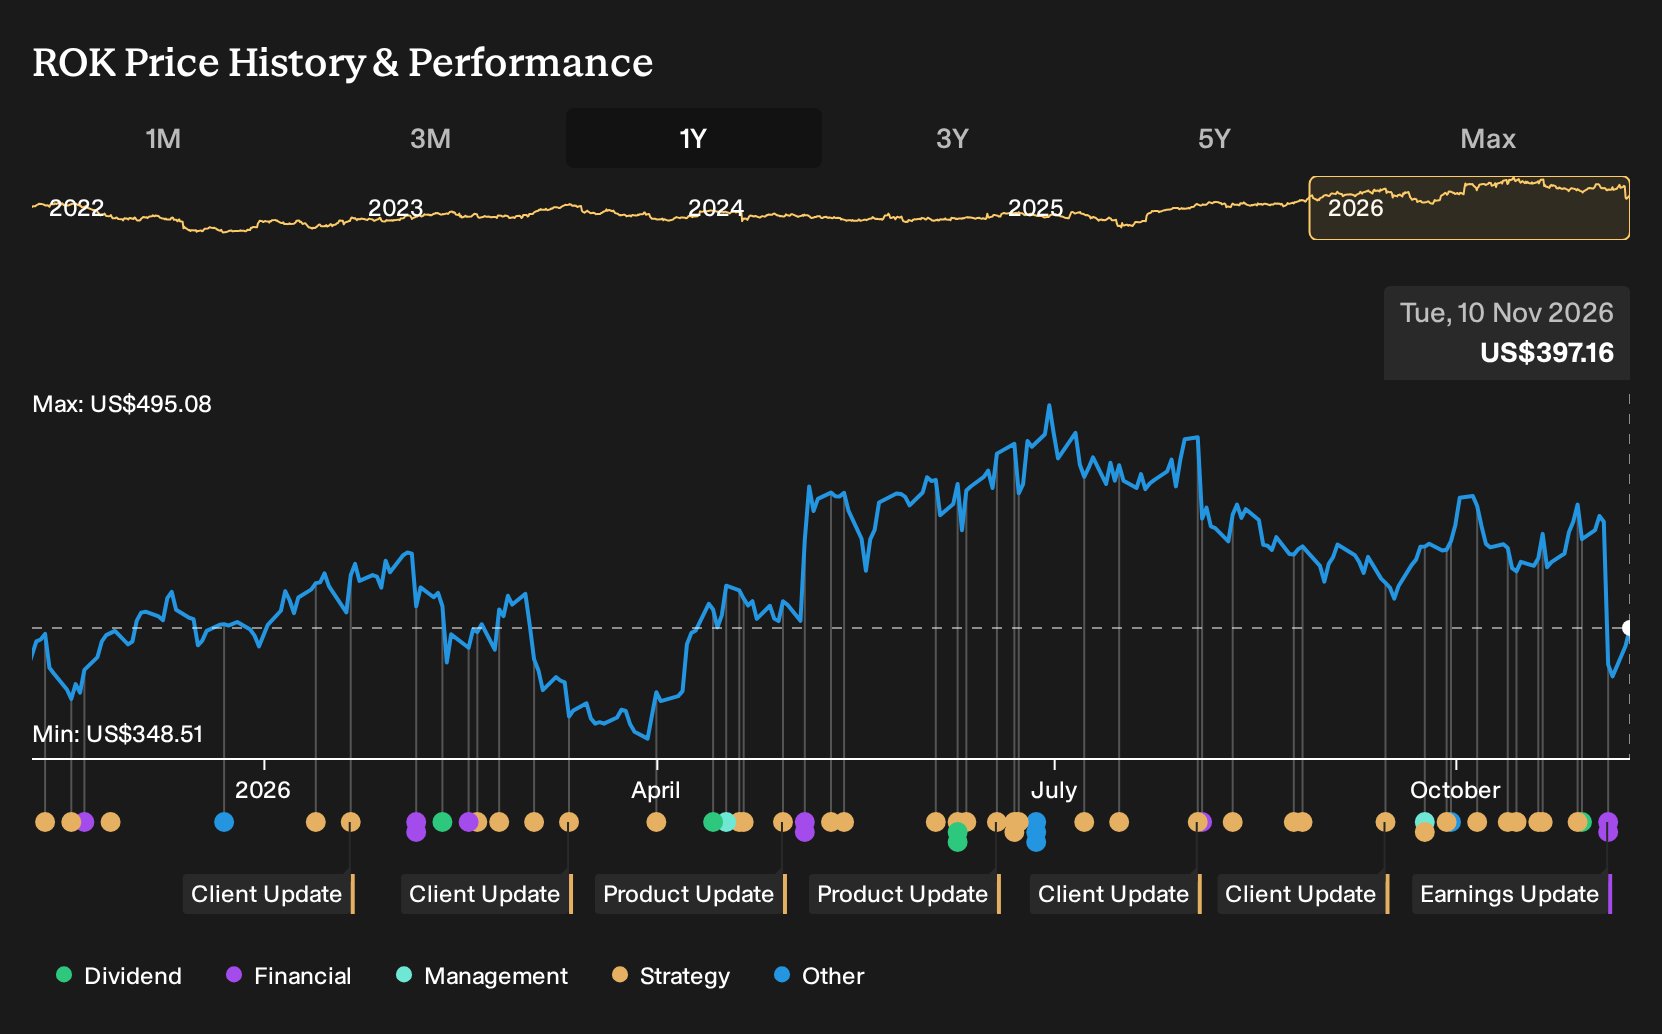
This higher dividend also interacts with the catalysts TradingClimbers laid out. A richer distribution stream can amplify share price reactions if earnings or order trends slip, because the stock already trades above some fair value estimates and underperformed the broader US market over the past year. Execution on the 2027 EPS range of US$13.78 to US$14.78 becomes central to sustaining that higher cash commitment.
TradingClimbers' fair value of US$350.75 for Rockwell Automation rests on an expectation of revenue rising 4.1% a year and profits settling at a 13.4% margin, which together provide what the narrative describes as a reasonable long-run earnings power for the business.
Uncover why Rockwell Automation's fair value indicates a 12% potential downside to its current price, suggesting that this premium may not be sustainable.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Rockwell Automation’s mix shift toward higher margin software, arguing that earnings could reach about US$2.2b on US$11.2b of revenue by 2029, compared with roughly US$1.4b today. You can treat that as a stretch scenario and then weigh how this fresh 2027 guidance might reshape those expectations.
Explore 3 other Rockwell Automation fair value estimates, including one that suggests as much as 17% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Rockwell Automation research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rockwell Automation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rockwell Automation's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rockwell Automation?
If Rockwell Automation has sharpened your interest in productivity, cash generation and capital discipline, it can help to widen the lens and compare it with other businesses that share similar financial strengths or different risk profiles.
- For investors who want quality at a marked down entry point, scan a curated 36 high quality undervalued stocks that combine stronger fundamentals with prices that sit below many intrinsic value estimates.
- If you care most about resilience and capital preservation, focus on a hand picked pool of 30 resilient stocks with low risk scores that score well on business stability and balance sheet strength.
- To broaden the opportunity set beyond widely followed large caps, review a targeted group of 20 high quality undiscovered gems that pair healthy financial traits with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com