


TKO Group Holdings (TKO) is back in focus after reporting third quarter results, lifting full year 2026 revenue guidance, and securing a Zacks Rank 1 upgrade that reflects higher earnings estimates.
Recent trading reflects that shift in sentiment. The share price is now at US$199.22, with a 7 day share price return of 6.42% and a 30 day share price return of 11.92%, pointing to building momentum after a year to date share price decline of 3.73%. At the same time, the 1 year total shareholder return of 12.63% and very large 5 year total shareholder return suggest longer term holders in TKO Group Holdings have already seen substantial value creation.
Scan how TKO Group Holdings compares with other media and entertainment players showing strong earnings trends and recent price momentum by reviewing the hand picked 36 high quality undervalued stocks in this space.
After TKO Group Holdings jumped on upgraded earnings views, analysts now peg fair value well above the current US$199.22. Is that discount a genuine margin of safety, or already fully earned by recent enthusiasm?
Most Popular Narrative: 15% Undervalued
On Simply Wall St, the analyst consensus Narrative pegs fair value for TKO Group Holdings at $234.39 compared with the last close of $199.22, pointing to a modelled upside that rests on media rights, margin expansion and capital returns.
Embedded step ups in long-term media rights for UFC with Paramount and WWE with ESPN and Netflix, alongside annual escalators and broader distribution, are set to structurally lift high-margin contractual revenue and expand EBITDA margins and earnings visibility from 2026 onward.
See why 8 investors see TKO Group Holdings as 15% undervalued.
The analyst consensus Narrative on Simply Wall St builds this view using a discount rate of 8.96%, an assumed revenue growth rate of 12.0% and a profit margin of 14.85%, then applies a future P/E of 17.23x to those earnings. That framework implies a fair value of $234.39 for TKO Group Holdings, which sits above the current share price yet still below the $275.00 high analyst target, and above the $185.00 low target that anchors the more cautious end of the range.
The same Narrative assumes earnings could reach $1.1b by around June 2029 if those margin and growth inputs hold, with analysts also building in 7.0% annual share count reduction over the next three years through buybacks. That combination of projected profit expansion and shrinking share base is what needs to line up with your own expectations if you are using the $234.39 figure as a reference point rather than an outcome.
Result: Fair Value of $234.39 (UNDERVALUED)
Still, this TKO Group Holdings narrative depends on streaming partners and site fees, both of which could be pressured if platforms or host cities pull back.
Find out about the key risks to this TKO Group Holdings narrative.
Another View: What TKO Group Holdings’ Earnings Multiple Signals
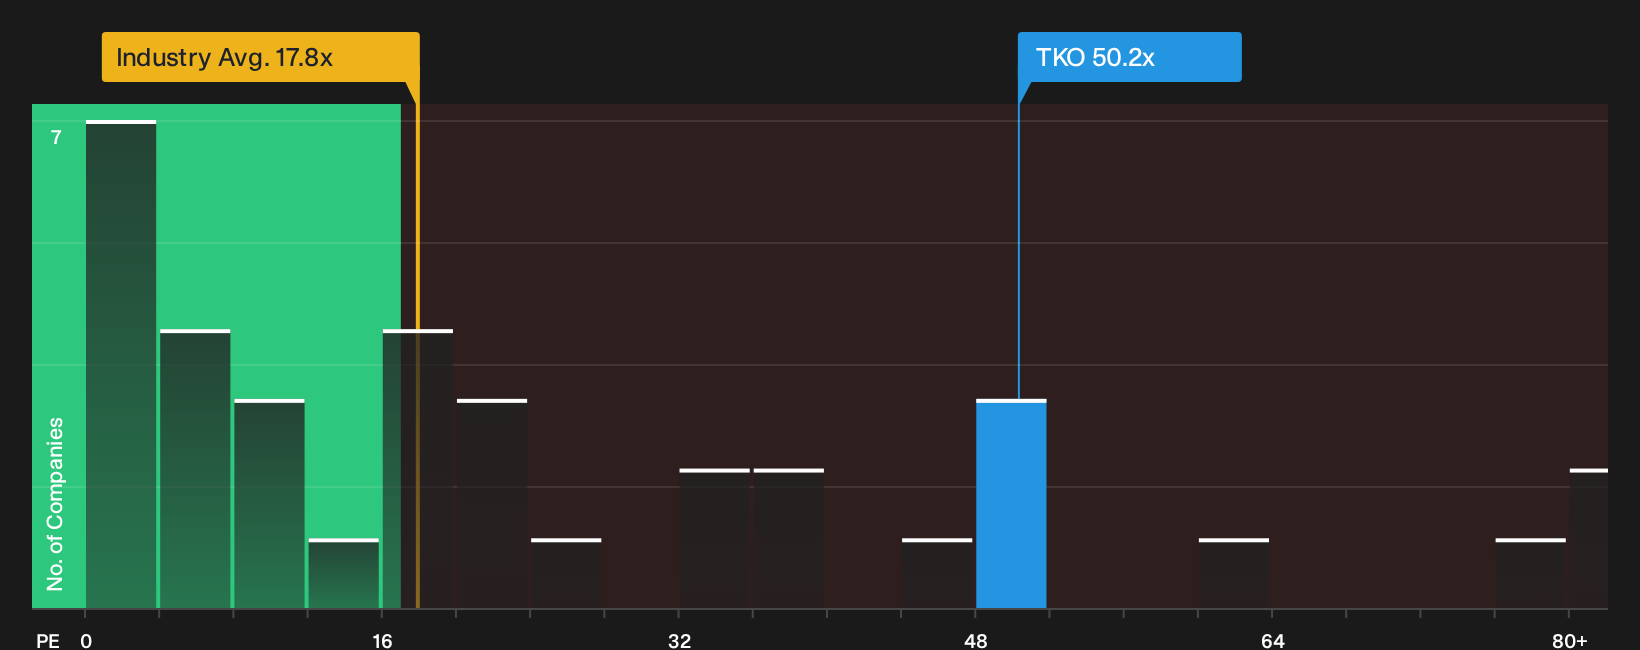
The cash flow model paints TKO Group Holdings as attractive, yet the current P/E of 50.2x tells a different story. That level is well above both the US Entertainment industry at 17.8x and the 34.2x fair ratio that the market could move toward. This raises the question of how much optimism is already priced in.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early inflection: either way, if you care about TKO Group Holdings it pays to move quickly and test the numbers yourself, starting with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond TKO Group Holdings?
If TKO Group Holdings has sharpened your focus, do not stop here. Broaden your watchlist with fresh ideas grounded in clear fundamentals and disciplined filters.
- Target potential opportunities by scanning the 9 elite penny stocks with strong financials that already show stronger financial underpinnings than the typical low priced stock.
- Prioritise quality at a sensible entry point by reviewing the 20 high quality undiscovered gems that pair healthy fundamentals with underfollowed market attention.
- Seek more stability during rough markets by focusing on the 30 resilient stocks with low risk scores that pass strict balance sheet and risk scoring checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com