


- KBR reported third quarter 2026 sales of US$2,028 million and net income of US$133 million, reaffirmed full year revenue guidance, and advanced the spin off of its Mission Technology Solutions business into Trinzic while adding new engineering and AI driven contracts.
- The combination of Trinzic board appointments, the West Qurna 1 low pressure gas capture work in Iraq, and wider KBR INSITE deployments shows KBR leaning into national security, gas infrastructure and digital optimization themes across several regions.
- We will now explore how KBR's progress on the Trinzic spin off could reshape the existing investment narrative around cash flow visibility.
Scan beyond KBR and this earnings season by reviewing 53 AI infrastructure stocks, a group that, like Trinzic and KBR INSITE, is tied to defense, energy systems, and industrial AI deployments.
KBR Investment Narrative Recap
To own KBR, you need to believe the firm can keep turning its government and energy transition backlog into steady earnings while managing contract churn. The analyst consensus Narrative on Simply Wall St leans on that idea of high revenue visibility. Third quarter 2026 results, with US$2,028 million in sales and US$133 million in net income, support that execution story for now.
The near term swing factor is how cleanly KBR executes the Trinzic separation while keeping Government Solutions and Sustainable Technology Solutions delivering on awards. The biggest risk remains contract volatility and protest delays, especially after the HomeSafe Alliance experience. The latest earnings and guidance reaffirmation do not materially change that risk reward balance.
The clearest link to the current catalyst set is the Trinzic board announcement. KBR is preparing to separate Mission Technology Solutions into a stand alone Trinzic entity in early 2027, with an eight member board led by retired Lt. Gen. Wendy M. Masiello and CEO designate Michael LaRouche, subject to final KBR board approval.
For you, this goes straight to the cash flow visibility question that sits behind the spin. If Trinzic successfully focuses on national security and space contracts while the remaining KBR leans into energy transition, digital tools such as KBR INSITE and long duration OpEx work, the market can assess each risk profile more cleanly. Execution slippage on this timetable would be a key watchpoint.
KBR's current earnings are US$423.0 million, and analysts collectively expect this to reach US$487.6 million by 2029. This represents a rise of about US$64.6 million, based on forecasts that include revenue growth of 6.0% per year and projected 2029 revenue of US$9.2b.
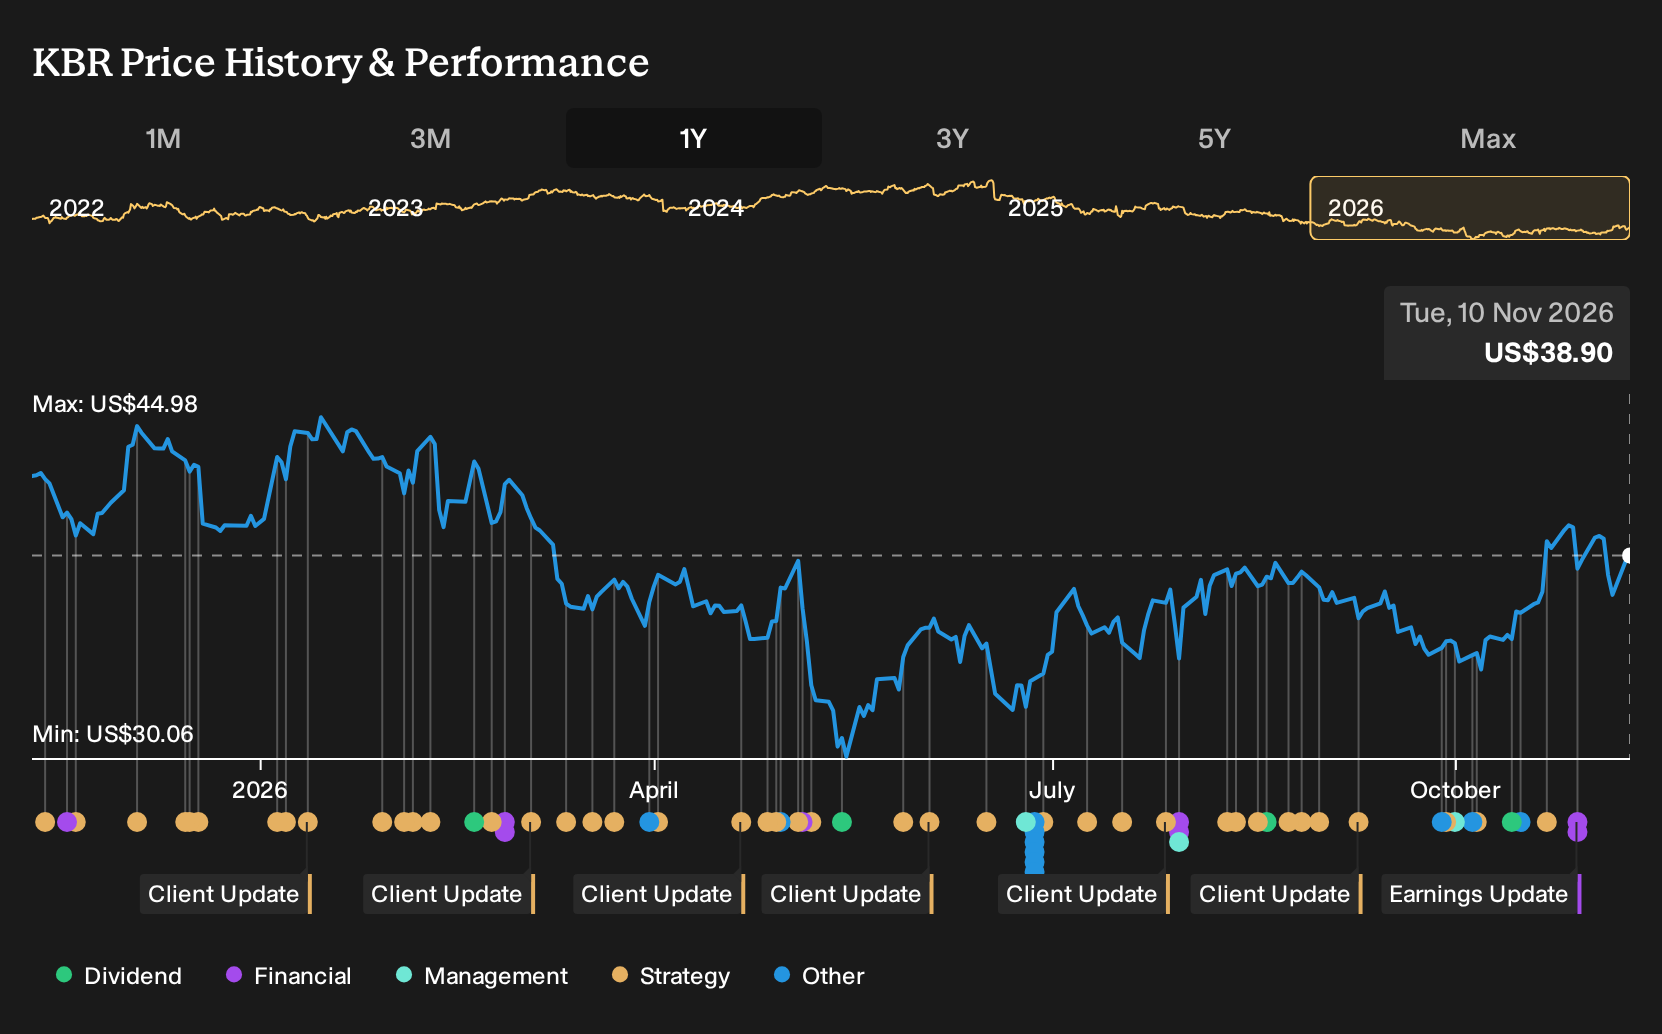
Uncover why KBR's fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate story focuses on the Trinzic spin as a risk rather than a clean unlock. The most cautious analysts were modelling KBR revenue of about US$9.0b and earnings near US$431.2 million by 2029, which is far below the US$487.6 million consensus. That gap shows how sharply opinions can differ, and the fresh earnings and guidance reaffirmation may push some of these views to adjust.
Explore 4 other KBR fair value estimates, including one that suggests there could be as much as 13% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your KBR research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for KBR. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KBR's overall financial health at a glance.
Looking For More Investment Ideas Beyond KBR?
If the KBR story has sharpened how you think about contracts, balance sheets, and cash generation, you can apply that same lens to a wider watchlist. The Simply Wall St Screener lets you quickly sort through different groups of companies so you can line up alternatives that match your own risk and income priorities.
- For investors who want potential upside with some financial resilience, start with a 20 high quality undiscovered gems that blend strong fundamentals with lower market attention.
- If capital preservation and steadier business profiles matter most to you, focus on 30 resilient stocks with low risk scores that score well on resilience metrics.
- For those who care about financial strength before anything else, filter for a list of solid balance sheet and fundamentals (24 results) and use that as the backbone of your long list.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com