


UGI (UGI) just rewrote its lending playbook. The utility signed a Second Amendment to its credit agreement that lifts total revolving commitments and pushes key debt maturities further out for investors watching liquidity.
Against that backdrop, UGI’s share price sits at US$37.54 and has gained 6.95% over the past 90 days. Its 1 year total shareholder return of 13.01% and very large 3 year total shareholder return suggest momentum has been building rather than fading.
See how UGI’s liquidity reset compares with its peers by reviewing a curated group of utilities with robust balance sheets through the list of solid balance sheet and fundamentals (24 results)
After that credit refresh and a 3 year total shareholder return that is very large, the real tension is simple: Does UGI’s recent price already reflect fair value, or do the valuation ranges still leave a meaningful gap?
Most Popular Narrative: 13% Undervalued
UGI’s last close at $37.54 sits below the analyst consensus Narrative fair value of $43.25, which reflects a 13% discount based on a 7.24% discount rate and detailed earnings and cash flow forecasts from the analyst consensus Narrative on Simply Wall St.
Implementation of the Pennsylvania gas rate settlement that phases in a US$65 million annual revenue increase between October 2026 and October 2027, raises the residential customer charge to US$20 by 2027, and introduces a Weather Normalization Surcharge pilot can support steadier UGI utility revenue and earnings visibility through at least early 2029.
See why 34 investors see UGI as 13% undervalued.
Result: Fair Value of $43.25 (UNDERVALUED)
Still, parts of the UGI story can break. Prolonged weakness in Midstream and Marketing earnings, or further safety related penalties in Pennsylvania, could quickly undermine that 13% undervaluation case.
Find out about the key risks to this UGI narrative.
Another View: UGI Through The Cash Flow Lens
There is a sharp counterpoint to the analyst fair value of $43.25 for UGI. The Simply Wall St DCF model values the stock at $14.29 per share, which implies UGI at $37.54 screens as expensive on that cash flow based approach rather than undervalued.
This gap between earnings based fair value and the DCF output raises a practical question for investors. Which yardstick do you trust more when future cash generation and discount rates pull the story in opposite directions?
Look into how the SWS DCF model arrives at its fair value.
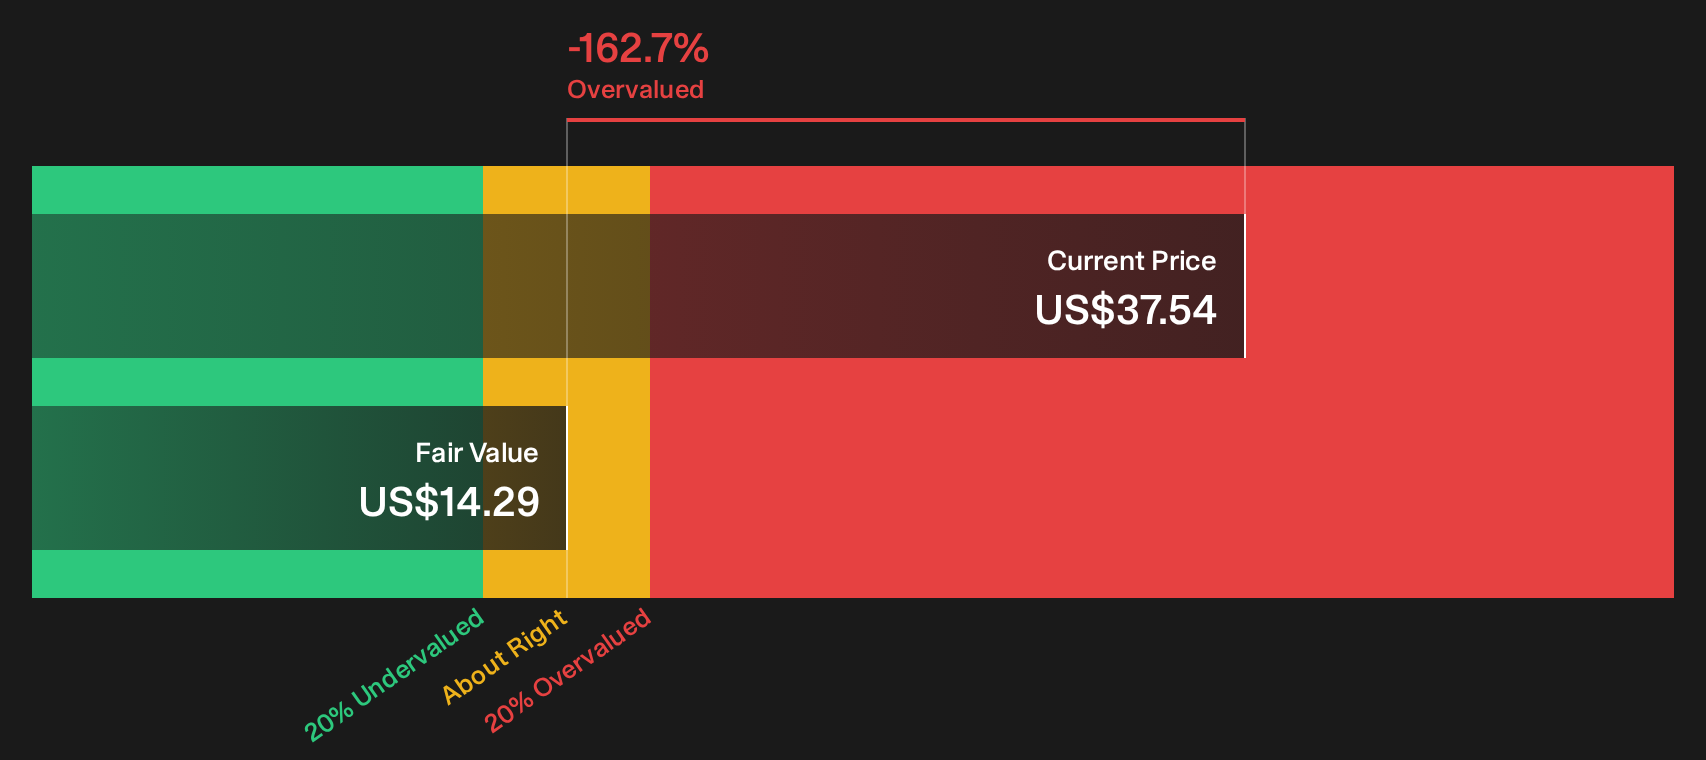
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out UGI for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on UGI’s value only matter if you use them. Review the full data set, weigh the upsides against the concerns, then decide where you land with the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond UGI?
If UGI has sharpened your focus on valuation, do not stop here. Broaden your watchlist with a few targeted stock sets that could refresh your opportunity pipeline.
- Target potential mispricings by scanning a curated pool of companies that look attractively valued on quality and fundamentals using the 36 high quality undervalued stocks.
- Prioritise resilience by reviewing a group of businesses with relatively low risk profiles and sturdier fundamentals through the 30 resilient stocks with low risk scores.
- Hunt for lesser known opportunities by checking a focused set of financially sound smaller players using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com