


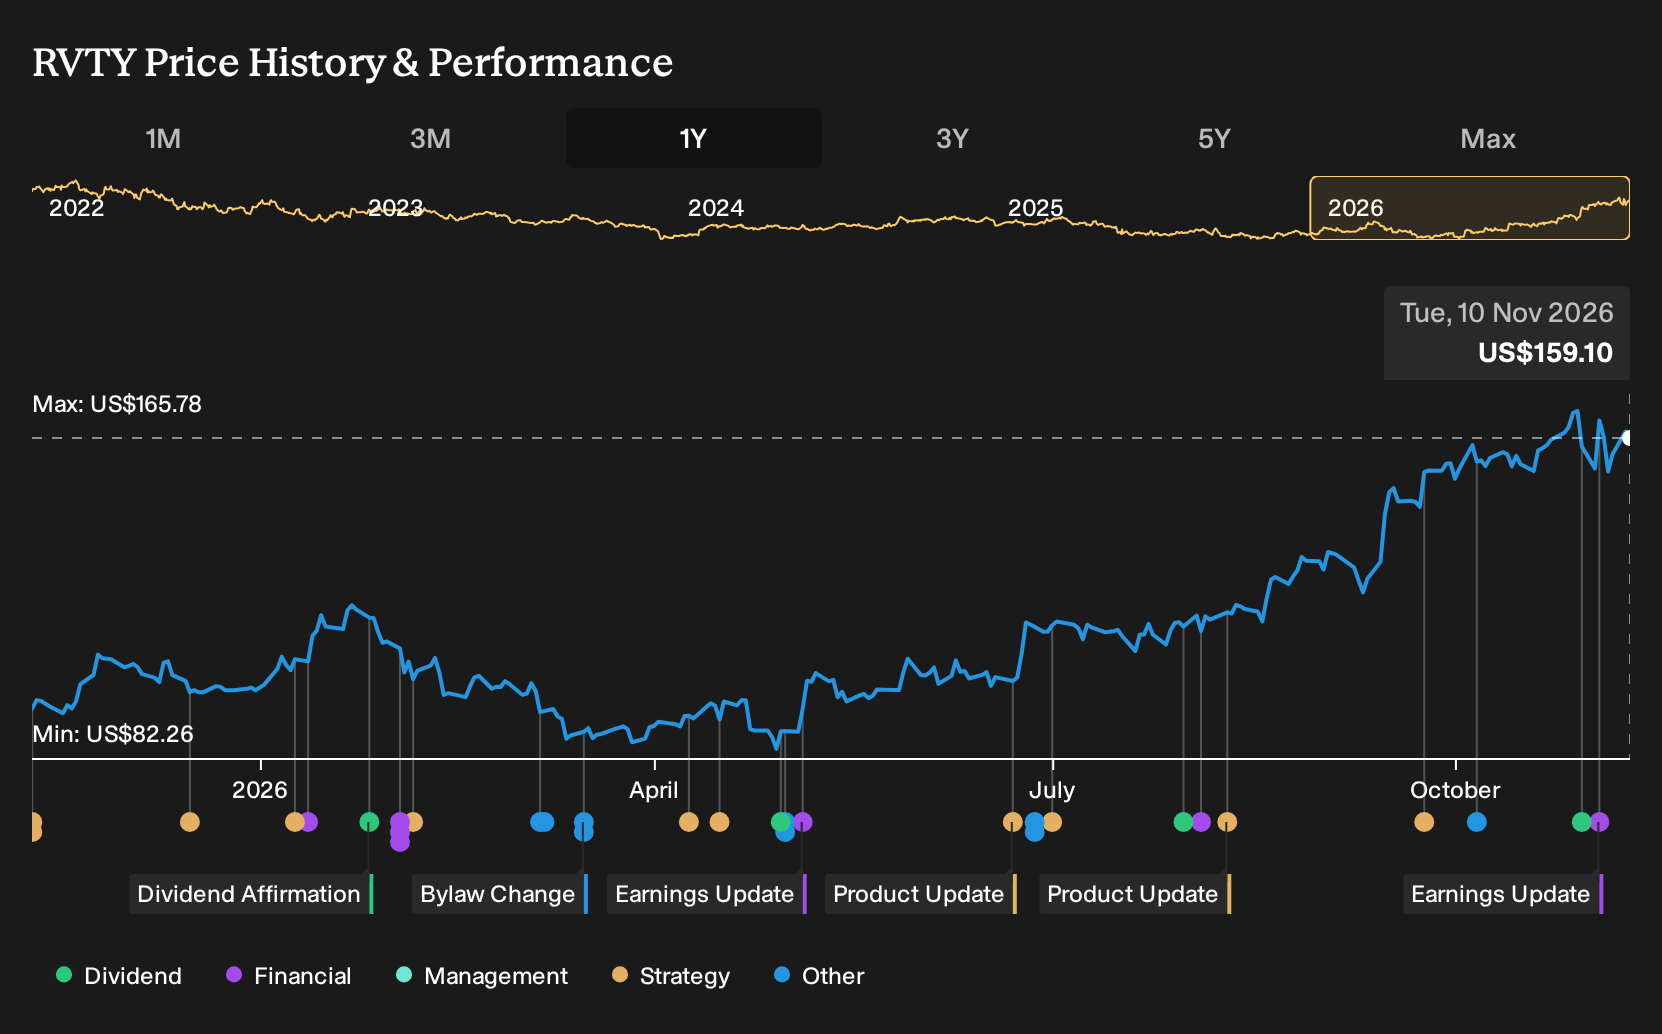
- Revvity reported third quarter 2026 sales of US$728.9 million and net income of US$62.3 million, with diluted EPS from continuing operations of US$0.56, and the board affirmed a regular quarterly dividend of US$0.07 per share payable in February 2027.
- The combination of higher quarterly earnings and ongoing cash returns through dividends highlights how Revvity is converting recent operating performance into shareholder distributions.
- Attention now shifts to how Revvity's stronger quarterly earnings feed into the existing investment narrative around margins, software, and diagnostics.
See how Revvity's combination of earnings progress and steady dividends compares with hand-picked healthcare peers by reviewing list of solid balance sheet and fundamentals (24 results) in the same space.
Revvity Investment Narrative Recap
To own Revvity, you need to be comfortable with a story built around modest top line progress feeding into better earnings, as outlined in the analyst consensus Narrative on Simply Wall St. The third quarter update, with higher sales and net income versus last year, broadly supports that operating thesis rather than rewriting it.
The near term swing factor still looks tied to execution in Signals software, reproductive health and ex China immunodiagnostics, plus keeping margins in the upper 20s. The biggest operational risk remains that revenue growth stays relatively soft while the P/E multiple is high, which would leave little room for execution hiccups.
The most relevant update here is the third quarter 2026 earnings report. Management reported sales of US$728.9 million and net income of US$62.3 million for the quarter, with diluted EPS from continuing operations of US$0.56 compared with US$0.41 a year earlier, alongside nine month figures that also showed higher sales and profit.
For investors watching catalysts such as Signals ARR growth, reproductive health contracts and the China immunodiagnostics exit, this set of numbers gives more detail on how Revvity is translating that story into the income statement. The print also helps frame risk, since strong earnings paired with a rich P/E leave less margin for disappointment if those drivers slow.
Revvity's current analyst storyline points to forecast revenues of US$3.4b and earnings of US$616.3 million by 2029, which would require 5.2% yearly revenue growth and an earnings increase of about US$363.5 million from the US$252.8 million reported today.
Uncover why Revvity's fair value indicates a 3% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate angle on Revvity leans heavily on Signals software as the wild card. The most optimistic analysts were pencilling in US$3.5b of revenue and US$739.4 million of earnings by 2029, well above consensus, on the view that AI driven contracts could ramp faster. This quarter’s earnings and dividend decision may prompt those projections to shift. Readers can use that spread in expectations as a reminder that opinions on Revvity vary widely and are worth comparing before making any move.
Explore 2 other Revvity fair value estimates, including one that suggests as much as 16% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider your own analysis and judgment.
- A great starting point for your Revvity research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Revvity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Revvity's overall financial health at a glance.
Looking for more investment ideas beyond Revvity?
If Revvity has sharpened your thinking about quality, risk and income, it can be useful to line that up against a broader watchlist using the Simply Wall St Screener.
- For investors who want potential upside paired with solid fundamentals, scan through a hand picked group of companies using the 20 high quality undiscovered gems.
- If capital preservation and steadier business profiles matter more to you than headline growth, narrow your search with the 30 resilient stocks with low risk scores.
- For anyone who likes the combination of sturdy finances and clean balance sheets, compare Revvity with a broader list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com