


Wells Fargo (WFC) has moved back into focus after its board signed off on a quarterly dividend and regulators lifted constraints that had limited growth in loans and deposits.
Against that backdrop, Wells Fargo’s share price has slipped around 9.9% year to date, even though the 3 year total shareholder return is about 118.5%. The recent dividend decision and easing of regulatory limits look like fresh catalysts after a softer 90 day share price return of 3.6%.
Scan hand-picked banks with return and dividend profiles similar to Wells Fargo by reviewing the 36 high quality undervalued stocks, which highlights institutions that combine resilient cash generation with balance sheets the market may be underpricing.
Wells Fargo now trades below analyst fair value estimates after a strong multi year run and fresh regulatory relief. Does that setup argue for leaning in today, or for waiting to see if the recent pullback goes further before committing new capital?
Most Popular Narrative: 12% Undervalued
Against the last close of $85.76, the analyst consensus Narrative on Simply Wall St anchors Wells Fargo’s fair value near $97.90 based on discounted cash flows using an 8.7% rate. That view ties the recent regulatory relief and capital returns directly to what future revenue, earnings and valuation multiples might look like.
The removal of the asset cap and resolution of regulatory orders has already allowed Wells Fargo to grow average loans 12% year over year and average deposits 10% in 2Q26. Continued deployment of this larger balance sheet alongside a targeted CET1 range of 10% to 10.5%, with potential 7% lower risk weighted assets, is set up to influence revenue and earnings.
See why 154 investors see Wells Fargo as 12% undervalued.
Result: Fair Value of $97.90 (UNDERVALUED)
Still, the Wells Fargo narrative leans on net interest margins holding up and newer credit card vintages improving, so sustained pressure in either area could quickly challenge it.
Find out about the key risks to this Wells Fargo narrative.
Another View: What Wells Fargo’s P/E Is Telling You
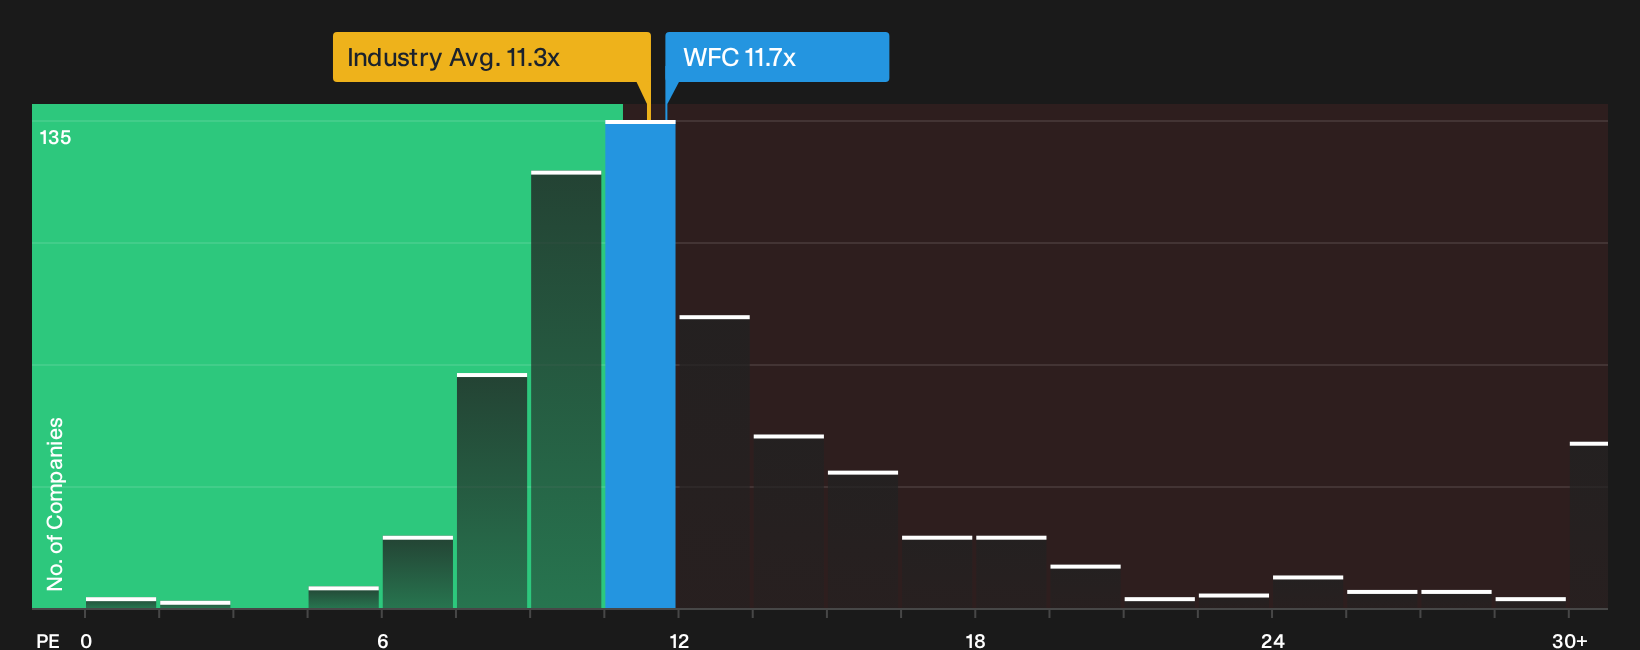
Analysts see Wells Fargo as undervalued on future cash flows, yet the current P/E of 11.7x sits slightly above both the US Banks industry at 11.3x and its peer average of 11.7x. The fair ratio of 13.8x hints at room for re rating. Is that a margin of safety or a value trap if earnings stumble?
For a closer look at how these earnings multiples stack up and where the fair ratio could pull the valuation, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Wells Fargo story so far. If you want to move early and form your own stance, start with the 3 key rewards and 1 important warning sign.
Looking for more Wells Fargo style investment ideas?
You have seen how one bank story can evolve quickly. Do not stop there, because widening your watchlist now could improve how you deploy your next dollar.
- Target resilience first by scanning a list of solid balance sheet and fundamentals (24 results) that filters for companies with robust fundamentals and balance sheets designed to handle tougher conditions.
- Hunt for mispriced opportunities through the 20 high quality undiscovered gems that highlight quieter businesses with strong financial footing that the broader market may be overlooking.
- Reduce stress while you invest by using the 30 resilient stocks with low risk scores to focus on companies with lower overall risk scores instead of chasing every headline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com