


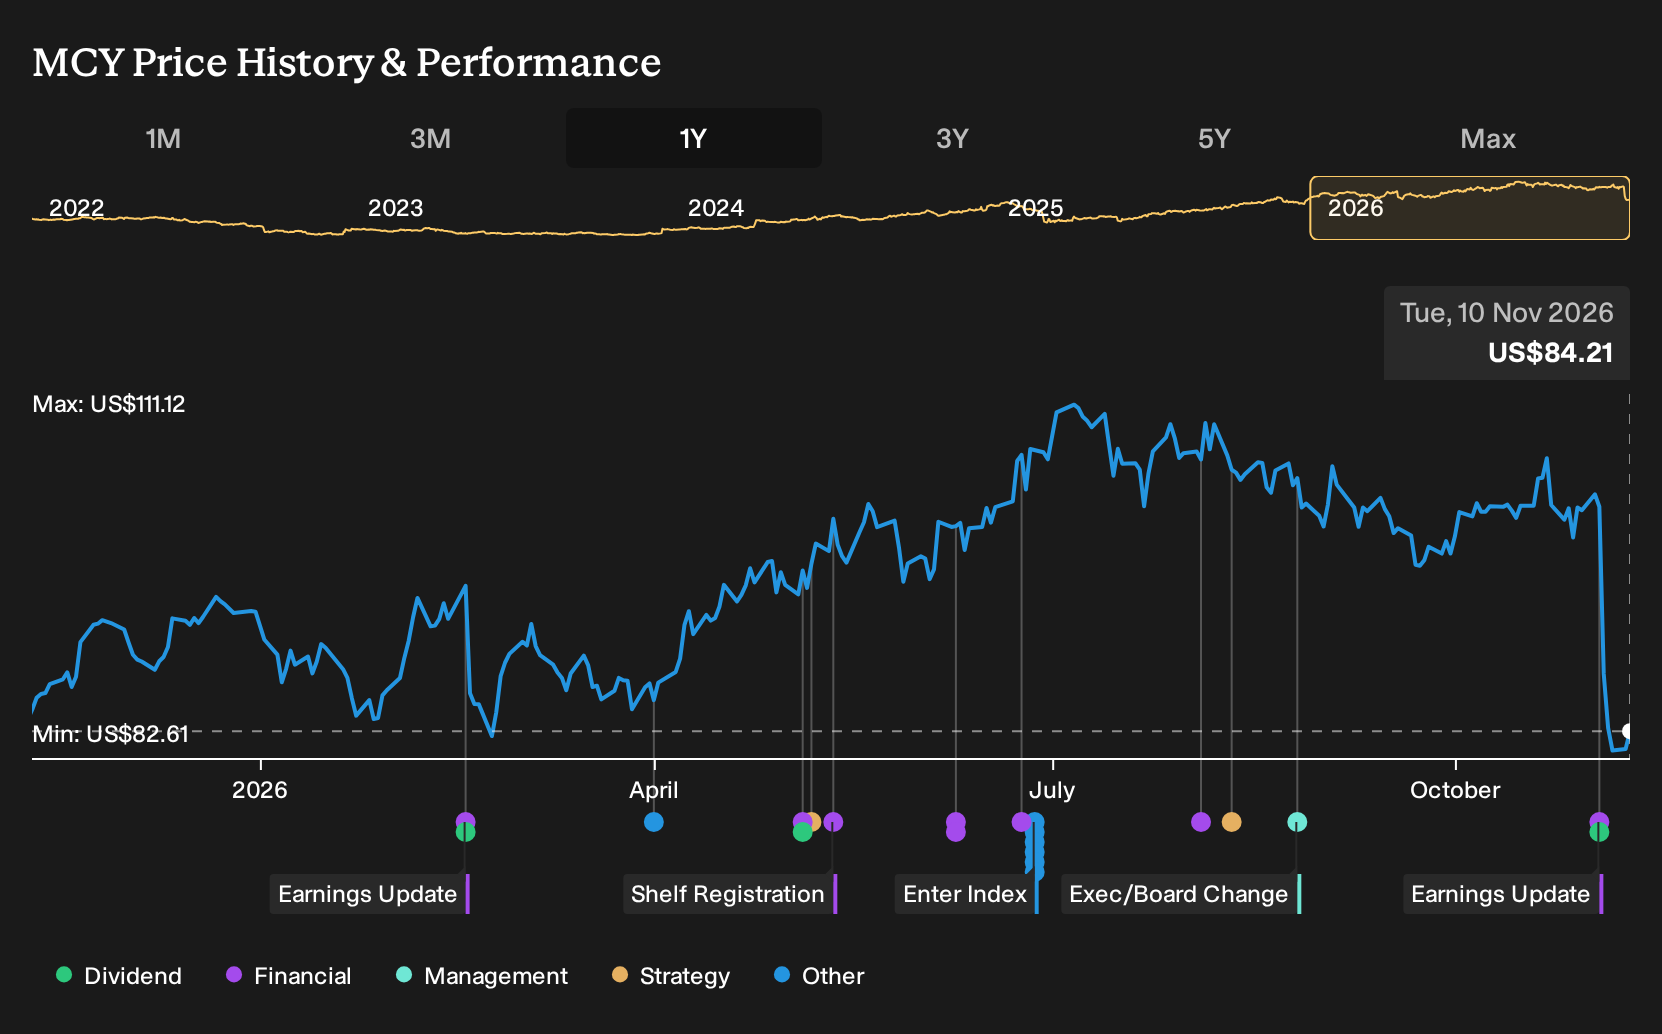
- Mercury General reported third quarter 2026 revenue of US$1,381.35 million compared with US$1,584.93 million a year earlier, and shifted from a US$280.4 million profit to a US$13.69 million loss, while nine month earnings and per share results remained positive year on year.
- The board affirmed a quarterly dividend of US$0.3175 per share, payable on December 31, 2026. This contrasts with the recent quarterly loss and highlights management’s decision to maintain cash returns while quarterly performance softens.
- Looking ahead, attention is likely to center on how Mercury General's swing to a third quarter loss fits within its existing earnings based investment narrative.
Compare Mercury General's third quarter swing to a loss with insurers that still screen well on fundamentals by scanning our hand picked list of solid balance sheet and fundamentals (24 results) before you move on.
Mercury General Investment Narrative Recap
To be comfortable holding Mercury General, you need to believe the core personal auto and homeowners book can keep producing solid underwriting results while catastrophe exposure is managed carefully. The analyst consensus Narrative on Simply Wall St points to a strong underlying combined ratio, and the nine month profit of US$440.24 million supports that broader earnings story despite the latest quarter.
The short term catalyst still revolves around how quickly underwriting results and catastrophe claims trends stabilise after the wildfire related hits highlighted in the risk list. The immediate concern is that further catastrophe losses or higher reinsurance costs pressure margins and slow any effort to rebuild statutory surplus.
The dividend affirmation at US$0.3175 per share is the announcement most closely tied to the latest earnings release. It came shortly after a quarter where Mercury General posted a US$13.69 million loss. This naturally puts attention on how resilient cash flows and capital are against wildfire risk and reinsurance pricing.
For catalysts, that payout decision sits alongside expectations for underlying earnings to support capital generation in future periods, as outlined in the analyst consensus Narrative on Simply Wall St. The key operational question for you is whether underwriting profits and any subrogation recoveries can fund both balance sheet repair and ongoing dividends without stretching the insurer’s risk profile.
Mercury General's narrative projects US$6.9b revenue and US$623.9 million earnings by 2029. This assumes 4.1% yearly revenue growth and an earnings decrease of about US$215.9 million from US$839.8 million today.
Uncover why Mercury General's fair value indicates a 43% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community range from about US$102.88 to US$187.69, so fellow retail investors see Mercury General as anywhere from modestly priced to heavily discounted. Consider those views alongside wildfire loss risk, reinsurance costs, and possible subrogation recoveries, then weigh how different outcomes could reshape Mercury General’s earnings profile.
Explore 3 other Mercury General fair value estimates, including one that suggests it could be worth just $102.88!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mercury General research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mercury General. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercury General's overall financial health at a glance.
Looking For More Ideas Beyond Mercury General?
If Mercury General's latest results have you rethinking your portfolio balance, widen the lens and compare it with other businesses that match your risk and income preferences using the Simply Wall St Screener.
- For potential mispricings backed by balance sheet strength, scan our curated 36 high quality undervalued stocks that combine quality fundamentals with lower implied downside.
- If steady income is a priority, review companies in the 5 dividend fortresses that pair higher yields with more established payout records.
- For a focus on stability and capital protection, filter for companies in the 30 resilient stocks with low risk scores that carry more resilient risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com