


With the Bank of England warning that young people in the UK are stuck in a low gear economy, investors are hunting for stories where leadership still has real skin in the game. Founder led British businesses can offer that, with leaders whose own reputations and wealth are on the line. This article highlights three such stocks, showing how these owner builders approach capital, culture, and long term decision making.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is personally tied to long term results. However, if you want the strongest names, these 8 top founder-led companies are the top of the list.
Computacenter (LSE:CCC)
Overview: Computacenter provides IT sourcing, managed services, and long term outsourcing for corporate and public sector clients across major global markets.
Operations: The business generates £12.1b from Computer Services, spread across the UK, Germany, Western Europe and a large North American footprint.
Market Cap: £4.9b
Computacenter ties its founder influenced, long tenured leadership directly to multi year IT outsourcing contracts. These are backed by a record £12.6b product backlog and upgraded profit guidance into 2026. That combination of committed client spend and leadership continuity can work powerfully for patient shareholders, depending on how one unseen pressure on long term contract profitability plays out.
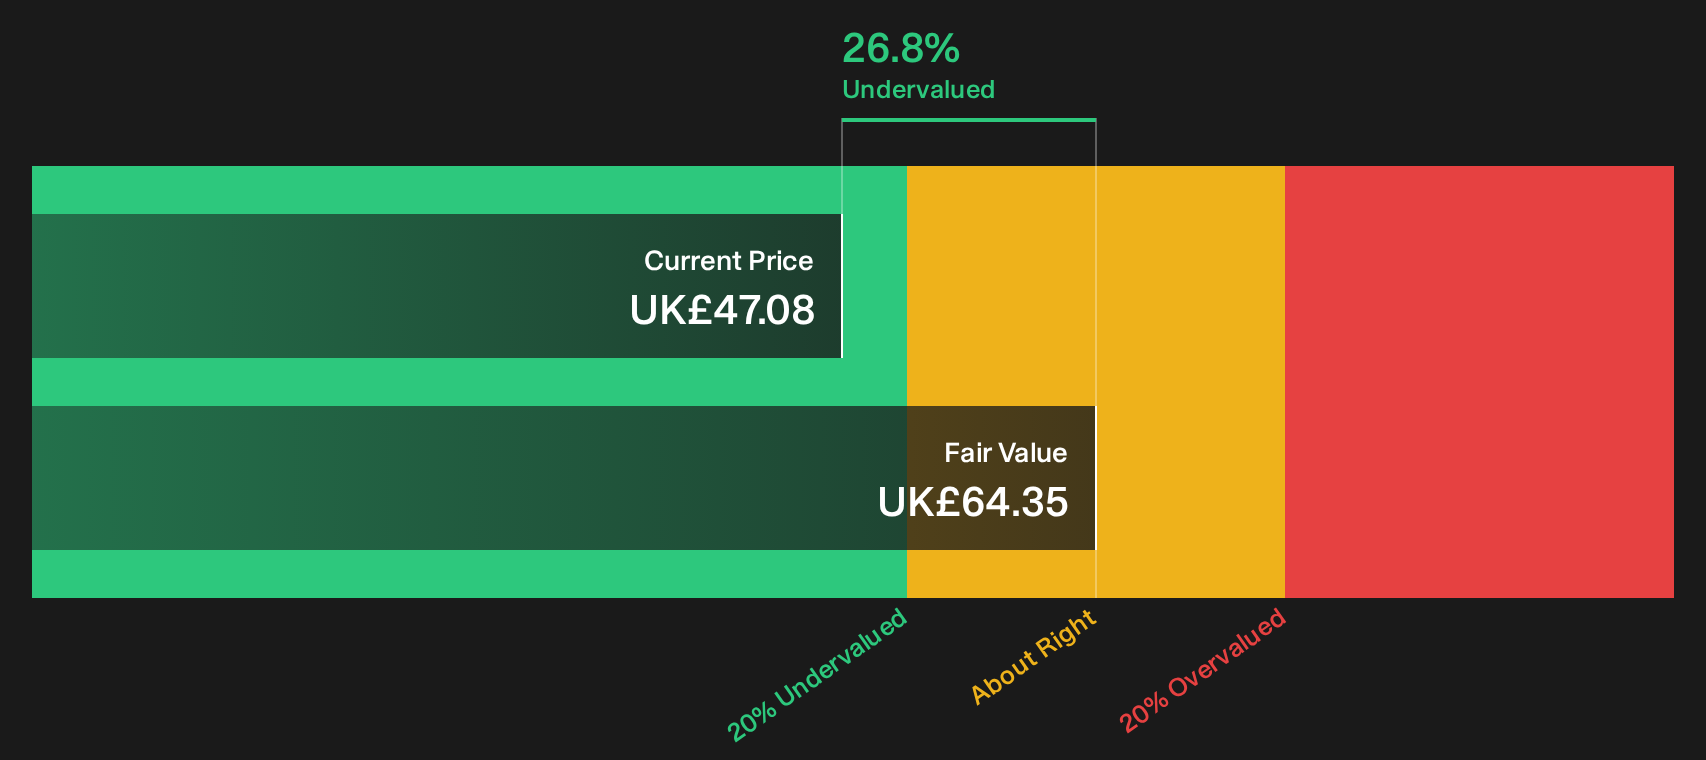
If that pressure worries you, stress test the story against the DCF valuation analysis for Computacenter to see what those contracts might really be worth under different assumptions.
Applied Nutrition (LSE:APN)
Overview: Applied Nutrition manufactures and sells founder led sports nutrition and wellness products, from proteins to hydration and vitamins, across global consumer channels.
Operations: Applied Nutrition generates £134 million from sports nutrition manufacturing and sales, with £58.3 million from the UK, £57.7 million international, and £18 million from Europe.
Market Cap: £750 million
Applied Nutrition fits this founder led screen because the same leadership that built its protein and hydration brands still sets the product agenda. The bullish analyst Narrative on Simply Wall St links this directly to how confidently the business is investing in extra capacity and distribution.
"High reported free cash flow conversion of 72% in FY25, combined with an adjusted EBITDA margin of 29% and a net cash position, provides Applied Nutrition with room to pursue bolt-on capacity or capability investments that could add incremental revenue without materially increasing financial risk. If demand or order flow into regions such as Eastern Europe, Latin America, Asia and Canada does not keep pace with this higher ceiling, fixed costs could weigh more heavily on gross margin and earnings."
What happens to Applied Nutrition’s valuation story ultimately rests on how fully that extra capacity translates into repeat demand at current margin levels.
That hinges on how far current pricing power can stretch, so read the full narrative for Applied Nutrition to see where Applied Nutrition’s risk and upside really accelerate.

Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings manages infrastructure, private equity and venture capital funds that channel growth capital into founder led and leadership driven businesses.
Operations: The group generates about £114.8 million from Real Assets and £50.1 million from Private Equity, mainly sourced from the UK and Australia.
Market Cap: £520 million
Foresight Group Holdings matters for this founder led screen because its core private markets engine is built around backing existing owner managers, and the bullish analyst Narrative on Simply Wall St argues that this approach is now supported by visible pipelines rather than vague growth hopes.
"Acceleration in real assets deployment into energy transition projects, supported by a near doubling of deployment in the most recent year and over £3.6b of identified future deployment rights in international mandates, gives Foresight Group Holdings room to turn existing pipelines into higher management fees and potentially stronger EBITDA growth as those commitments are drawn."
The real test for Foresight Group Holdings will be whether one unresolved pressure on fundraising momentum tilts long term fee growth above or below expectations.
If that fee pressure is what you are watching, read the full narrative for Foresight Group Holdings to see how current pipelines could still re-rate the whole story.

Seeking Alternatives Before They Fly Away
Fresh opportunities move fast. By the time most investors notice a breakout, the ideal entry can be gone. Scan these under the radar ideas while it matters and get in early.
- Spot potential turnarounds early by scanning 4 resilient stocks with low risk scores, which currently pairs steadier risk profiles with room for momentum before the crowd catches on.
- Ride structural trends in automation by checking 91 robotics and automation stocks, which is packed with businesses tied to real world robotics demand rather than hype cycles.
- Track the next wave of electrification by reviewing 41 power grid technology and infrastructure stocks, which is built around companies plugged into grid upgrades and energy infrastructure investment while it is still under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com