


OneSource Specialty Pharma Limited (NSE:ONESOURCE) is possibly approaching a major achievement in its business, so we would like to shine some light on the company. OneSource Specialty Pharma Limited, a biopharmaceutical company, engages in the research, development, manufacture, and commercialization of biological drug products in various injectable formats in India, Singapore, the United States, Spain, and internationally. With the latest financial year loss of ₹738m and a trailing-twelve-month loss of ₹16m, the ₹186b market-cap company alleviated its loss by moving closer towards its target of breakeven. As path to profitability is the topic on OneSource Specialty Pharma's investors mind, we've decided to gauge market sentiment. Below we will provide a high-level summary of the industry analysts’ expectations for the company.
Consensus from 4 of the Indian Life Sciences analysts is that OneSource Specialty Pharma is on the verge of breakeven. They expect the company to post a final loss in 2026, before turning a profit of ₹4.6b in 2027. Therefore, the company is expected to breakeven roughly a year from now or less! We calculated the rate at which the company must grow to meet the consensus forecasts predicting breakeven within 12 months. It turns out an average annual growth rate of 70% is expected, which signals high confidence from analysts. Should the business grow at a slower rate, it will become profitable at a later date than expected.
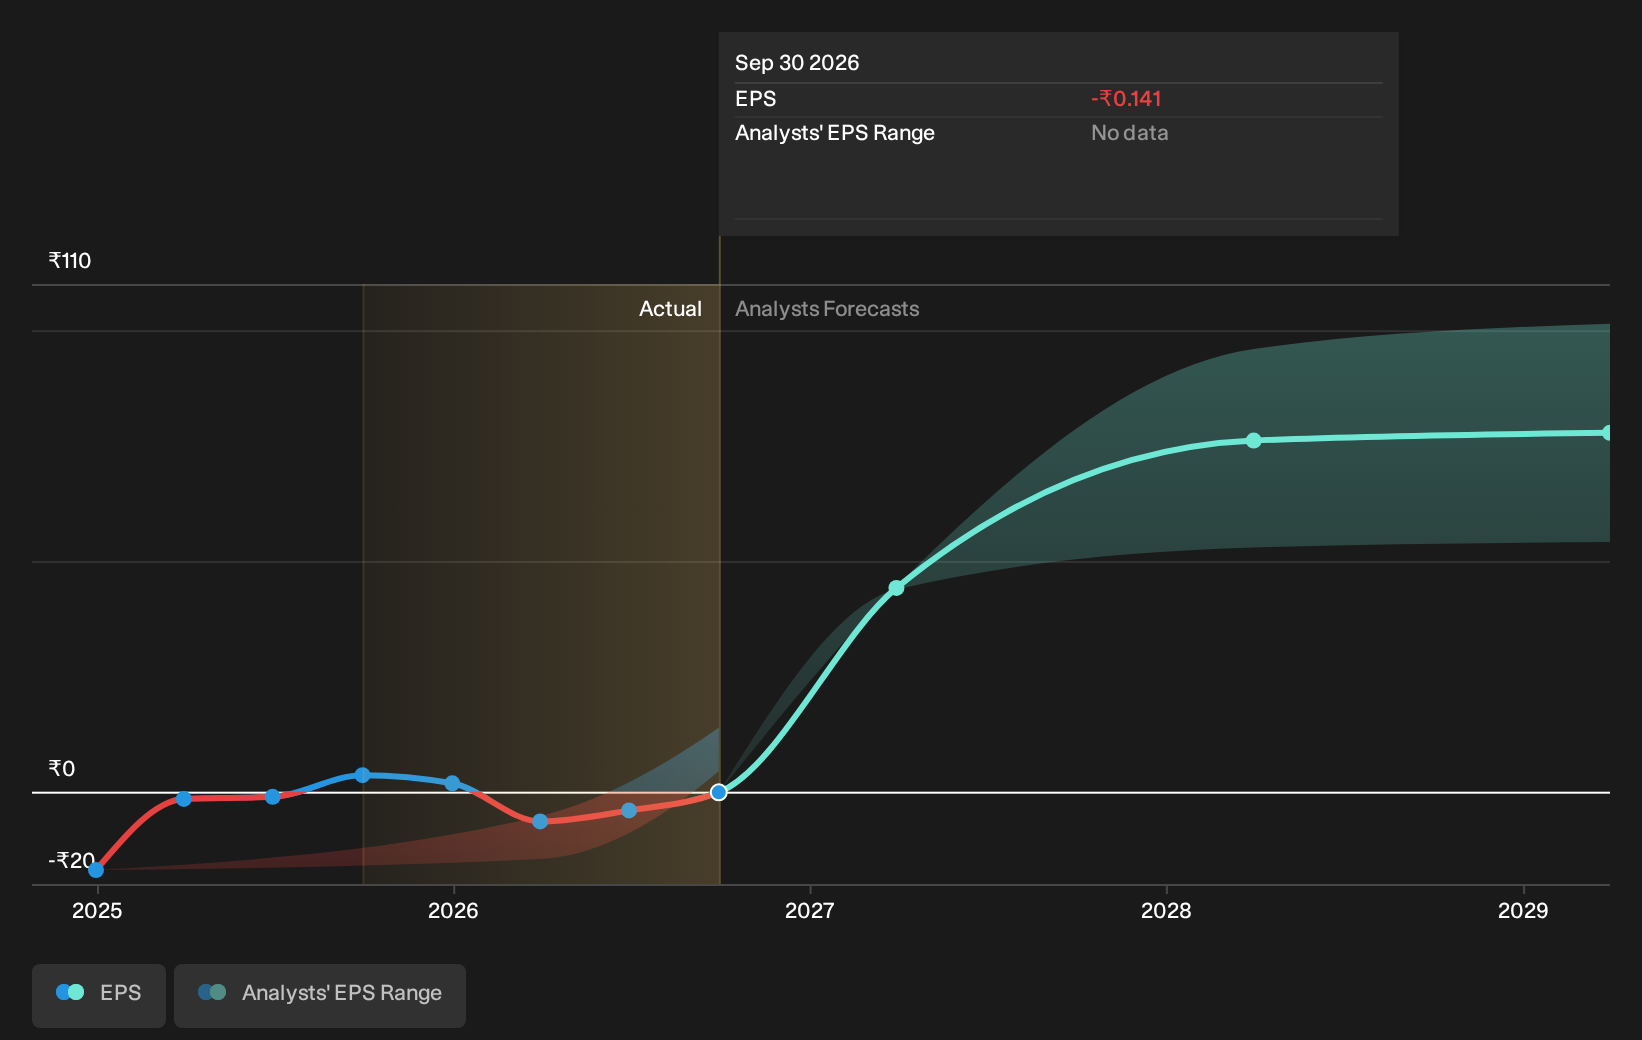
We're not going to go through company-specific developments for OneSource Specialty Pharma given that this is a high-level summary, but, bear in mind that typically a life science company has lumpy cash flows which are contingent on the product and stage of development the company is in. This means, large upcoming growth rates are not abnormal as the company is beginning to reap the benefits of earlier investments.
See our latest analysis for OneSource Specialty Pharma
Before we wrap up, there’s one aspect worth mentioning. The company has managed its capital judiciously, with debt making up 25% of equity. This means that it has predominantly funded its operations from equity capital, and its low debt obligation reduces the risk around investing in the loss-making company.
Next Steps:
There are key fundamentals of OneSource Specialty Pharma which are not covered in this article, but we must stress again that this is merely a basic overview. For a more comprehensive look at OneSource Specialty Pharma, take a look at OneSource Specialty Pharma's company page on Simply Wall St. We've also put together a list of essential factors you should look at:
- Valuation: What is OneSource Specialty Pharma worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether OneSource Specialty Pharma is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on OneSource Specialty Pharma’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.