


Lemonade has been a volatile ride for shareholders, and after a big multi year swing in returns the real question now is whether the current share price lines up with what its sales can reasonably support.
- Over the past 3 years the stock has climbed roughly 150%, which puts a lot of weight on how much revenue power investors believe Lemonade can ultimately deliver.
- Recent coverage has highlighted rapid top line growth alongside rising losses, so expectations around how this AI driven insurance model can turn strong sales into sustainable economics will be central to how you judge the valuation.
- Your read on Lemonade is one view; the desks covering it have another. See what analysts think Lemonade's shares could be worth.
The stock's next move may depend on whether Lemonade's current price is adequately backed by its sales today and the revenue base investors think it can build from here.
If you want more context on how Lemonade's sales based story compares with other opportunities, line it up against companies in the 36 high quality undervalued stocks
Does Lemonade Look Pricey on Sales?
P/S suits Lemonade because investors are currently focused on what its top line can support before profits settle into a steady pattern.
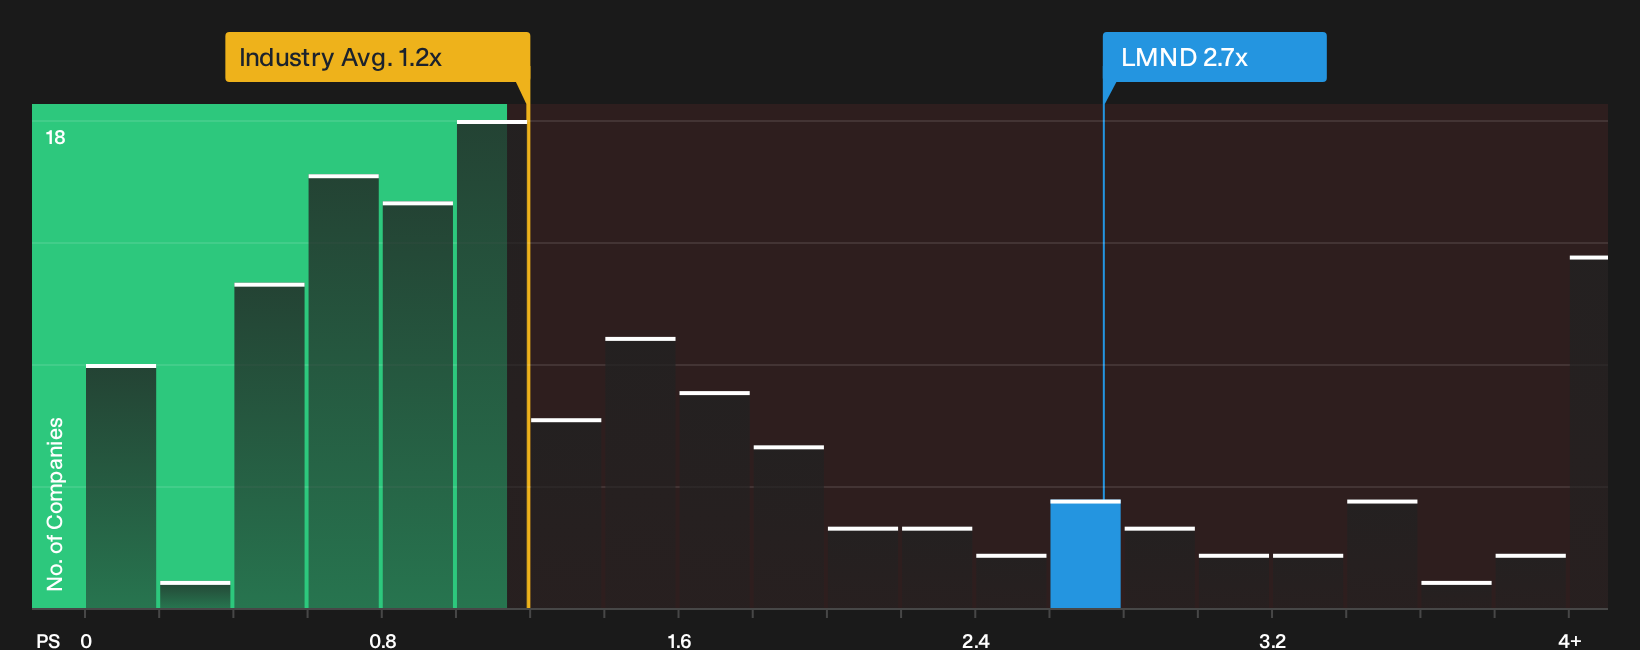
The stock trades on roughly 2.7x P/S, which is higher than both the Insurance industry average of about 1.2x and a peer group closer to 2.1x. On this framework, the tailored fair multiple that blends Lemonade’s growth profile, margin structure, size and risk flags suggests the present P/S leans toward overvalued rather than cheap.
Because the latest Q3 2026 update paired very strong revenue gains with a wider net loss, this richer P/S tag implies investors are still putting a premium on future execution instead of current profitability. Anyone assessing Lemonade here needs to weigh how much confidence to put in that AI driven insurance model eventually converting rapid sales into durable cash generation at a level that justifies paying above both sector and peer P/S benchmarks. Explore the numbers behind Lemonade's P/S valuation.
The Lemonade Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Lemonade valuation puzzle leaves off by clearly explaining which expectations for growth, margins, and eventual earnings would need to align for the stock to be worth materially more or less than today’s price. Each scenario focuses on the assumptions behind its fair value so you can later compare those inputs with the company’s actual results as new numbers arrive on the Community page.
One of the top narratives on Lemonade: 33% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"A key factor is whether Lemonade can turn its AI enabled cost advantages, such as a 5% LAE ratio and lower growth financing costs, into sustained improvements in loss economics and cross sell…"
Discover why this Narrative puts Lemonade at 33% undervalued.
One more piece to the Lemonade puzzle before you act
Lemonade’s story does not end with ratios and narratives, because Simply Wall St’s broader checks have also flagged specific concerns that sit outside the valuation box and deserve a closer look before you commit. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com