


Blue Owl Capital (OWL) just paired a fresh earnings update with an unchanged dividend. Third quarter revenue reached US$806.53 million and net income was US$19.96 million, alongside a declared quarterly payout of US$0.23 per Class A share.
Despite the stronger third quarter update and steady dividend, Blue Owl Capital’s recent trading tells a more cautious story. The share price has fallen about 33% year to date, and the 1 year total shareholder return is down roughly 26%, suggesting momentum has faded even after a 7.6% gain over the past month.
Look beyond Blue Owl Capital and explore other alternative asset managers facing similar earnings and dividend dynamics with our curated list of list of solid balance sheet and fundamentals (24 results)
Bulls point to Blue Owl Capital’s rising revenue, positive net income and confirmed dividend, while bears highlight the sharp share price slide. Which side does the current valuation actually support?
Most Popular Narrative: 21% Undervalued
Blue Owl Capital last closed at $10.21, while the analyst consensus Narrative on Simply Wall St sets fair value at $12.92 using an 8.37% discount rate. This frames the stock as materially cheaper than that implied value.
Significant ongoing growth in permanent capital vehicles, particularly through expansion in private credit, real assets, and evergreen and interval fund strategies, is still providing a larger base of recurring management fee revenue for Blue Owl Capital and keeps the potential for higher fee related earnings and durable margin expansion alive.
See why 61 investors see Blue Owl Capital as 21% undervalued.
Result: Fair Value of $12.92 (UNDERVALUED)
Still, the valuation story for Blue Owl Capital only holds if fundraising pressures and the investor lawsuit do not escalate enough to dent fee paying assets.
Find out about the key risks to this Blue Owl Capital narrative.
Another View: Rich Multiples Keep Blue Owl Capital In Check
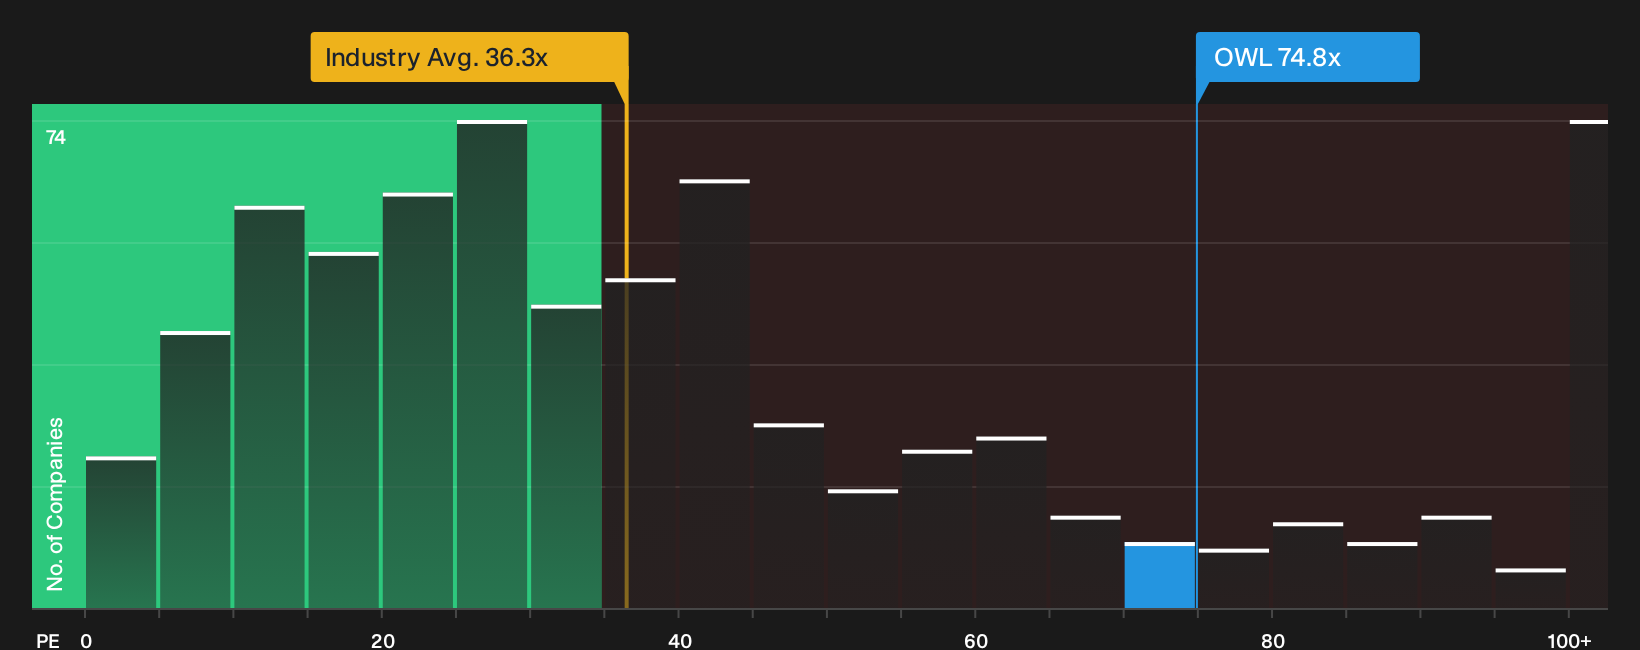
The analyst Narrative paints Blue Owl Capital as roughly 21% undervalued at $10.21, yet the market is already paying a steep P/E of 74.8x. That compares with 36.3x for the US Capital Markets industry, a 29.9x peer average and a fair ratio of 20x that the valuation model points to.
Such a large premium leaves less room for error if earnings or fundraising fall short of expectations. It raises a simple question for you as an investor: Is this a genuine mispricing, or is the high multiple already doing the heavy lifting in the story?
Before leaning too hard on the analyst target or the Narrative, it is worth checking how the current valuation stacks up against detailed earnings and balance sheet work in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Blue Owl Capital so far. If you want a faster way to weigh those risks against the potential upside, start by reviewing the 2 key rewards and 3 important warning signs.
Looking for more Blue Owl Capital sized investment ideas?
If Blue Owl Capital has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist with fresh, data driven candidates before the next move passes you by.
- Target resilient compounding potential by scanning companies with strong payout power through the 5 dividend fortresses.
- Hunt for mispriced quality where fundamentals and valuations still look appealing using the 36 high quality undervalued stocks.
- Prioritize capital preservation and steadier ride potential by filtering for stocks through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com