


NGL Energy Partners (NGL) has put guidance in the spotlight after lifting its fiscal 2027 adjusted EBITDA outlook and highlighting record Water Solutions results, even as recent quarterly earnings showed a headline loss.
The latest guidance update lands after a sharp run-up in NGL Energy Partners’ share price, with a year to date share price return of 59.19% and a 1-year total shareholder return of 57.92%, anchored by a very large 5-year total shareholder return of about 7x. Recent trading has cooled slightly, with the 30-day share price return of 6.92% partly offset by a 90-day share price decline of 7.24%. This pattern suggests that investors are weighing the upgraded EBITDA outlook and Water Solutions strength against the recent quarterly loss as they reassess risk and future cash generation.
Compare NGL Energy Partners’ guidance-driven story with a curated group of infrastructure and cash flow focused businesses by scanning the 36 high quality undervalued stocks that could be pricing in a similar setup.
Bulls point to NGL Energy Partners’ richer EBITDA outlook and Water Solutions strength, while bears focus on headline losses and fresh capex. The key question is which story better fits the current valuation setup that follows next.
Preferred Price-to-Sales of 0.4x: Is it justified?
NGL Energy Partners closed at $15.76, and on a P/S ratio of 0.4x it screens as good value compared with both peers and the wider US Oil and Gas industry. This suggests that the recent share price strength has not erased all of the apparent discount.
The P/S metric compares the partnership’s market value to its $4,639.703m of revenue and is often used for businesses that are still loss making at the net income line. For NGL Energy Partners, this lens matters because the group reported a net loss of $379.561m and remains unprofitable, so earnings-based ratios do not yet give a clear signal.
On this measure, the stock is described as good value versus peers at an average P/S of 2.5x and also versus the US Oil and Gas industry at 1.8x. This is a steep gap for the market to be assigning. The estimated fair P/S ratio of 0.5x sits above the current 0.4x reading, so pricing could reasonably move closer to that level if investors place more weight on the improved loss trend and the expectation that NGL is forecast to become profitable over the next 3 years.
Explore the SWS fair ratio for NGL Energy Partners.
Result: Price-to-Sales of 0.4x (UNDERVALUED)
Still, the recent net loss of $379.561m and the annual revenue decline of 25.90% could quickly challenge the NGL Energy Partners rerating story if sentiment turns.
Find out about the key risks to this NGL Energy Partners narrative.
Another View: DCF Fair Value for NGL Energy Partners
The P/S ratio presents NGL Energy Partners as inexpensive, and the SWS DCF model goes further and values the partnership at $34.55 per unit compared with the current $15.76 price. That indicates a substantial potential undervaluation. The key question is whether future cash flows support confidence in this higher DCF-based valuation.
Look into how the SWS DCF model arrives at its fair value.
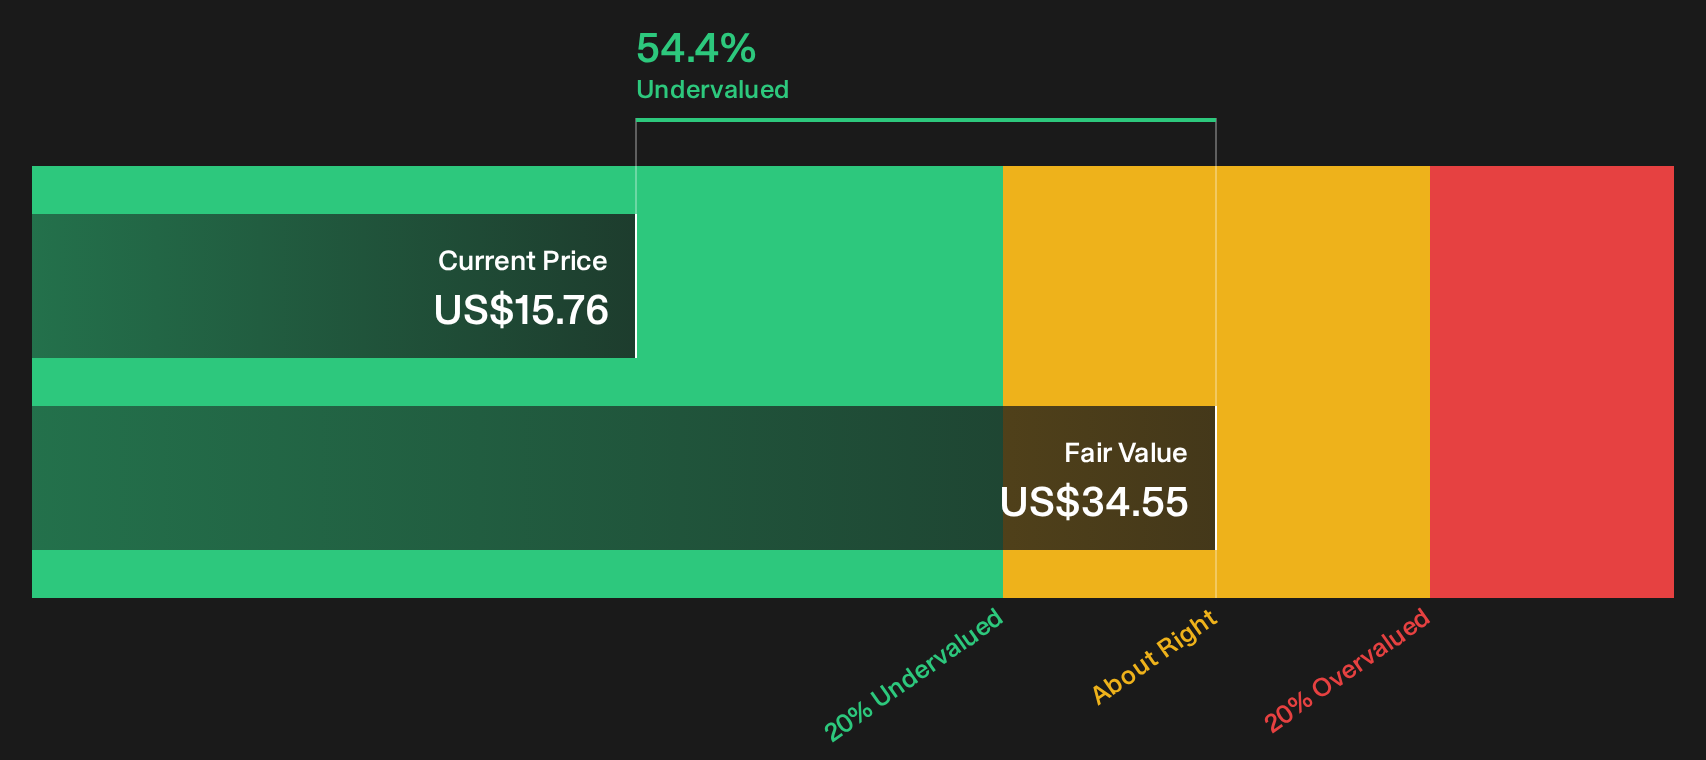
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NGL Energy Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on NGL Energy Partners so far, or a clear message hiding in plain sight. Act quickly, review the full data set, and shape your own view with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond NGL Energy Partners?
Do not stop your research with NGL Energy Partners. Use fresh watchlists from the Simply Wall Street Screener to pressure test your thesis and spot opportunities others might skip.
- Target potential mispricings by scanning companies that pair strong fundamentals with low expectations through the 36 high quality undervalued stocks.
- Strengthen your focus on resilience and capital preservation by reviewing a list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities by checking a 20 high quality undiscovered gems before attention and pricing catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com