


- UroGen Pharma reported third quarter 2026 sales of US$89 million with a net loss of US$1.46 million, alongside a shelf registration of up to US$55.04 million in ordinary shares and progress across its uro oncology pipeline, including first dosing in the Phase 1 UGN-501 trial.
- Recent data showing durable JELMYTO responses, together with the early UGN-501 study and a sharply narrower quarterly loss, highlight how UroGen Pharma is trying to balance ongoing R&D investment with a more established urothelial cancer franchise.
- We will now look at how UroGen Pharma's sharply reduced quarterly net loss could reshape the broader investment narrative for the business.
UroGen Pharma Investment Narrative Recap
For UroGen Pharma, the core belief is that a focused uro oncology platform can eventually support its current spending and move the business closer to break even. The third quarter print, with US$89 million in sales and a net loss of US$1.46 million, points to improving operating leverage but not yet to a self funding model.
The analyst consensus narrative on Simply Wall St focuses on future revenue growth, so the short term swing factor remains how consistently ZUSDURI and JELMYTO perform against guidance while expenses track toward US$260 million to US$270 million. The biggest risk is that high costs and a concentrated portfolio keep losses and funding questions in play.
The UGN 501 first patient dosing announcement is closely linked to that thesis. UroGen Pharma is trying to convert its bladder cancer research into a broader product set. If this is successful, it could eventually spread fixed operating costs across more than the current commercial therapies and reduce reliance on JELMYTO and ZUSDURI alone.
That Phase 1 study is still early and carries typical development risk, including safety outcomes, feasibility of intravesical delivery and future regulatory decisions. For you as an investor, execution around UGN 501, the UGN 103 filing and existing commercial brands now forms a cluster of catalysts that must be weighed against balance sheet constraints and less than one year of cash runway.
UroGen Pharma's narrative projects US$773.8 million revenue and US$294.4 million earnings by 2029. This rests on analysts assuming 45.7% yearly revenue growth and an earnings increase of about US$360 million from earnings today of a US$65.8 million loss.
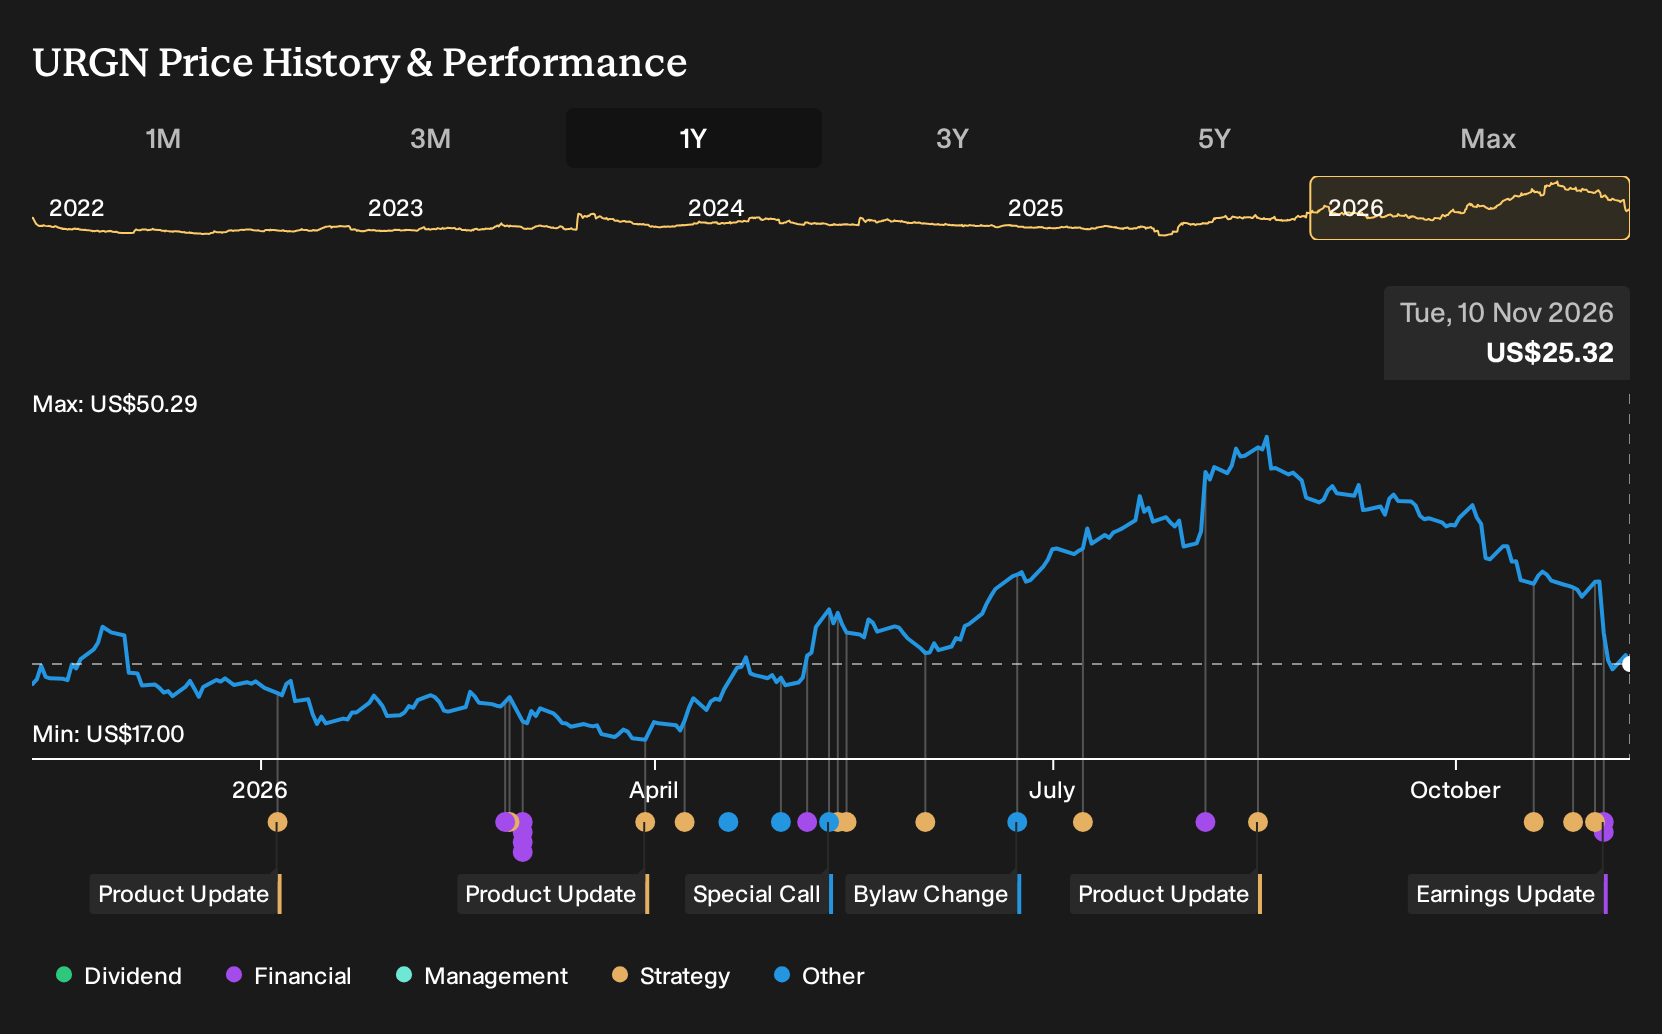
Uncover why UroGen Pharma's fair value indicates a 144% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate view puts UroGen Pharma’s high operating expense plan at the center of the story. The most cautious analysts were still modeling roughly US$781.9 million of revenue and US$285.3 million of earnings by 2029, yet saw that spending ramp as a drag. You can decide whether the latest earnings and UGN-501 update eventually shift that cautious script.
Explore 2 other UroGen Pharma fair value estimates, including one that suggests it could be worth just $56.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your UroGen Pharma research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for UroGen Pharma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UroGen Pharma's overall financial health at a glance.
Looking For More Investment Ideas Beyond UroGen Pharma?
If UroGen Pharma has put uro oncology on your radar, it can also be a good moment to widen your watchlist with other clear, data driven ideas from the Simply Wall St Screener.
- For investors who want potential upside with tighter budgets, scan the 9 elite penny stocks with strong financials that combine smaller market caps with stronger balance sheets and fundamentals than many peers.
- If quality at a sensible entry point is your priority, focus on companies in the 36 high quality undervalued stocks that pair solid cash flows with what analysts see as discounted prices.
- For those who care most about stability and resilience through cycles, concentrate on the 30 resilient stocks with low risk scores that screen for stronger financial health and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com