


Brazil’s government is preparing fresh fiscal measures that aim to cool debt concerns and support lower local interest rates, and that shift in the cost of money can reshape the outlook for domestically focused stocks. When long rates move, refinancing, credit demand and real estate decisions all get repriced. This article examines what that could mean for Brazil Domestic Cyclicals and outlines 3 stocks exposed to this policy story.
The three Brazil Domestic Cyclicals highlighted below are only a small sample of what screens out when interest rate sensitive sectors are filtered for basic size, balance sheet and business quality criteria. The full set includes 13 more locally exposed companies with equally compelling stories that are not covered here. To see the broader field and identify which Brazil focused plays best fit your risk tolerance and thesis on local borrowing costs, head straight to the Brazil Domestic Cyclicals (Equities Leveraged to Lower Local Interest Rates) screener
C&A Modas (BOVESPA:CEAB3)
Overview: C&A Modas is a Brazil based fashion retailer whose clothing, footwear, beauty and online offerings are tightly linked to local consumer spending and store credit conditions.
Operations: C&A Modas generates about R$7.7b from Retail and R$368 million from C&A Pay financial services, with minor internal eliminations.
Market Cap: R$2.4b
C&A Modas fits this Brazil Domestic Cyclicals theme as a retailer whose fortunes are closely tied to household budgets and the cost of credit. This is why the analyst consensus Narrative on Simply Wall St focuses heavily on how its digital push and store refresh program are changing the earnings profile.
"Rapid investments in digital tools such as AI powered search, personalized app storefronts and an AI personal shopper are now feeding into 29.2% year over year growth in website and app sales, which reached 7% of total sales and support further revenue growth and stable merchandise margins as the online mix increases."
The real swing factor is how one still evolving pressure on C&A Modas’ cost base and pricing power ultimately flows through to margins.
That margin question is exactly what the full narrative for C&A Modas unpacks, showing where C&A Modas could be accelerating or stalling as credit conditions shift.

Cosan (BOVESPA:CSAN3)
Overview: Cosan is a Brazil headquartered energy and infrastructure group that runs fuel distribution, natural gas, logistics, lubricants and farmland platforms tied to domestic activity.
Operations: Cosan generates about R$15.2b from Compass, R$14.4b from Rumo, R$10.0b from Moove and R$0.6b from Radar, with most revenue coming from Brazil.
Market Cap: R$10.9b
Cosan plugs directly into this Brazil Domestic Cyclicals theme because fuel, rail and gas volumes respond quickly when local financing conditions improve. The analyst consensus Narrative on Simply Wall St frames the story around how that operating leverage interacts with the holding company’s balance sheet repair.
"Execution on portfolio recycling, including the Compass secondary offering, the agreed sale of part of Radar’s land portfolio and the pending exit from the Porto São Luís terminal, is freeing capital to cut holding-level debt and interest expense. This can lift net income and free cash flow as expanded net debt and financing costs fall."
What really moves the needle for Cosan is how one unresolved pressure on its debt service coverage ratio shapes future cash generation.
This is where Cosan’s unresolved pressure point starts to matter, and the full narrative for Cosan shows whether that leverage is quietly accelerating or still masking bigger risks.
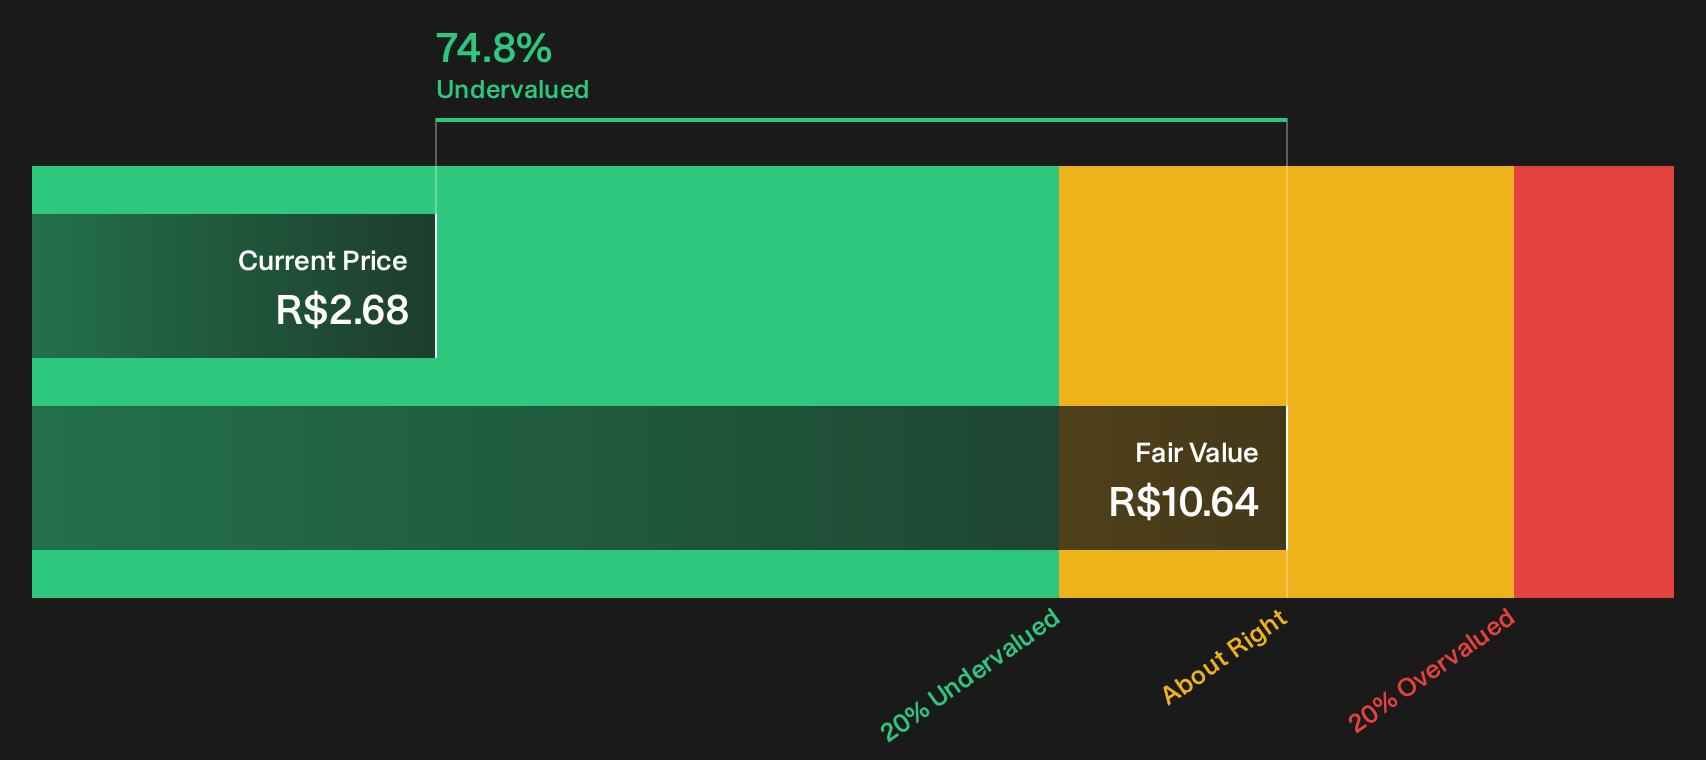
Lojas Quero-Quero (BOVESPA:LJQQ3)
Overview: Lojas Quero-Quero is a Brazil based retailer selling home improvement and household goods, supported by its own credit and financial services.
Operations: Lojas Quero-Quero generates about R$2.9b from home improvement retail across Brazil, fully concentrated in its domestic market.
Market Cap: R$230 million
Lojas Quero-Quero plugs directly into this Brazil Domestic Cyclicals theme because its installment heavy home improvement retail model leans on local credit costs. The analyst consensus Narrative on Simply Wall St frames that exposure through how store expansion, phygital sales and in house credit interact with funding conditions.
"Ongoing expansion into underserved, lower-competition interior towns combined with a still growing store base across 495 cities keeps Lojas Quero-Quero positioned to capture incremental consumer spend in smaller municipalities, which can support store revenue and overall earnings."
What really decides how that potential plays out is how pressure on funding costs and credit quality shapes future profitability and cash generation.
That credit squeeze is the key swing factor, and the full narrative for Lojas Quero-Quero shows whether Lojas Quero-Quero’s interior-town expansion is quietly accelerating value or masking brewing risk.

Curious About What You Might Be Missing
Fresh ideas move first. Breakout stories get caught early, momentum shifts fast and under the radar pockets drop off the map before the crowd notices. Act now.
- Spot sturdy payers that can help steady portfolio swings while yields keep flying around by using the curated 216 dividend fortresses before these payouts draw wider attention.
- Explore early-stage breakthroughs where real earnings already support the story by scanning the hand picked 42 profitable AI stocks that aren't just burning cash while these trends are still under the radar for now.
- Position ahead of potential infrastructure momentum by filtering through the targeted 41 power grid technology and infrastructure stocks before renewed spending themes draw these tickers into wider focus.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com