


Scorpio Tankers (STNG) just paired a fresh earnings update with a higher quarterly dividend, a combination that puts both profitability and cash returns to shareholders in focus as the December payout approaches.
Recent price action has cooled a little, with the share price slipping 7.77% over the past week and 5.39% over the past month, even as Scorpio Tankers still carries a year to date share price return of 62.11% and a five year total shareholder return of about 4.5x. This may hint that investors are reassessing near term risk while longer term holders remain well rewarded.
Scan beyond Scorpio Tankers and line up other high quality cash generators with strong balance sheets, using our curated 36 high quality undervalued stocks as a starting watchlist.
Fresh earnings strength and a richer dividend meet a share price that just cooled off. Is Scorpio Tankers more interesting on this pullback, or is it worth waiting for a deeper reset before committing new capital?
Most Popular Narrative: 38% Undervalued
Against a last close of $80.55, the bullish analyst Narrative on Simply Wall St anchors Scorpio Tankers at a fair value of $130, using a 9.052% discount rate and explicitly baking in falling revenue and shrinking margins.
Incremental earnings capacity from newbuild and JV commitments of just over US$978 million, which can be funded from existing liquidity, gives Scorpio Tankers additional operating leverage to any future rate strength that may not be fully captured in current revenue and EPS expectations.
See why 2 investors see Scorpio Tankers as 38% undervalued.
Result: Fair Value of $130 (UNDERVALUED)
Still, the bullish Scorpio Tankers script can break if refined product demand weakens faster than expected or if environmental rules force heavier, margin-squeezing capital expenditures.
Find out about the key risks to this Scorpio Tankers narrative.
Another View: Our DCF Flags A Very Different Fair Value
Scorpio Tankers looks inexpensive based on an analyst fair value estimate of $130 per share, yet the Simply Wall St discounted cash flow (DCF) model presents a very different perspective. On that cash flow basis, the estimated value is $20.97 per share. This compares with the recent $80.55 share price, which sits well above the implied range and challenges the idea that the stock is underpriced. When the gap is this wide, it is important to consider which valuation lens you place more weight on.
Before relying too heavily on either narrative, it helps to understand exactly how the cash flows are treated and what the model assumes about the future, then compare that with your own expectations for factors such as freight rates, fleet utilization, and reinvestment needs. Look into how the SWS DCF model arrives at its fair value.
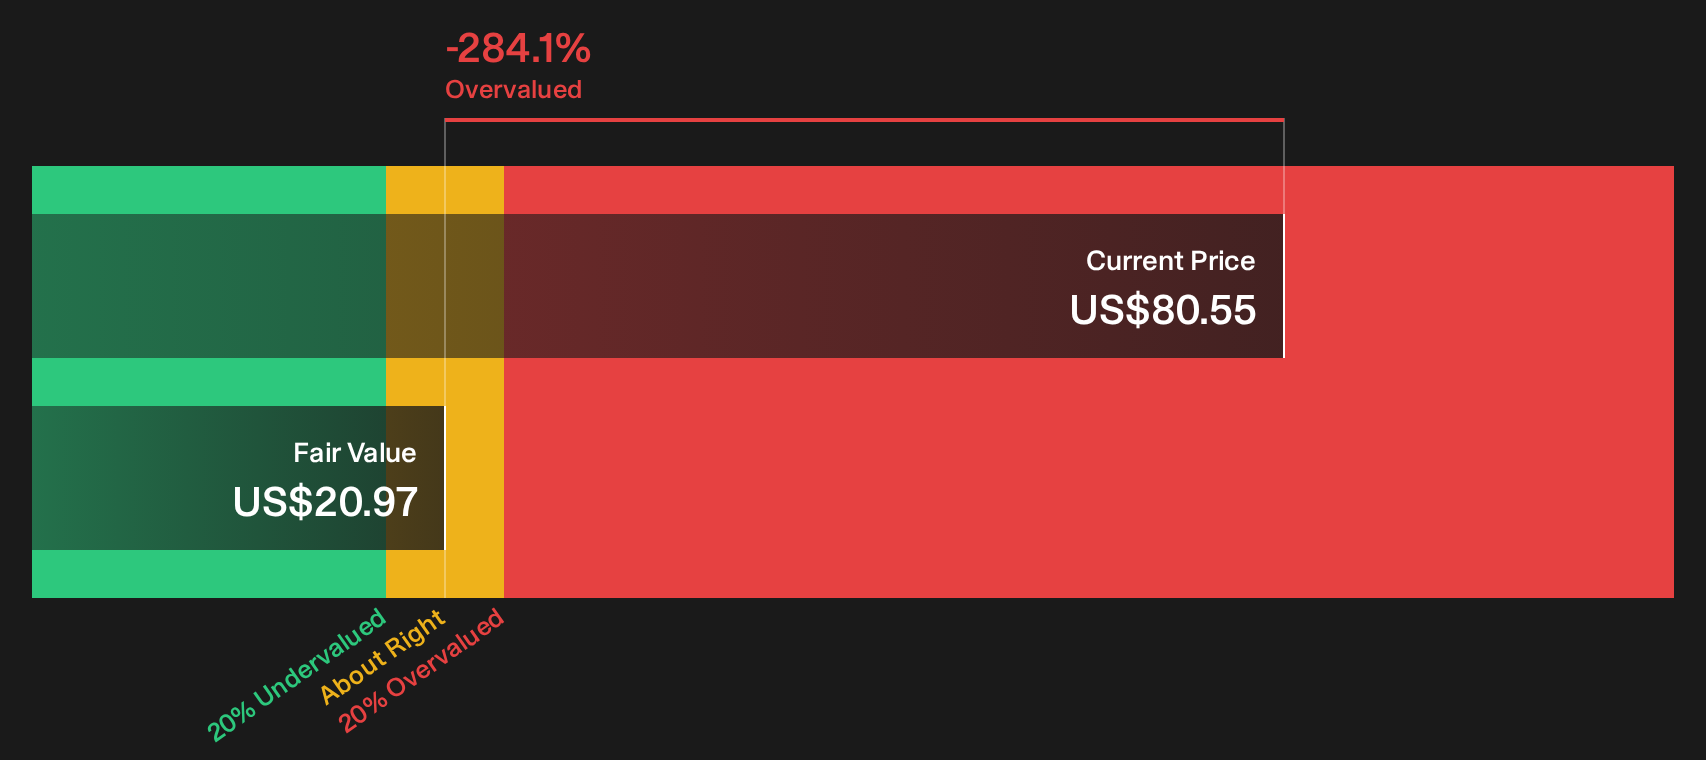
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Scorpio Tankers for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Scorpio Tankers can feel messy, so move fast, gather the facts for yourself, and weigh both sides using the 4 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Scorpio Tankers?
If Scorpio Tankers has sharpened your focus on quality and valuation, keep that momentum going and line up fresh opportunities before the crowd moves first.
- Target stronger income potential by reviewing higher yielding candidates in the 5 dividend fortresses that still clear key balance sheet and payout checks.
- Upgrade portfolio resilience by filtering for financial robustness with the list of solid balance sheet and fundamentals (24 results) and sidestep weaker capital structures.
- Hunt for future leaders early by scanning the 20 high quality undiscovered gems before they attract wider market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com