


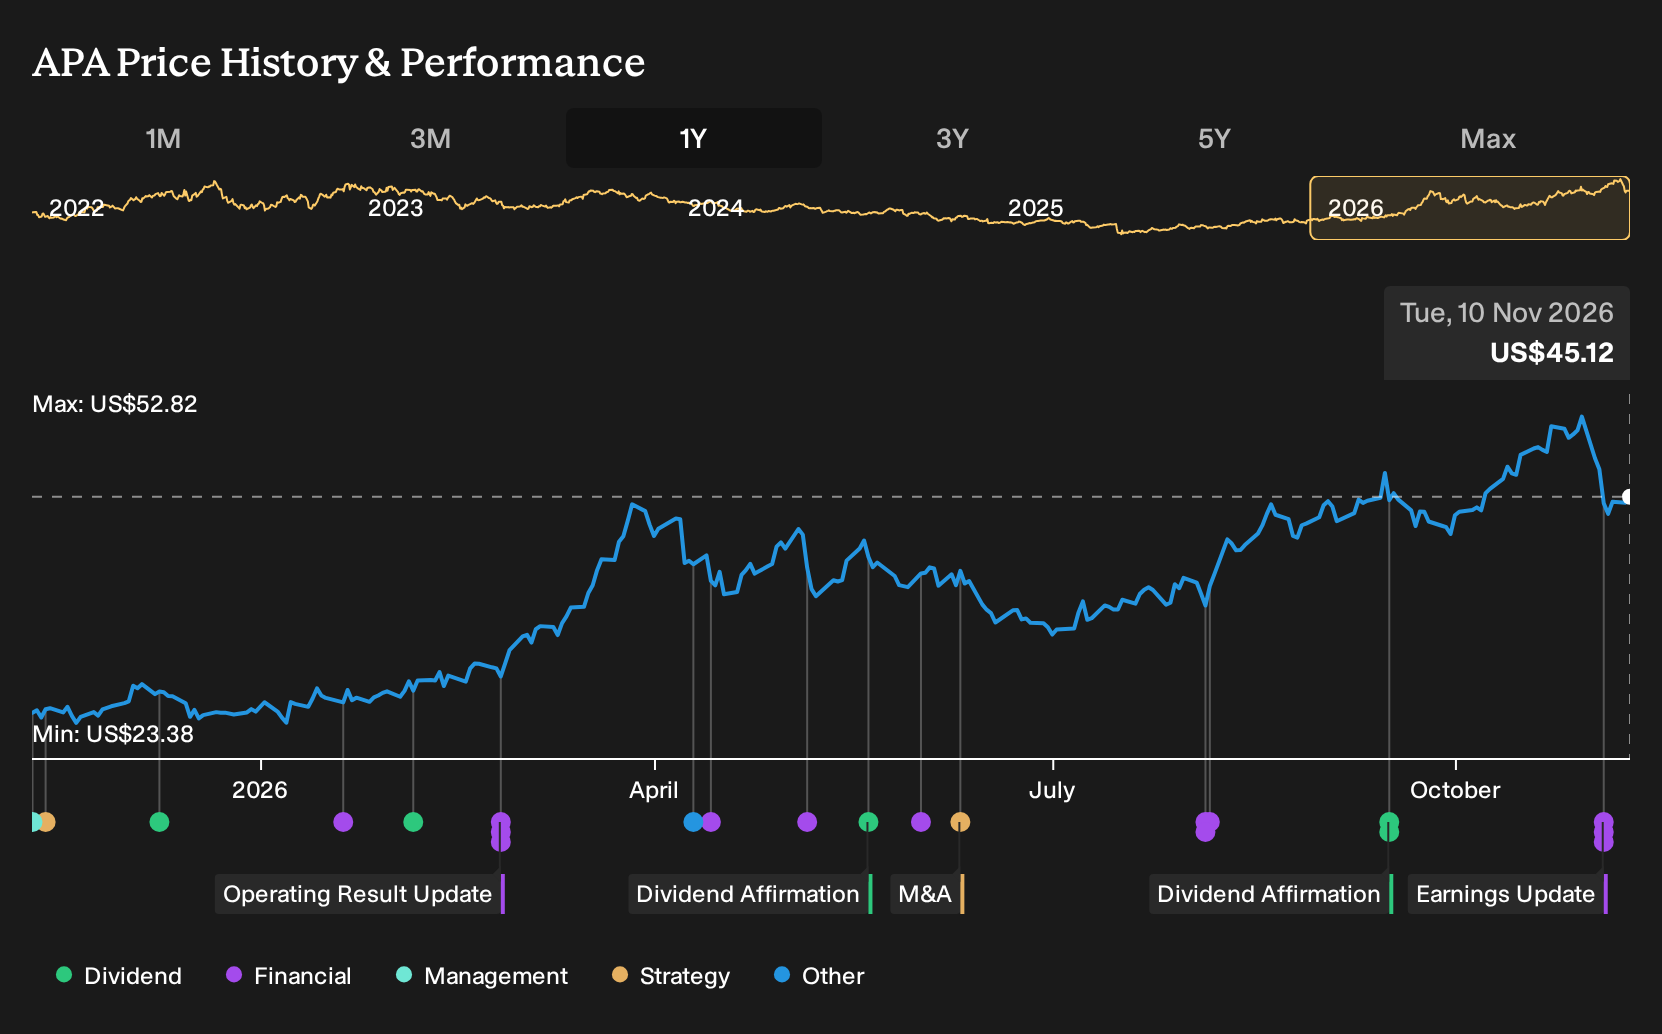
If APA was on your watchlist instead of in your portfolio, the recent move may feel like a punch to the ribs. Investors who held APA over the past year are up 88.7%, including dividends. Recent quarters brought strong free cash flow, higher net margin and a heavier tilt toward low cost assets in places like Egypt, Suriname and Alaska. If that shift to underexplored, lower breakeven projects was already on record in late 2025, what was the real clue you needed to see it as an opportunity?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made APA harder to judge, start where the gap is still open and scan 36 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On APA
The shares cost US$24.35 at the start of the period, and APA sat between two very different stories about what might come next.
On the optimistic side, the bull Narrative saw Fair Value at US$35 and leaned on Egypt, Suriname and Alaska. It assumed revenue would decline 1.5% a year but margins could rise from 11.0% to 25.3% by 2028.
The bearish view put Fair Value at US$16 and focused on renewables pressure, regulation and political risk. That Narrative assumed revenue would fall 9.7% annually and earnings in 2028 would be US$890.3 million.
What The Results Changed For The APA Narrative
The clearest test of the APA bull case came from the Q3 2026 report. Revenue moved from US$2,110m in Q3 2025 to US$2,775m in Q3 2026, while net income excluding extra items went from US$205m to US$698m and net margin shifted from 9.7% to 25.2%. That supported the optimistic margin story more than the cautious revenue decline scenario, although one period did not settle it.
The lesson to carry elsewhere is simple. When a thesis hinges on margin expansion, track net income and net margin in each report more closely than headline revenue or short term share moves.
What APA's Price Already Assumes After The Run
APA now trades at US$45.12 after an 88.7% gain over the past year. The bearish analyst Narrative on Simply Wall St sets its Fair Value below that level and frames today’s quote as already baking in successful execution on cost cuts, portfolio reshaping and Suriname driven cash flow.
A buyer today is effectively assuming APA converts current free cash flow, gas trading profits and frontier projects into durable, repeatable earnings. The bearish analyst Narrative on Simply Wall St asks whether regional gas price shocks and timing risk on projects like Suriname and Alaska could upset that script.
"The numbers imply that APA's share price already reflects successful execution on cost savings, stable production from the Permian and Egypt, and meaningful future cash flow from Suriname and frontier exploration, which leaves limited room for disappointment."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 31% below our estimate - operates a large gold reserve base facing higher extraction and jurisdictional complexity.
- Company 2 - 40% below our estimate - converts subsea prospect lists into higher margin projects and recurring service work.
- Company 3 - 46% below our estimate - supplies full stack AI computing platforms as key customers add data center capacity.
Three companies from the same screener. Open every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com