


Dividend guidance and earnings shape the latest Targa Resources story
Targa Resources (TRGP) just paired a 2027 dividend guidance update with fresh third quarter numbers, giving investors new information on both income potential and recent operating performance.
The company plans to recommend a 20% uplift in its annual common dividend for 2027 to $6.00 per share, alongside guidance for 2026 net income of $2,490.0 million and detailed third quarter results.
Targa Resources has paired that guidance with a mixed stretch in the market, with the share price down 5.77% over the past week and 1.88% over the last month, yet still up 50.62% year to date and supported by a very strong 5 year total shareholder return of 472.97%, which signals momentum over the longer run.
Scan how Targa Resources stacks up against other income ideas by reviewing our hand picked 5 dividend fortresses built for investors who care about yield and staying power.
Targa Resources has paired double digit share gains this year with a short term pullback, leaving investors to parse whether the latest slip reflects changing sentiment or a disconnect with the fundamentals that now drive the valuation work.
Most Popular Narrative: 13% Undervalued
Targa Resources is trading at a last close of $281.32 against an analyst consensus Narrative fair value of $325.14. This frames the stock as discounted in that work, which uses a 7.24% discount rate from the analyst consensus Narrative on Simply Wall St.
The valuation suggests the share price already reflects a growth path supported by raised adjusted EBITDA guidance, long term producer and export contracts and a growing consensus of higher analyst price targets, yet it still leaves room if the company meets its Permian related volume and free cash flow plans.
See why 19 investors see Targa Resources as 13% undervalued.
Result: Fair Value of $325.14 (UNDERVALUED)
Still, the Targa Resources story can change quickly if Permian build out runs ahead of long term demand, or if large projects keep capital spending elevated for longer.
Find out about the key risks to this Targa Resources narrative.
Another View on Targa Resources Valuation
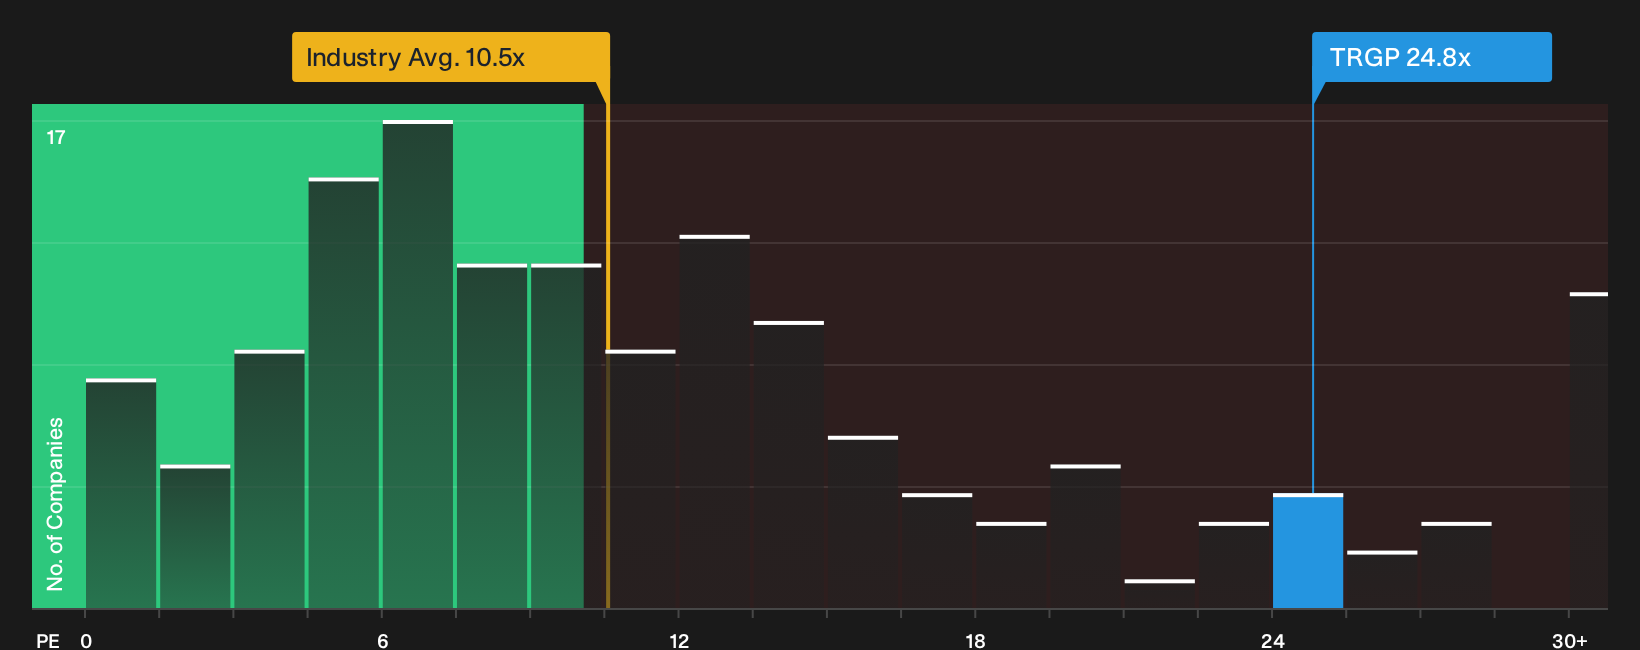
The earlier narrative framed Targa Resources as undervalued against a fair value of $325.14 per share. A different lens tells a cooler story. On a P/E of 24.8x, the stock trades well above the US Oil and Gas industry on 10.5x and above a fair ratio of 22.3x, which points to richer expectations and a narrower margin for disappointment.
For investors who lean on earnings multiples more than long term narratives, that premium raises a simple question: Is the higher price you are paying today for Targa Resources really compensated by the growth and risk profile you see ahead, or would a move closer to the fair ratio reshape the opportunity set in this sector?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Targa Resources feels familiar, treat it as a prompt to review the numbers yourself and consider your options before sentiment shifts. To weigh both sides clearly, start with the structured breakdown of 3 key rewards and 3 important warning signs
Looking for more Targa Resources sized investment ideas?
If Targa Resources has sharpened your focus on valuation and income, do not stop here. Broader idea generation can reveal opportunities you would otherwise never see.
- Target resilient performers by scanning a 30 resilient stocks with low risk scores that helps you focus on businesses with lower risk profiles and more robust fundamentals.
- Hunt for mispriced opportunities through a 20 high quality undiscovered gems tailored to highlight quality companies that many investors might still be overlooking.
- Strengthen your core holdings with a list of solid balance sheet and fundamentals (24 results) so you aim your capital at enterprises with sturdier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com