


- Sterling Infrastructure reported third quarter 2026 sales of US$1,563.93 million and net income of US$214.93 million. The company raised full year 2026 guidance to revenue of US$4.63 billion to US$4.73 billion and net income of US$596 million to US$604 million, and completed a 258,000 share buyback under its 2025 program.
- Management highlighted strong demand for mission critical infrastructure work in data centers and semiconductors, supported by a multiyear project pipeline and active acquisition efforts aimed at expanding capacity and geographic reach. The company is using its balance sheet and cash generation to support both organic projects and M&A.
- We will now look at how Sterling Infrastructure's upgraded 2026 earnings guidance could reshape the investment narrative around its mission critical backlog.
Scan how Sterling Infrastructure’s data center and semiconductor work compares with other potential beneficiaries of the AI build out by reviewing our hand picked 53 AI infrastructure stocks in the same space.
Sterling Infrastructure Investment Narrative Recap
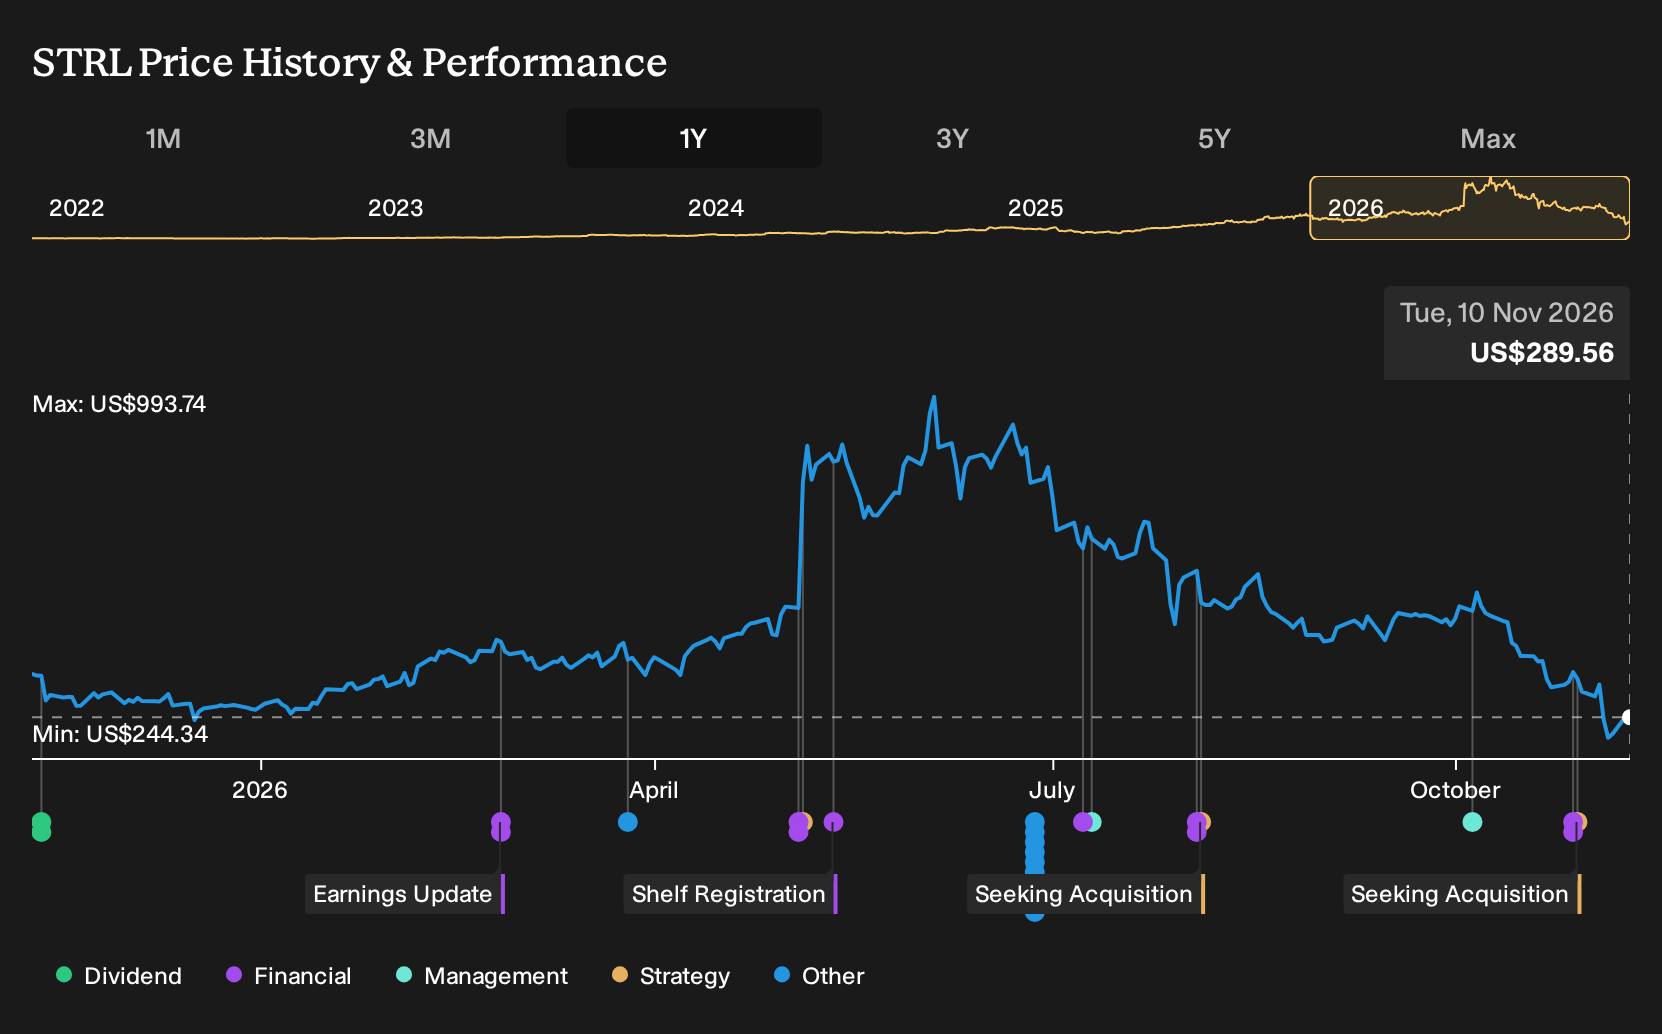
For Sterling Infrastructure, the big picture is simple. You need to believe the mission critical backlog in data centers and semiconductors can be executed with enough skilled labor, equipment and capital discipline to support the raised 2026 guidance. The recent earnings beat and guidance upgrade strengthen that case, while the stock’s sharp pullback reminds you that sentiment can swing far faster than contracts.
The near term swing factor is execution on the US$7b plus pool of signed and high probability work that the analyst consensus Narrative on Simply Wall St focuses on. The biggest risk sits on the same axis. Tight electrician supply, rising capital spending and any soft patch in new awards or campus phases could crimp visibility if project timing or utilization wobbles.
The most relevant recent update is the higher 2026 outlook, with revenue guided to a range of US$4.63b to US$4.73b and net income to a range of US$596m to US$604m. Those figures sit alongside very strong third quarter numbers and indicate that Sterling Infrastructure is already converting portions of its long dated AI infrastructure and semiconductor pipeline into current period earnings.
For you as an investor, that ties directly back to catalysts around multi year campuses, E Infrastructure margin work and acquisition led expansion discussed in the analyst consensus Narrative on Simply Wall St. Raised guidance and a completed US$133.34m buyback show management leaning into this setup, while execution risk around labor, backlog timing and heavier capital outlays remains firmly on the checklist.
Sterling Infrastructure's narrative ties to analyst expectations that revenues reach US$7.6b and earnings land at US$1.1b by 2029, based on forecast revenue growth of 21.0% a year and an earnings uplift of about US$545.7m from current earnings of US$554.3m.
Uncover why Sterling Infrastructure's fair value indicates a 173% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Sterling Infrastructure leans heavily on concentration risk. The most pessimistic analysts worry that dependence on data centers and semiconductor campuses could backfire if awards slow, which partly explains why they previously penciled in 2029 earnings of US$972.0 million on about US$7.2b of revenue. That sits below consensus and paints a cooler story, and the latest guidance and acquisition push may now prompt you to reassess how that cautious script holds up.
Explore 6 other Sterling Infrastructure fair value estimates, including one that suggests it could be worth just $679.88!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Sterling Infrastructure research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sterling Infrastructure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sterling Infrastructure's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sterling Infrastructure?
Sterling Infrastructure may be front of mind after this guidance update, but your portfolio is rarely built around a single story. Casting a wider net across different types of opportunities can help you compare risk, quality and income potential on the same screen.
- If you care about steadier profiles with fewer red flags, start with a curated set of resilient companies by scanning our 30 resilient stocks with low risk scores.
- For investors who want quality at a measured price, weigh Sterling Infrastructure against a hand picked group of attractively priced opportunities through the 36 high quality undervalued stocks.
- If balance sheet strength is non negotiable for you, line up Sterling Infrastructure alongside companies with robust finances by running the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com