


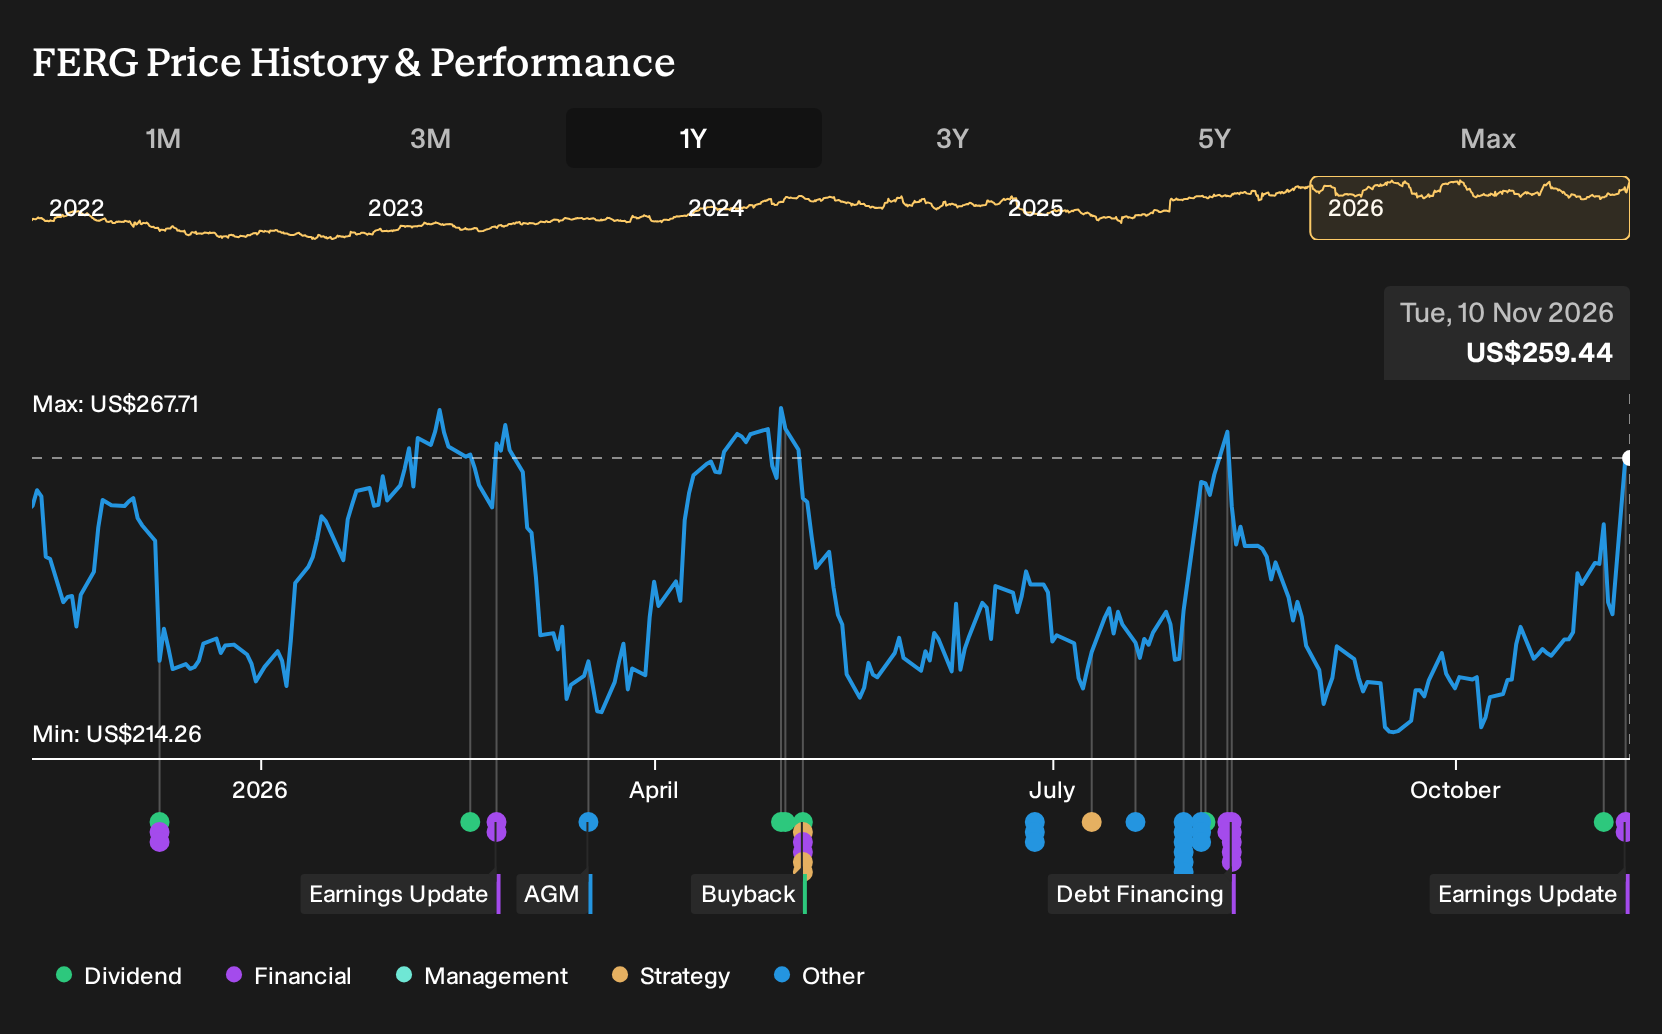
- Ferguson Enterprises reported past third quarter 2026 sales of US$9,026m with net income of US$598m and raised full year net sales growth guidance to about 7% following active acquisition spending.
- The mix of organic growth, contributions from deals such as FloWorks, and continued quarterly dividends highlights how Ferguson Enterprises is using its enlarged distribution platform to support both reinvestment and direct cash returns.
- The focus now turns to how Ferguson Enterprises' stronger guidance, built on organic and acquisition driven sales, reshapes the existing investment narrative.
Scan other distributors experiencing similar acquisition activity and guidance momentum by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) alongside Ferguson Enterprises' latest moves.
Ferguson Enterprises Investment Narrative Recap
To own Ferguson Enterprises, you need to believe the business can keep converting its North American scale, acquisitions like FloWorks, and large project exposure into steady sales and earnings, even with mixed end markets. The raised full year net sales outlook to about 7% growth points to management confidence in both organic activity and the enlarged platform.
The near term swing factor remains how quickly large non residential and industrial backlogs convert to revenue, while residential plumbing softness and commodity or PVC deflation still threaten pricing and margins. Integration of recent deals is another practical risk, especially if expected synergies take longer to show up in profitability.
The most relevant recent update is the higher full year 2026 guidance to roughly 7% net sales growth compared with prior mid single digit expectations. That sits alongside the analyst consensus narrative on Simply Wall St, which already highlights FloWorks and HVAC investments as key contributors to a much larger addressable market.
This upgraded outlook puts more weight on execution. Investors now have to watch whether Ferguson Enterprises can maintain non residential strength, manage residential pockets of weakness, and complete the integration of eleven acquisitions while absorbing higher leverage. Any stumble on integration or project timing would quickly test both margin resilience and confidence in that raised sales target.
Ferguson Enterprises' narrative projects US$39.0b revenue and US$2.7b earnings by 2029. This assumes 7.5% yearly revenue growth and an earnings increase of about US$700m from current earnings of US$2.0b.
Uncover why Ferguson Enterprises' fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Ferguson Enterprises’ heavier HVAC and Waterworks investment as a potential upside swing factor. Before this guidance hike, that bullish camp was already modeling about US$40.2b in revenue and US$2.8b in earnings by 2029. You can compare those higher expectations with today’s results to see how opinions might shift from here.
Explore 2 other Ferguson Enterprises fair value estimates, including one that suggests up to 25% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ferguson Enterprises research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ferguson Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ferguson Enterprises' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ferguson Enterprises?
Once you have a view on Ferguson Enterprises, it can help to widen the lens and compare it with other companies that share similar qualities or offer different risk and income profiles.
- If you want potential mispricing combined with resilient financials, start with a focused set of 20 high quality undiscovered gems that may not yet be widely followed.
- For investors who prefer steadier balance sheets over story driven growth, filter the market using our 30 resilient stocks with low risk scores to narrow in on businesses with more measured risk scores.
- If income is your priority and you care about yield support, use the curated 5 dividend fortresses to zero in on companies offering higher dividend payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com